
 CA
 NZ
 UK
 US
 IND

 AU
 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
- Technology Maintains Strongest Momentum: Information Technology (XIJ) continues to occupy the strongest position across the chart, with its latest endpoint extending towards the upper-right region of Leading, indicating exceptionally positive relative strength and momentum.
- Four Sectors Remain in Leading: Information Technology (XIJ), Property (XPJ), Industrials (XNJ) and Telecommunications (XTJ) maintain their positions in Leading, demonstrating positive relative strength and momentum against the benchmark.
- Materials and Resources Remain Improving: Materials (XMJ) and Resources (XJR) continue to occupy Improving, indicating positive momentum despite negative relative strength.
- Financials, Healthcare and Consumer Discretionary Move into Weakening: Financials (XFJ), Health Care (XHJ) and Consumer Discretionary (XDJ) occupy the lower-right quadrant, reflecting negative momentum despite positive relative strength.
- Three Sectors Continue to Lag: Consumer Staples (XSJ), Energy (XEJ) and Utilities (XUJ) remain in Lagging, highlighting persistent weakness in both relative strength and momentum.
The latest chart therefore shows a distribution of four sectors in Leading, three in Weakening, two in Improving and three in Lagging. The overall configuration indicates that the Leadership group remains unchanged, with Information Technology maintaining a particularly strong momentum advantage. Property, Industrials and Telecommunications also retain positive relative strength and momentum, although their latest directional trajectories differ considerably. Meanwhile, Materials and Resources continue to demonstrate positive momentum despite remaining below the vertical reference axis. However, Financials, Health Care and Consumer Discretionary remain in negative momentum territory, while Consumer Staples, Energy and Utilities continue to occupy the weakest relative positions. The plotted trails illustrate the evolution of sector positioning over the six-period look-back, with the latest endpoint determining the current quadrant classification.
ASX Sector Momentum Quadrants
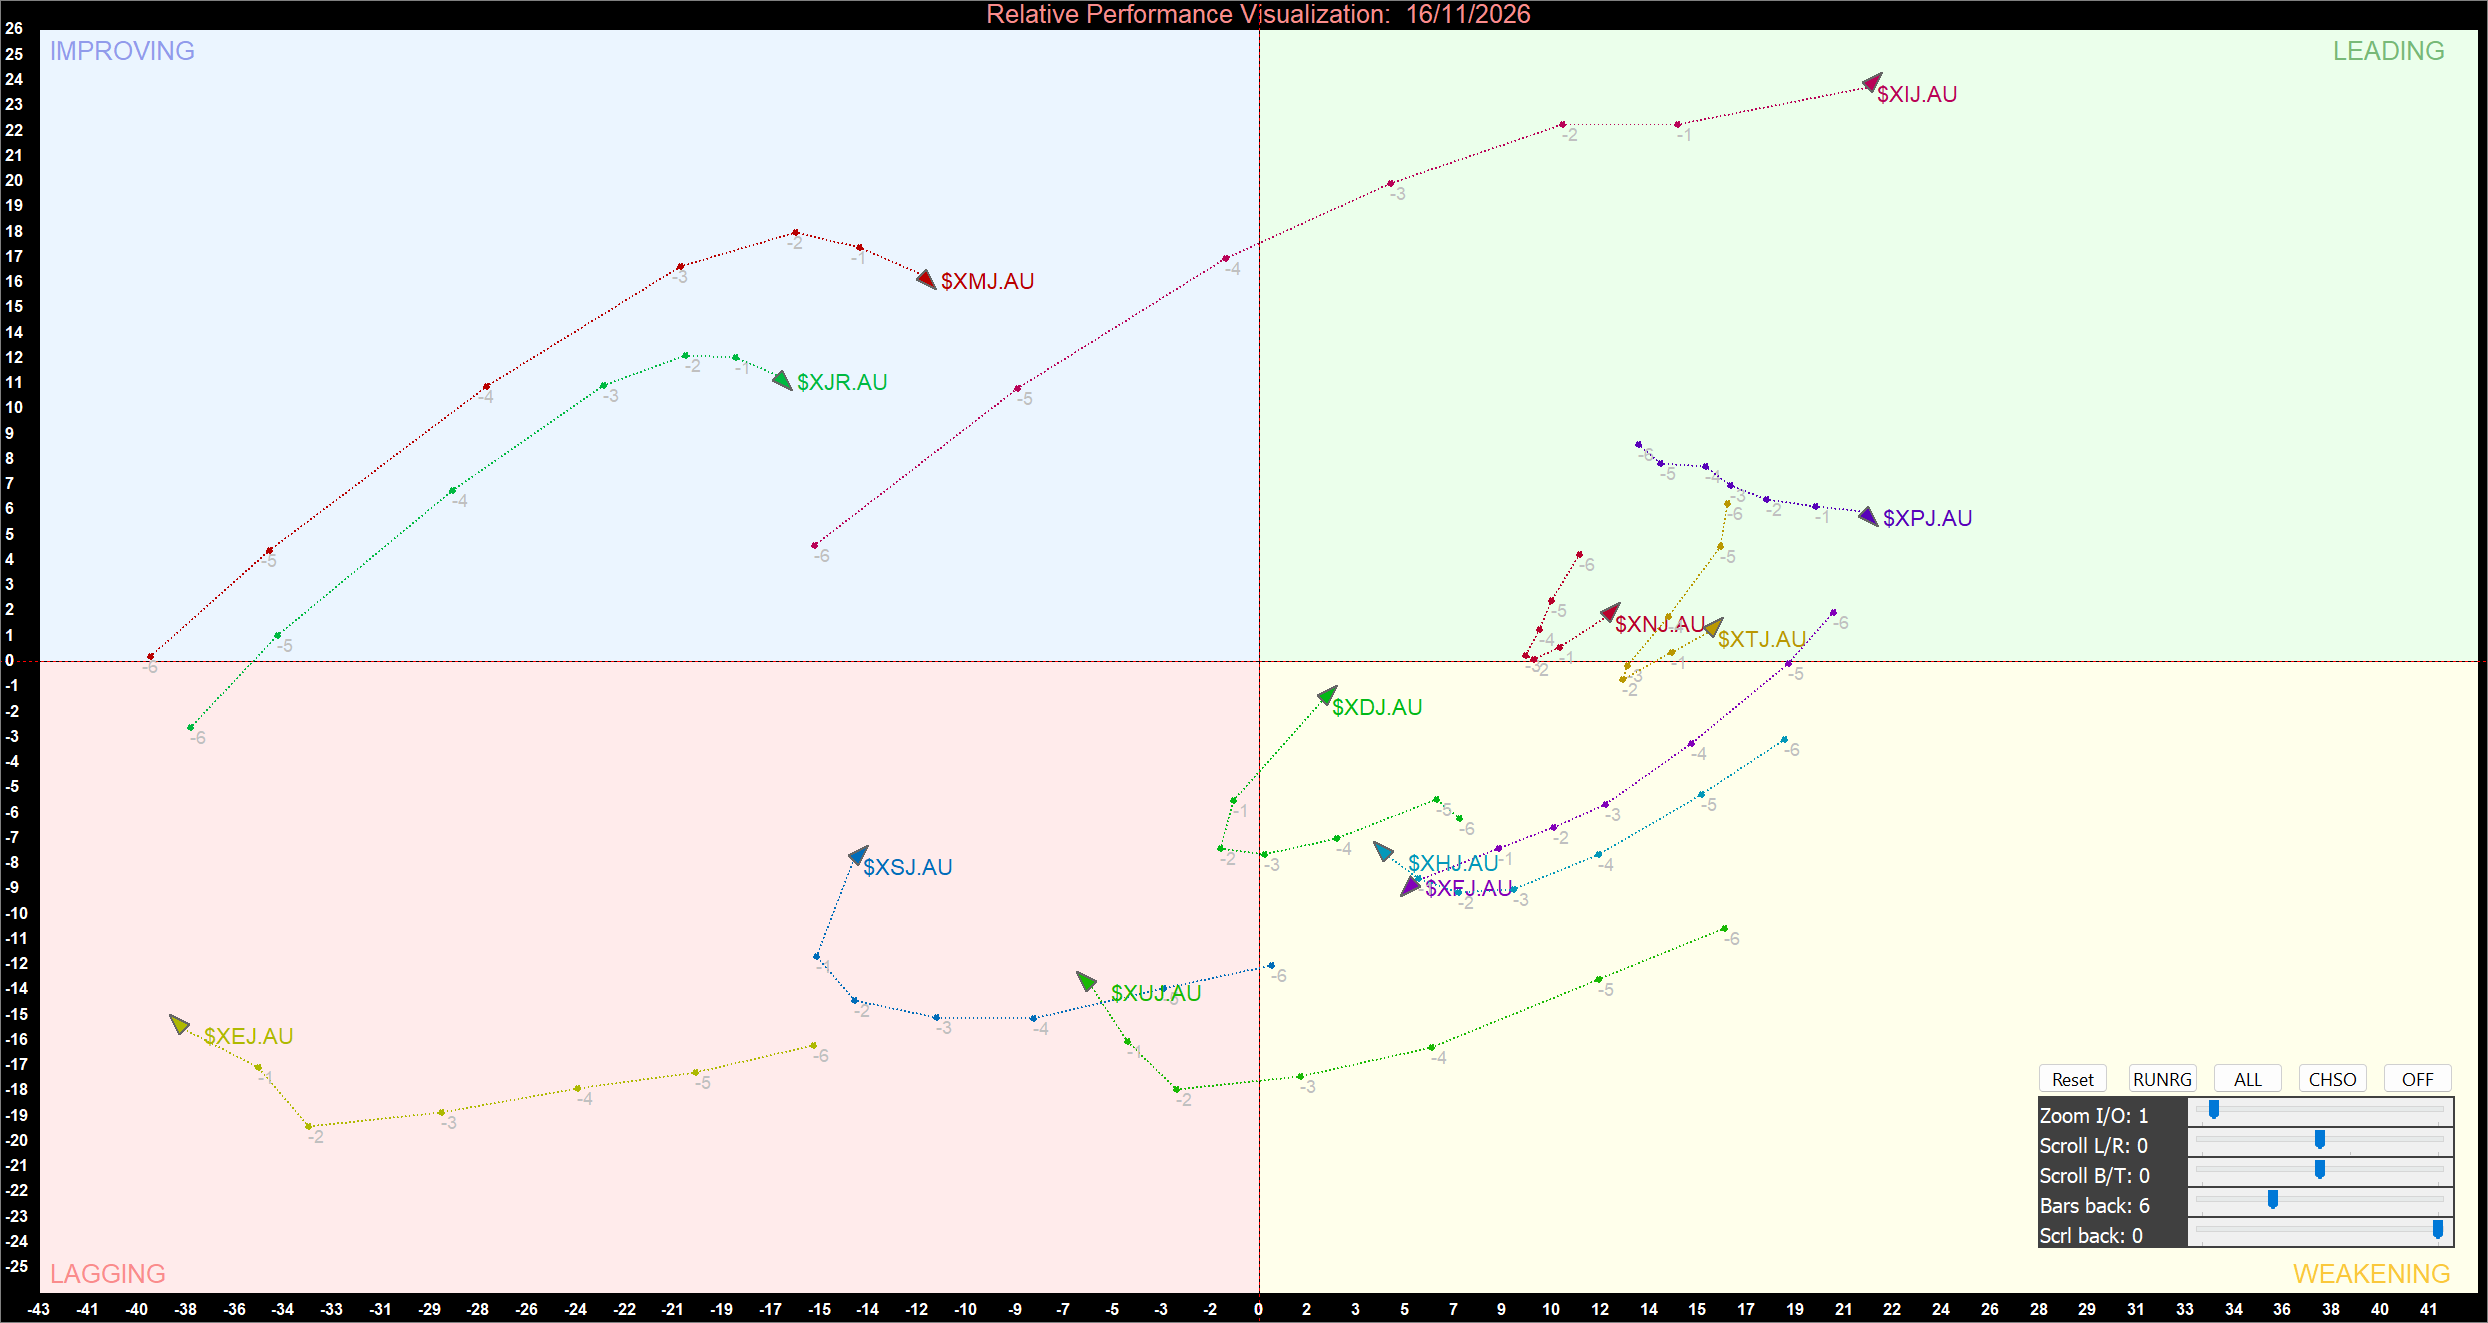
ASX Sector Relative Momentum Chart (at the closing price of 16/11/2026). Powered by AmiBroker.
Information Technology Maintains Leadership as Four Sectors Remain in Leading
Four of the twelve sector indices are positioned in the Leading quadrant. Information Technology (XIJ), Property (XPJ), Industrials (XNJ) and Telecommunications (XTJ) have their latest endpoints above the horizontal axis and to the right of the vertical axis. This configuration indicates positive relative strength and positive momentum against the benchmark. However, their latest directional trajectories reveal considerably different momentum characteristics, with Information Technology demonstrating the strongest position.
Information Technology remains the strongest-positioned sector across the entire chart, with its latest endpoint located near the upper-right boundary of Leading. Its sharply upward and rightward trajectory over the six-period look-back indicates a substantial acceleration in momentum. The sector has moved considerably higher from its previous positions, suggesting that positive momentum continues to strengthen. Its considerable distance from the central reference area highlights its significant relative momentum advantage over the other sector indices.
Property also remains within Leading, although its latest trail displays a downward directional movement. This suggests that momentum has moderated despite maintaining positive relative strength. Its latest endpoint remains comfortably above the horizontal reference line, but continued downward movement could eventually result in a transition into Weakening.
Industrials and Telecommunications also maintain positions in Leading. Both sectors are located relatively close to the horizontal reference boundary, indicating comparatively moderate positive momentum. Their latest trajectories suggest continued positive relative strength, although their momentum advantages are considerably less pronounced than that of Information Technology. Telecommunications remains particularly close to the horizontal boundary, making its classification more sensitive to relatively small changes in momentum.
The distinction between quadrant positioning and directional movement remains important. All four sectors retain their Leading classification as long as their latest endpoints remain above the horizontal axis and to the right of the vertical axis. Continued upward and rightward movement would reinforce their momentum positions, while a decline below the horizontal reference line would signal a transition into Weakening.
Financials, Health Care and Consumer Discretionary Remain in Weakening
Financials (XFJ), Health Care (XHJ) and Consumer Discretionary (XDJ) occupy the Weakening quadrant. Their latest endpoints remain to the right of the vertical axis but below the horizontal axis, indicating positive relative strength alongside negative momentum. These sectors therefore retain a relative-strength advantage against the benchmark, although their momentum readings remain below the zero line.
Financials remains within negative momentum territory, with its latest endpoint positioned below the horizontal reference line. Although its plotted trail indicates a recovery from earlier positions, this improvement has not yet translated into positive momentum. A sustained move above the horizontal boundary would provide the first confirmation of a transition into Leading.
Health Care also remains in Weakening, with its latest endpoint positioned considerably below the horizontal axis. Its negative momentum reading indicates that relative performance continues to deteriorate despite maintaining positive relative strength. Although the plotted trajectory suggests some recovery from earlier readings, momentum remains insufficient to establish a Leading classification.
Consumer Discretionary is positioned closer to the central reference area, suggesting comparatively less severe negative momentum than the other two sectors. Nevertheless, its latest endpoint remains below the horizontal axis, confirming that momentum has yet to recover into positive territory.
All three sectors would need to move above the horizontal reference line while maintaining positive relative strength to return to Leading. Conversely, a move to the left of the vertical axis while momentum remained negative would signal a rotation into Lagging.
Materials and Resources Maintain Improving Positions
Materials (XMJ) and Resources (XJR) remain positioned in the Improving quadrant. Their latest endpoints are above the horizontal axis but to the left of the vertical axis, indicating positive momentum despite negative relative strength. This configuration suggests that their momentum conditions remain favourable relative to previous readings, although neither sector has yet established positive relative strength or entered Leading.
Materials is positioned considerably higher within Improving, indicating a stronger momentum reading than Resources. Its latest endpoint remains well above the horizontal reference line, reflecting a substantial positive momentum position. However, its recent directional movement indicates some moderation following the earlier advance.
Resources also maintains positive momentum, with its latest endpoint located above the horizontal axis. Its plotted trajectory indicates a comparatively weaker momentum position than Materials. Nevertheless, its current classification confirms that momentum remains positive despite continued negative relative strength.
A sustained move to the right of the vertical axis while remaining above the horizontal axis would confirm a transition into Leading. Continued upward and rightward movement would provide stronger confirmation that improving momentum is translating into positive relative strength. Conversely, a renewed decline below the horizontal reference line would return either sector to Lagging.
Energy, Consumer Staples and Utilities Remain in Lagging
Consumer Staples (XSJ), Energy (XEJ) and Utilities (XUJ) continue to occupy the Lagging quadrant. Their latest endpoints remain to the left of the vertical axis and below the horizontal axis, indicating negative relative strength and negative momentum. Their positions confirm that they remain among the weakest groups in the current relative rotation configuration.
Energy is positioned substantially further left than the other two sectors, reflecting particularly weak relative strength alongside negative momentum. Despite some upward movement in its plotted trail, its latest endpoint remains deep within negative relative strength territory. This suggests that the sector has yet to establish a meaningful recovery against the benchmark.
Utilities also remains deeply within negative momentum territory, although its latest endpoint is positioned closer to the vertical reference axis. Its plotted trail demonstrates some recovery from previous weaker readings, suggesting that momentum deterioration may be stabilising. Nevertheless, the sector remains firmly within Lagging.
Consumer Staples occupies a relatively weak position, with its latest endpoint remaining considerably below the horizontal reference line. Its trajectory indicates that momentum has yet to recover meaningfully, while relative strength remains negative.
A sustained move above the horizontal axis would provide the first indication of improving momentum and shift any of these sectors into Improving. A subsequent move to the right of the vertical axis would be required to establish positive relative strength and enter Leading. Until such movements occur, their current positioning suggests that momentum conditions remain unfavourable.
Bottom Line
The ASX sector momentum chart for 16 November 2026 shows four sectors in Leading: Information Technology, Property, Industrials and Telecommunications. Information Technology maintains the strongest momentum position, with its latest trajectory indicating a substantial acceleration in positive momentum. Property remains in Leading despite some moderation, while Industrials and Telecommunications retain comparatively moderate positive momentum. Financials, Health Care and Consumer Discretionary occupy Weakening, reflecting negative momentum despite positive relative strength. Materials and Resources remain in Improving, with both sectors maintaining positive directional momentum. Energy, Consumer Staples and Utilities continue to lag, indicating persistent weakness in relative strength and momentum. Overall, the configuration highlights the continued dominance of Information Technology, supported by a stable leadership group, while Materials and Resources retain improving momentum. Subsequent RRG readings will be important in determining whether the improving sectors can transition into Leading and whether the existing leadership group can sustain its positive momentum.

 Nov 18, 2026
 Please wait processing your request...