
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Source: Krish Capital Pty Ltd
Index Update: The S&P/ASX 200 closed higher on Friday, adding 59.90 points or 0.68% to finish at 8,864.90. Despite the positive session, the benchmark index remains 2.09% below its 52-week high and was broadly flat over the past five trading days. Seven of the eleven sectors advanced, led by materials, which rose +1.45% as it recovered from recent weakness, though it remains slightly down (-0.10%) over the week. A-REITs (+1.35%) and financials (+1.16%) also posted notable gains, while energy was the major drag, dropping -2.43% on the day.
Macro Update: US inflation rose 2.9% in August, the highest since January, as firms passed Trump-era tariffs on to consumers. Core CPI held steady at 3.1%, signalling stable underlying price pressures. Despite the uptick, Wall Street expects the Federal Reserve to cut rates by 25 basis points next week, citing a cooling labour market. Market participants remain cautiously optimistic about monetary easing as rates stand at 4.25%–5.5%.
Top Market Movers: Bellevue Gold Limited (ASX: BGL) led the gains on Friday, rising 7.18% to close at AUD 0.97, followed by Regis Resources Limited (ASX: RRL), which climbed 6.42% to AUD 5.80. Guzman y Gomez Limited (ASX: GYG) also advanced 6.41% to finish at AUD 25.22. On the downside, Mesoblast Limited (ASX: MSB) fell 4.74% to AUD 2.21, Aristocrat Leisure Limited (ASX: ALL) dropped 3.97% to AUD 67.47, while Woodside Energy Group Ltd (ASX: WDS) declined 3.39% to AUD 24.22.
Commodity Update: The dollar weakened Friday as higher U.S. jobless claims and a slight rise in inflation reinforced expectations of Federal Reserve rate cuts. Gold gained 0.23% to USD 3,685.85, silver climbed 0.87% to USD 42.51, and copper edged up 0.16% to USD 10,080.20. Brent crude slipped 0.50% to USD 66.03, pressured by weak demand and ample supply, though supported by geopolitical tensions in Russia-Ukraine and the Middle East, alongside potential U.S. sanctions on Moscow.
Our Stance: The S&P/ASX 200 finished the week on a positive note, with broad-based sector gains offsetting earlier weakness. Materials led the recovery, supported by rebounds in key commodities, though energy lagged on soft demand signals. Market sentiment remains cautiously constructive, buoyed by expectations of imminent U.S. rate cuts despite a slight inflation uptick. Stable core CPI and a cooling labour market reinforce views of forthcoming monetary easing. Equity performance was mixed, with notable strength in gold and consumer-facing stocks, while energy and biotech faced selling pressure. Overall, the market shows cautious resilience, but near-term moves will hinge on the Fed’s decision and global growth signals.
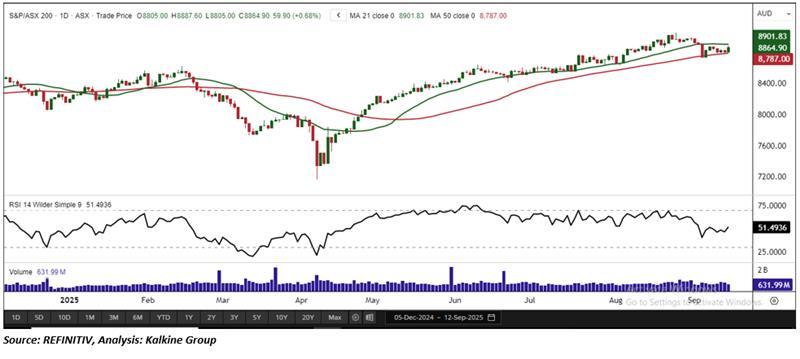
In its latest session, the S&P/ASX 200 Index advanced 59.90 points to close at 8,864.90, supported by a bullish candlestick formation accompanied by strong trading volumes clear signals of sustained investor confidence. On the daily chart, the index continues to hold firmly above its 50-period Simple Moving Average (SMA), a dynamic support level that reinforces the prevailing positive short-term outlook. A critical support zone has been established at 8,780, and maintaining levels above this threshold will be essential to preserving the integrity of the current uptrend. On the upside, a decisive breakout above this support-turned-resistance area could serve as a strong bullish confirmation, potentially unlocking further upward momentum and shifting broader market sentiment more decisively in favor of the bulls. From a broader perspective, the index’s sustained position above the 21-period SMA on the weekly chart underscores its resilient long-term bullish foundation, highlighting continued strength across multiple timeframes.


 Nov 12, 2026





 Please wait processing your request...