
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
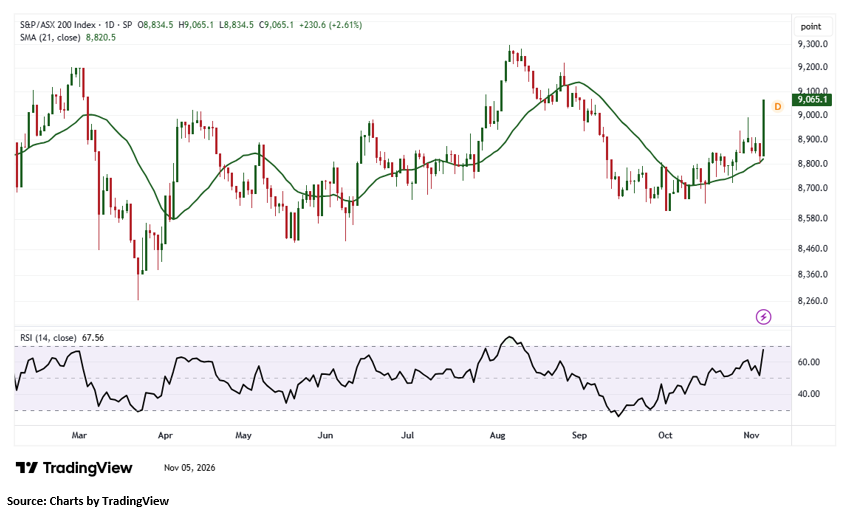
Index Update: The S&P/ASX 200 surged 230.60 points (2.61%) on Thursday to close at 9,065.10, marking a fresh 20-day high. The index gained 1.95% over five sessions and remained 2.49% below its 52-week peak. Eight of 11 sectors finished higher, with Information Technology leading at 10.09%, followed by Materials (7.55%) and Healthcare (3.64%). Technology also gained 9.41% over five sessions, while Energy (-4.76%) and Utilities (-1.51%) recorded declines, highlighting contrasting sector performances.
Macro Update: Australia’s seasonally adjusted goods Trade Surplus rose by AUD 2.64 billion to AUD 2.83 billion in September 2026, according to the ABS. Exports increased 2.3% to AUD 48.43 billion, driven by mineral fuels and metals, while imports declined 3.3% to AUD 45.61 billion.
Meanwhile, public sector employment grew 2.3% in 2025–26, the slowest annual increase since 2019–20. Total public sector wages reached AUD 266.1 billion, rising 6.6%, compared with 7.8% previously. Healthcare employment increased 4.4%, while education jobs expanded 2.3% during the financial year.
Top Market Movers: NEXTDC Limited (ASX:NXT) led the ASX 200 gainers, surging 50.842% or AUD 3.320 to AUD 9.850, followed by Catalyst Metals Limited (ASX:CYL), which advanced 18.338% or AUD 0.640 to AUD 4.130. Vulcan Energy Resources Limited (ASX:VUL) gained 18.181% to AUD 1.235. Among the losers, Eagers Automotive Limited (ASX:APE) declined 13.219% to AUD 16.610, while Amcor PLC (ASX:AMC) fell 7.794% to AUD 62.110. Codan Limited (ASX:CDA) dropped 6.170% or AUD 3.690 to AUD 56.120, rounding out the three biggest decliners for the session.
Commodity Update: The US dollar retreated on Thursday but recovered from earlier lows after Democrats secured a sweeping victory in the US midterm elections, reducing political uncertainty as markets assessed potential regulatory changes. Gold gained 1.77% to USD 4,145.70, while silver advanced 1.00% to USD 53.22. Copper edged up 0.06% to USD 14,086.00. Meanwhile, Brent Crude oil declined 0.56% to USD 94.10 as investors assessed whether the election outcome could increase pressure on President Donald Trump to end the war with Iran.
Our Stance: The ASX 200’s sharp rebound to a 20-day high signals improving market momentum, supported by broad-based sector gains and particularly strong performances in technology and materials. Australia’s widening trade surplus provides a constructive economic backdrop, while moderating public sector employment growth points to a more measured labour market expansion. However, steep declines in energy and select heavyweight stocks highlight continued market divergence. Rising gold and silver prices add another dimension to Commodity sentiment, even as oil prices soften. Overall, the market appears to be regaining confidence, although uneven sector performance suggests investors may remain selective in the near term.
From a technical perspective, the S&P/ASX 200 Index advanced in the latest trading session, signalling signs of stabilisation following the recent pullback. The index continues to hold above the key support level of 9,010.50, which remains crucial for maintaining its broader technical structure. Sustained trading above this level could improve investor sentiment and support further recovery towards recent highs. On the upside, immediate resistance is positioned near 9,105.50, while a decisive breakout above this level could strengthen bullish momentum and open the door for a further advance towards 9,160.70. Conversely, a sustained break below 9,010.50 could invalidate the recovery attempt and expose the index to renewed selling pressure.


 Nov 12, 2026




 Please wait processing your request...