
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
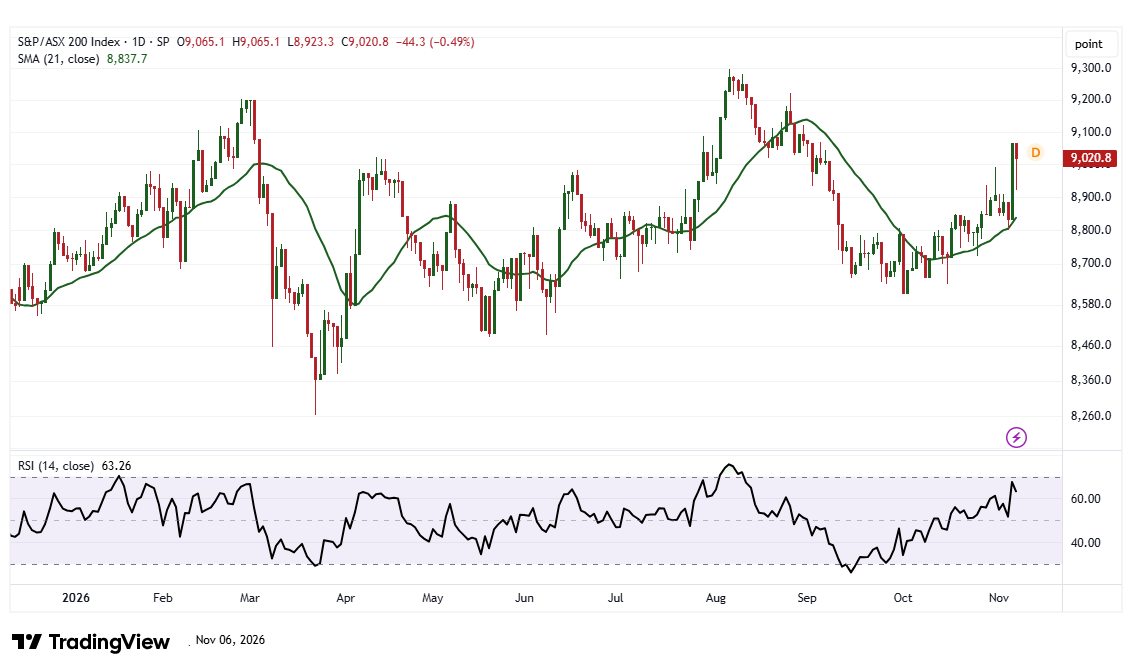
Index Update: The S&P/ASX 200 slipped 44.30 points, or 0.49%, to 9,020.80 on Friday, retreating after reaching a fresh 20-day high. Despite the decline, the benchmark advanced 1.27% over five sessions and remained 2.97% below its 52-week peak. Seven of 11 sectors ended lower, led by Materials, down 2.51%. Consumer Staples topped sector gains, rising 1.41% on the day and 4.83% over five days. Financials, telecommunications and utilities also advanced.
Macro Update: Markets faced pressure from uncertainty over economic growth, rising government borrowing costs and concerns that Inflation may remain elevated into 2027. According to reports, confidence in the artificial intelligence rally has weakened, while softer European data has added to further worries. Oil prices fell almost 20% this week to below USD 100 a barrel amid hopes of easing tensions in the Iran war, although crude remains nearly 60% higher this year. Moreover, according to The University of Michigan's measure, US one-year inflation expectations edged up to 4.7% in October.
Top Market Movers: Top gainers of Friday included Nine Entertainment Co. Holdings Limited (ASX:NEC), up AUD 0.085, or 11.643%, at AUD 0.815. NEXTDC Limited (ASX:NXT) advanced AUD 0.550, or 5.583%, to AUD 10.400, while Amcor plc (ASX:AMC) gained AUD 2.900, or 4.669%, to AUD 65.010. Decliners included Develop Global Limited (ASX:DVP), down AUD 0.400, or 10.127%, to AUD 3.550; Vulcan Energy Resources Limited (ASX:VUL) declined AUD 0.120, or 9.717%, to AUD 1.115; and News Corporation (ASX:NWS) dropped AUD 4.410, or 9.289%, to AUD 43.070.
Commodity Update: The US dollar held steady against major currencies on Friday as a sharp selloff in US equities increased Demand for safe-haven assets, including the Japanese yen, while Treasury yields declined ahead of the closely watched US payrolls report. Gold fell 0.91% to USD 4,076.20, silver declined 0.67% to USD 51.98, and copper slipped 0.18% to USD 13,777.00. Brent Crude gained 0.31% to USD 99.50 amid Middle East Supply disruption concerns.
Our Stance: The Australian Equity market remains vulnerable to near-term Volatility as persistent inflation concerns, elevated borrowing costs and uncertainty surrounding global economic growth weigh on investor sentiment. The S&P/ASX 200’s weekly advance suggests underlying resilience, although weakness in Materials highlights uneven sector performance. Gains in Consumer Staples, Financials and Utilities indicate selective interest in defensive sectors. Meanwhile, fluctuating oil prices, geopolitical tensions and shifting expectations around Monetary Policy could influence market direction. Corporate earnings, Commodity price movements and upcoming economic indicators remain important factors to monitor. A cautious near-term outlook appears appropriate, with sector-specific developments likely to shape market performance.
From a technical perspective, the S&P/ASX 200 index declined during the latest Trading session but continues to maintain a cautiously constructive near-term outlook. The index is holding above key support at 8,980.40, which remains critical to preserving the broader bullish structure. Sustained trading above this level could stabilise market sentiment and support a recovery towards recent highs. Immediate resistance is positioned near 9,060.50, while a decisive breakout above this level could strengthen bullish momentum and open the way towards the next target of 9,100. Conversely, a sustained break below 8,980.40 could weaken the positive technical outlook and expose the index to further downside pressure.


 Nov 12, 2026




 Please wait processing your request...