
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Investment Highlights
- Yancoal reported record run-of-mine production of 67 million tonnes for FY25.
- The company successfully lowered cash operating costs to $92/tonne.
- The board has restored the dividend at a 55% payout ratio.
- With $2.1 billion in cash and zero interest-bearing debt, Yancoal is arguably the strongest balance sheet play in the ASX energy sector.
After the volatility of 2024, the price action suggests a significant shift in supply and demand dynamics. As we move through the first quarter of 2026, the question isn't just about coal prices, it's about whether the "turnaround story" is finally confirmed by the tape.
The Engine Behind the Move
- Yancoal’s fundamental turnaround is anchored by its transition from a debt-heavy producer to a cash-generating powerhouse. The company’s ability to maintain a zero-debt position while amassing a $2.1 billion cash pile provides a massive margin of safety that was absent in previous cycles.
- By optimizing production to reach 38.6 million tonnes of saleable coal and disciplined cost-cutting, YAL has decoupled its survival from short-term commodity price spikes. This structural efficiency, combined with the reinstatement of fully-franked dividends, has forced a re-rating of the stock from a speculative play to a staple for institutional income seekers.
Associated Risks
- Despite the operational "clean-up," Yancoal remains a high-beta play sensitive to the global thermal coal price.
- Furthermore, while the current cash pile of $2.1 billion is a strength, there is execution risk regarding how management deploys this capital; an overpriced acquisition or a shift back to dividend suppression could derail the current recovery in investor sentiment.
Technical Outlook
The price action appears to validate the stock's turnaround narrative.
Yancoal (ASX:YAL)
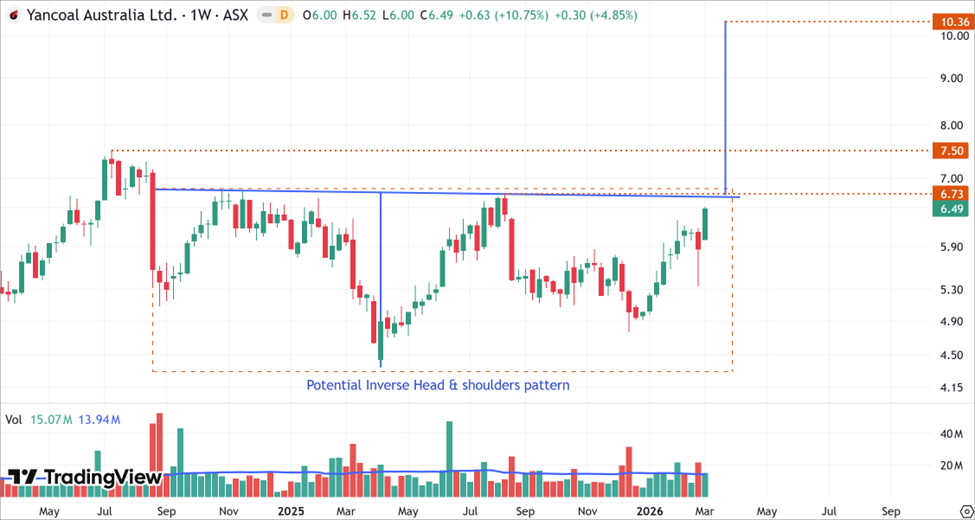
YAL’s Weekly Price Chart (at the closing price of 03rd March 2026). Powered by: tradingview.com
- On the weekly chart, YAL’s stock price is developing a potential Inverse Head and Shoulders pattern but has not completed yet, suggesting a possible long-term trend reversal from bearish to bullish.
- The pattern’s neckline is situated at $6.73; a decisive breakout above this level, ideally supported by a breakaway gap or strong trading volume, could propel the stock toward the projected target of $10.36.
- While this target sits above the significant resistance formed by the July 2024 high, selling pressure may emerge at that peak, potentially creating a pullback before the stock ultimately reaches the final target.
The Bottom Line
- Ultimately, Yancoal is currently in a critical "coiling" phase as it tests major multi-year resistance. The confluence of a massive Inverse Head and Shoulders formation and a "clean" balance sheet suggests that the stock is primed for a significant structural shift.
- While the fundamental engine is firing on all cylinders, supported by record production and restored dividends, the final confirmation lies with the price action. A high-volume weekly close above the $6.73 neckline would likely trigger a wave of technical buying, validating the turnaround story and clearing a path toward the ambitious $10.36 target.
- Until that breakout is secured, however, investors should remain mindful of coal price volatility and the potential for a "bull trap" at the current ceiling.


 Nov 12, 2026





 Please wait processing your request...