
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Company Overview
Vysarn Ltd is an ASX-listed specialist provider of hydrogeological services and water management solutions to the resources sector, particularly gold, lithium, and base metals miners operating in Western Australia's remote and arid mining regions. The company's services include dewatering, water supply, drilling, and environmental water management — all critical inputs for mine operations where water is simultaneously a safety concern (preventing flooding) and a scarce resource (required for ore processing).
As Western Australia's mining boom continues, driven by gold and lithium demand, the need for sophisticated water management expertise has grown substantially. Vysarn has positioned itself as a specialist provider capable of managing complex hydrogeological challenges that generalist mining services contractors cannot handle with the same technical depth. The company has built a fleet of specialist drilling rigs, pumping systems, and monitoring infrastructure that provides a physical barrier to competitive entry.
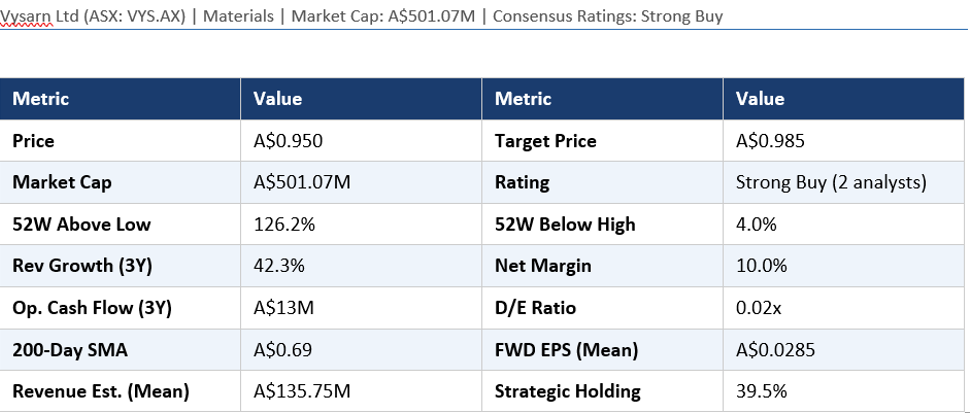
Strategic entities hold 39.5% of shares, reflecting high founder and institutional alignment. Revenue has grown at 42.3% per annum over three years, driven by the expansion of its service fleet and deepening relationships with major mining clients. Vysarn operates in a market with structural growth — more mines are being developed, existing mines are going deeper where dewatering complexity increases, and environmental regulations are mandating more rigorous water management.
Fundamental Insights
Vysarn's fundamentals confirm rapid growth at scale. Three-year revenue CAGR of 42.3% is outstanding for an industrial services business, driven by fleet expansion, workforce scaling, and new contract wins with major mining clients. Net profit margin of 10.0% reflects a services business with significant variable labour and equipment costs, and while modest by some standards, it is appropriate for the capital-intensive nature of specialist drilling operations.
Operating cash flow of A$13 million over three years confirms the business generates real cash despite its growth phase investment, and the near-debt-free balance sheet (D/E of 0.02x) is extraordinary for a capital-intensive services business — it means Vysarn has funded its fleet expansion primarily through earnings retention and equity.
Two analysts provide forward estimates with EPS projected at A$0.0285-A$0.030 and revenue at A$132.7-A$138.8 million. At the current price of A$0.95, the forward P/E is approximately 33x — elevated relative to the margin profile but consistent with the high growth rate. The 200-day SMA of A$0.69 well below the current price confirms a powerful uptrend driven by genuine fundamental re-rating.
Broker Views and Analyst Consensus
Two analysts cover Vysarn, with one Strong Buy and one Buy rating, and a consensus target of A$0.985 implying 3.7% upside from the current A$0.95. The narrow gap between price and target suggests the market has largely priced in the near-term fundamental case, but both analysts maintain positive ratings because the medium-term growth story remains intact.
The broker thesis centres on the structural growth in Western Australian mining services demand, Vysarn's specialist positioning in hydrogeological services where competitive depth is limited, and the company's conservative balance sheet that gives management flexibility to accelerate growth through additional fleet investment without financial stress. The 39.5% strategic shareholding signals alignment between management and long-term growth objectives.
Key risks include exposure to the Western Australian mining cycle, client concentration in a small number of major mining companies, and the capital intensity of maintaining and expanding the specialist drilling fleet. Labour market conditions in WA's Fly-In-Fly-Out mining workforce are also a cost sensitivity for service providers.
Technical Analysis
Vysarn has surged 126.2% above its 52-week low and trades only 4.0% below its 52-week high — positioning near the top of its annual range after a very strong recovery. The 200-day SMA at A$0.69 is dramatically below the current price of A$0.95, confirming an entrenched uptrend. The stock appears to be in the final stages of approaching its 52-week high, which will be the next technical test.
A break above the 52-week high with volume would be a significant bullish signal targeting the A$1.00+ zone. Support sits at A$0.90 (near-term) and A$0.85. With the price essentially at consensus target (A$0.985), the stock may need a fundamental catalyst such as a contract win announcement or earnings upgrade for the next material move higher. RSI is likely elevated after the strong run.
Investor Insights
Vysarn is a quality mining services growth story with strong execution credentials. The near-consensus valuation means current buyers are paying fair value rather than a discount, but the medium-term earnings growth supports continued holding. For investors, a pullback toward A$0.90 would offer a better entry point. For existing holders, the Strong Buy/Buy consensus and intact growth story support holding through current levels. Watch for contract announcement catalysts that could drive analyst estimate upgrades and push the stock above current target prices.
Disclaimer: This article is for informational and educational purposes only and does not constitute financial advice or a recommendation to buy or sell any security. Investors should conduct independent due diligence and seek advice from a licensed financial adviser before making any investment decisions. Past performance is not indicative of future results. All figures sourced from publicly available market data.


 Nov 12, 2026





 Please wait processing your request...