
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
- Six Sectors Remain in Leading: Energy (XLE), Health Care (XLV), Materials (XLB), Communication Services (XLC), Financials (XLF) and Consumer Staples (XLP) remain in the Leading quadrant.
- Energy Maintains Leadership: XLE remains firmly positioned in Leading after gaining 1.11% during the session.
- Utilities Strengthen: Utilities (XLU) remains in Improving after advancing 0.86%, indicating recovering relative momentum.
- Health Care Maintains Strong Momentum: XLV remains in Leading despite declining 2.52%, demonstrating the difference between daily performance and relative momentum.
- Real Estate Remains Improving: XLRE is positioned in Improving, indicating strengthening momentum without established leadership.
- Technology Remains Lagging: XLK gained 0.32% but remains in Lagging, showing that the recent price improvement has not yet translated into stronger relative momentum.
- Industrials and Consumer Discretionary Remain Lagging: XLI and XLY remain below the RRG midpoint, with declines of 0.48% and 0.80%, respectively.
- No Sectors in Weakening: The absence of sectors in Weakening indicates that the current rotation remains relatively constructive, with weakness concentrated in the Lagging quadrant.
The latest US sector momentum visualization for 8 September 2026 shows six sectors positioned in Leading, two in Improving and three in Lagging, with no sectors in Weakening. Energy, Health Care, Materials, Communication Services, Financials and Consumer Staples remain in Leading, while Utilities and Real Estate occupy Improving. Technology, Industrials and Consumer Discretionary remain in Lagging. This follows the quadrant-based framework of the reference analysis.
The latest daily performance data also highlights a notable divergence between short-term price performance and relative momentum. Energy and Utilities recorded positive daily returns and remain in stronger quadrants, while Technology also gained but continues to sit in Lagging. Conversely, Health Care recorded the largest decline but remains in Leading, reinforcing that RRG positioning reflects broader relative momentum rather than simply one-day performance.
Momentum Breakdown by Quadrant
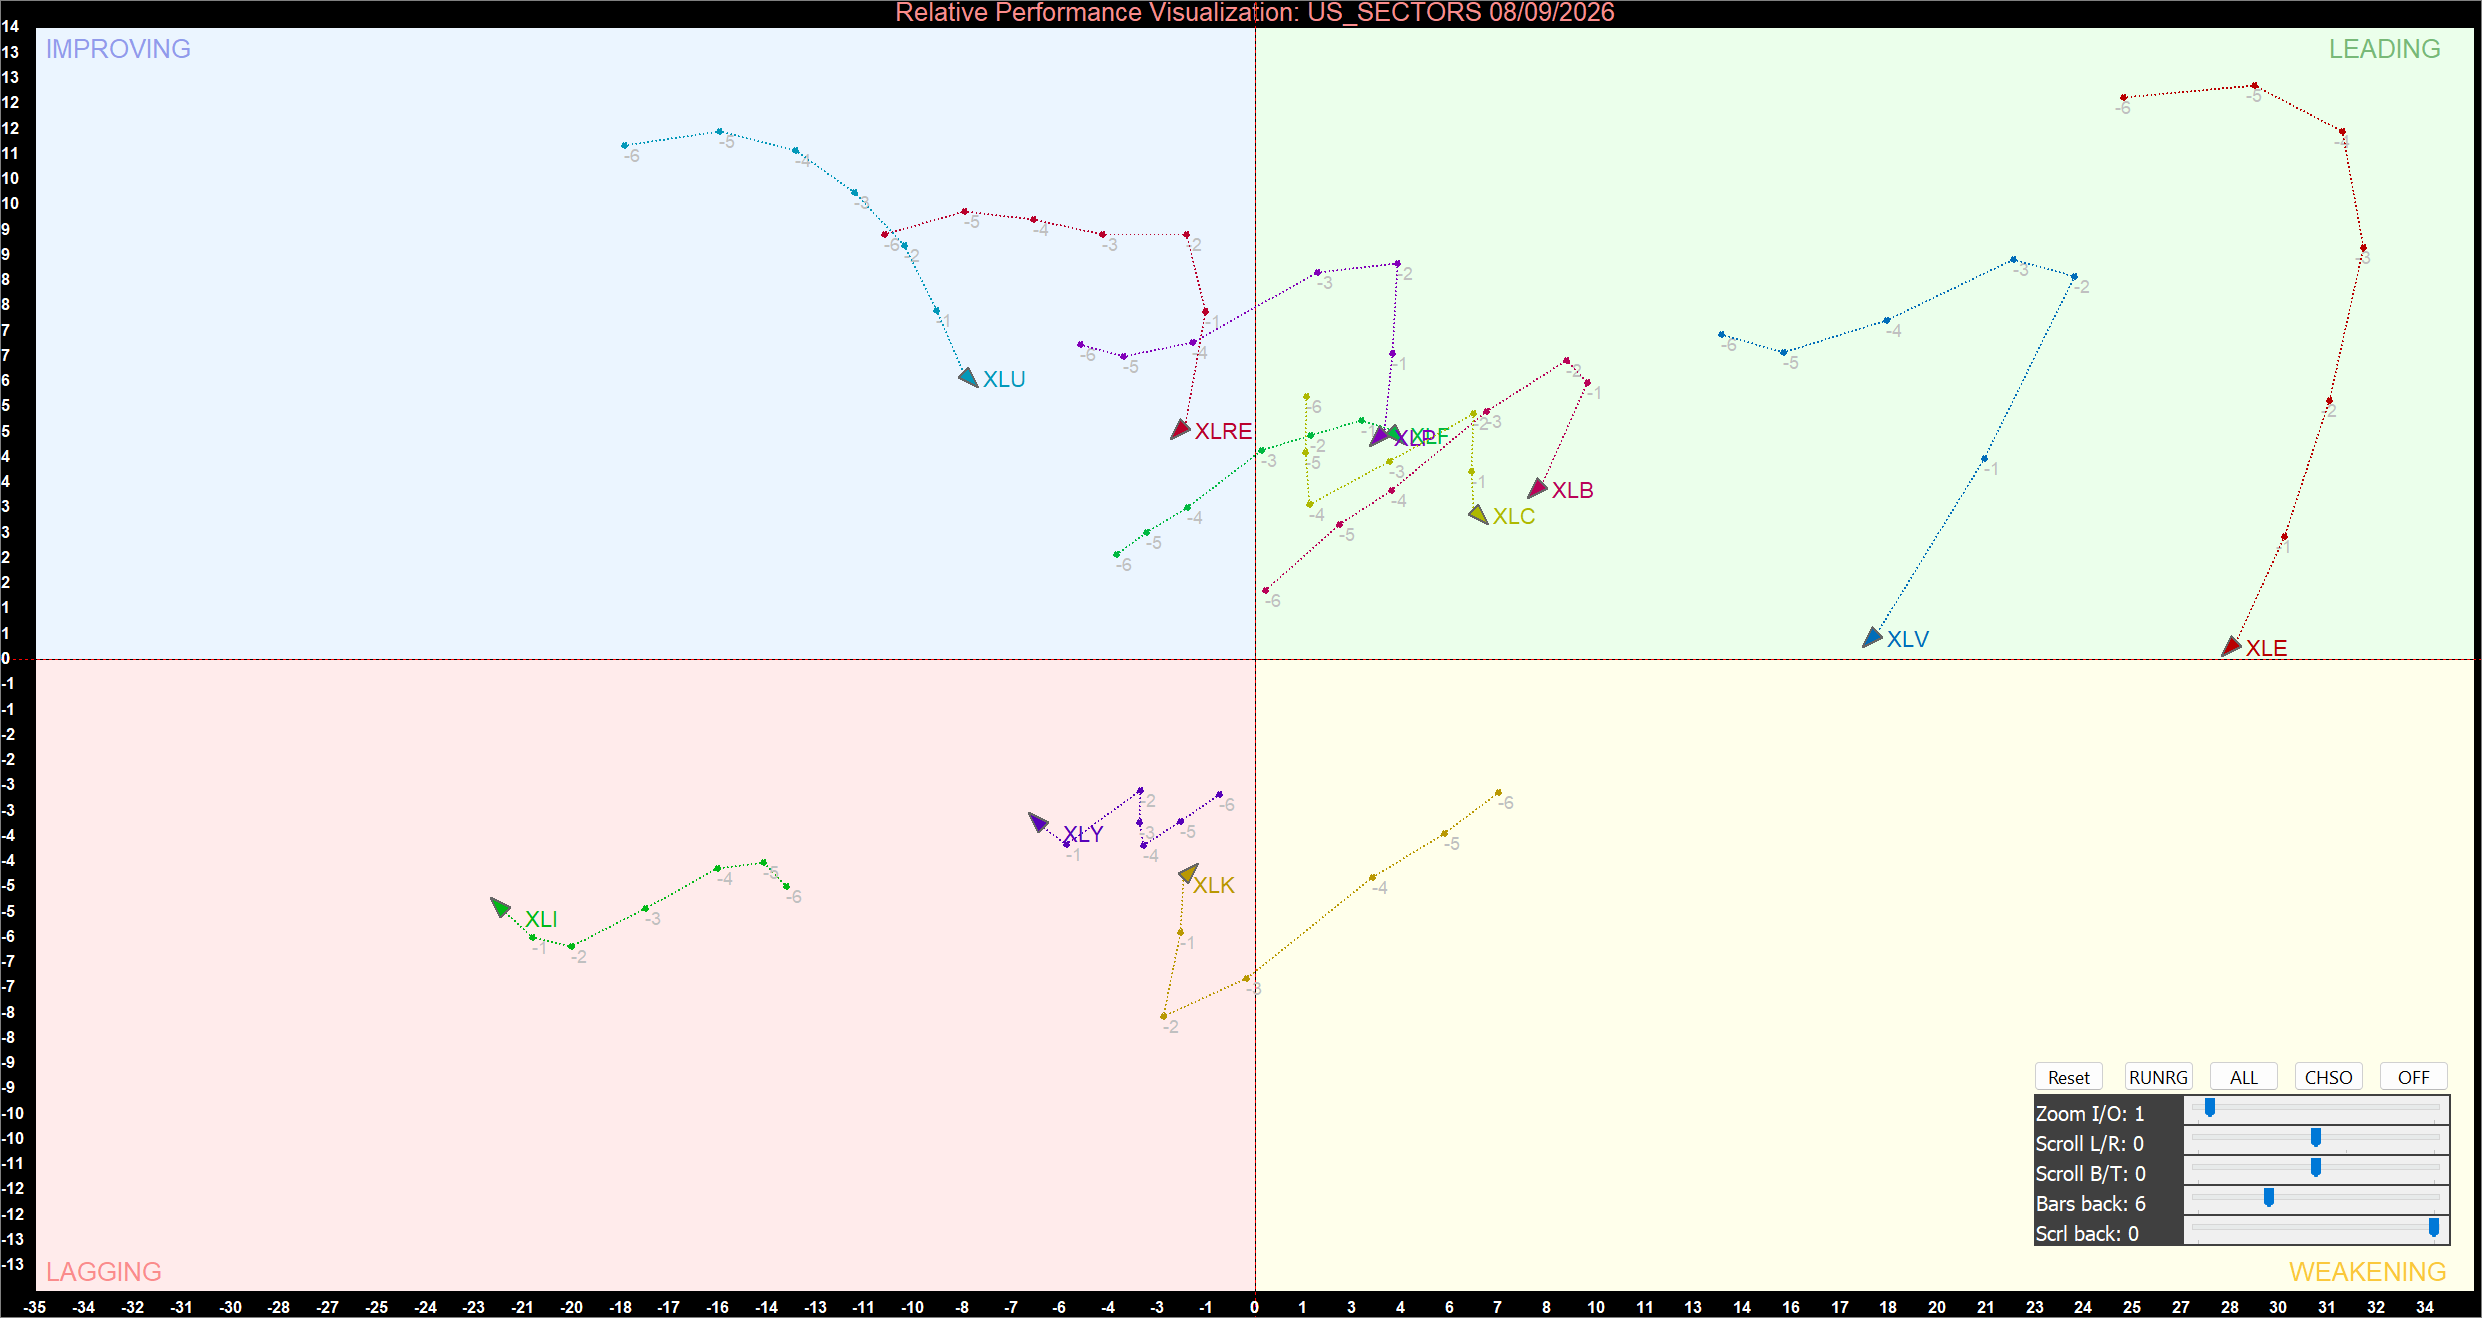
US Sector Relative Momentum Chart (at the closing price of 08/09/2026). Powered by AmiBroker.
Leading: Energy, Health Care, Materials, Communication Services, Financials and Consumer Staples
Energy (XLE) remains one of the strongest sectors from a relative-momentum perspective. The sector gained 1.11% on 8 September and remains positioned in the upper-right portion of the RRG, indicating continued positive relative strength and momentum.
Health Care (XLV) also remains in Leading despite falling 2.52%, the weakest daily performance among the sectors in the current dataset. Its continued position in the upper-right quadrant indicates that its broader relative momentum remains stronger than the market.
Materials (XLB) and Communication Services (XLC) remain in Leading despite declining 0.95% and 0.46%, respectively. Financials (XLF) also remains in Leading despite falling 1.38%, while Consumer Staples (XLP) declined 0.66% but retained its Leadership position.
The continued presence of six sectors in Leading indicates that established relative momentum remains concentrated across a broad group of sectors. However, their future RRG trajectories will be important in determining whether this leadership can be sustained.
Improving: Utilities and Real Estate
Utilities (XLU) gained 0.86%, while Real Estate (XLRE) declined marginally by 0.07%. Despite the difference in daily performance, both remain in the Improving quadrant.
Their positions indicate strengthening relative momentum without yet establishing the stronger relative-strength characteristics associated with Leading. Utilities is particularly notable following its positive daily performance.
Continued movement toward the upper-right would increase the probability of both sectors transitioning into Leading, while movement back toward the centre would suggest that their momentum recovery is losing strength.
Lagging: Technology, Industrials and Consumer Discretionary
Technology (XLK) gained 0.32% on 8 September but remains in Lagging. This demonstrates that a positive one-day return does not necessarily translate into an immediate improvement in relative momentum.
Industrials (XLI) declined 0.48% and Consumer Discretionary (XLY) fell 0.80%, with both sectors remaining in the lower-left quadrant. Their positions indicate weaker relative strength and subdued momentum compared with the broader market.
For these three sectors, sustained movement toward the centre of the RRG would provide the first indication that momentum is beginning to recover. A subsequent transition into Improving would provide stronger confirmation of a developing rotation.
Strategic Summary
The latest US sector momentum analysis shows six sectors in Leading, two in Improving and three in Lagging, creating a relatively constructive but selective rotational structure.
Energy, Health Care, Materials, Communication Services, Financials and Consumer Staples remain the established leaders. Their continued positions in the upper-right quadrant indicate stronger relative momentum despite several sectors recording negative daily returns.
Utilities and Real Estate remain the key sectors in Improving. Continued movement toward the upper-right would provide stronger confirmation of a potential transition into Leading.
Meanwhile, Technology, Industrials and Consumer Discretionary remain in Lagging. Technology's 0.32% gain is particularly notable because the sector has improved on the day without yet producing a corresponding improvement in its RRG classification.
Overall, the RRG presents a broadly constructive US sector environment, supported by six established leaders and no sectors in Weakening. The key developments to monitor are whether Utilities and Real Estate can transition into Leading and whether Technology, Industrials and Consumer Discretionary can rotate toward the centre of the RRG.


 Nov 12, 2026





 Please wait processing your request...