
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
- Universal Store Holdings is a growing Australian youth fashion retailer operating the Universal Store, Perfect Stranger and CTC businesses, with a strategy focused on premium, on-trend fashion and continued retail network expansion.
- H1 FY26 delivered strong operating momentum, with group sales increasing 14.2% to $209.6 million and underlying EBIT rising 23.2% to $43.6 million.
- Universal Store and Perfect Stranger continued to record positive like-for-like sales growth, while the group expanded its store network to 118 locations by December 2025.
- Technically, UNI has formed a potential Inverse Head & Shoulders pattern while approaching neckline resistance around $7.88 and simultaneously testing a descending Trendline .
- A decisive breakout above $7.88 would confirm the bullish Reversal pattern and could generate a medium-term measured-move target near $9.88.
Following several months of corrective price action, Universal Store Holdings Ltd (ASX: UNI) appears to be approaching an important technical inflection point. The stock has gradually developed a potential Inverse Head & Shoulders pattern after reaching a low near $6.10 in May 2026, while the recovery has brought price back towards the neckline around $7.88. At the same time, UNI is testing a descending trendline that has restricted the recovery since the March 2026 high. A convincing breakout above both resistance levels could signal the beginning of a new medium-term recovery phase.
The Retail Growth Story
Universal Store Holdings operates a portfolio of youth fashion retail businesses, with Universal Store as its core format alongside Perfect Stranger and the CTC brands. The company's strategy is focused on scaling premium fashion brands, expanding its retail formats and strengthening its customer experience. Its H1 FY26 results demonstrated continued sales and Earnings momentum.
- Strong Group Sales Growth: H1 FY26 group sales increased 14.2% year-on-year to $209.6 million. This reflected continued growth across the group's retail businesses and a long-term sales CAGR of 12.2% from H1 FY21 to H1 FY26.
- Improving Profitability: Underlying EBIT increased 23.2% to $43.6 million, while underlying NPAT rose 22.0% to $28.3 million. The underlying EBIT Margin improved to 20.8%, supported by stronger gross margins and sales growth.
- Strong Universal Store Performance: The core Universal Store Business generated $174.8 million of sales in H1 FY26, up 11.9%, with like-for-like sales growth of 8.7%. The company also continued expanding its store network, reaching 87 Universal Store locations.
- Rapid Perfect Stranger Growth: Perfect Stranger sales increased 41.5% to $17.8 million, while like-for-like sales rose 14.8%. The network expanded to 22 stores, highlighting the format's growing contribution to the group.
- Strong Balance Sheet : At the end of H1 FY26, Universal Store Holdings reported $38.4 million of cash and nil borrowings excluding Lease liabilities. The company also paid a fully franked Interim Dividend of 26.0 cents per share.
Associated Risks
While the technical structure has improved, several risks remain.
The potential Inverse Head & Shoulders pattern remains unconfirmed, meaning UNI must deliver a decisive breakout above the neckline and descending trendline resistance around $7.88 before the bullish scenario can be validated. Failure to overcome this resistance could result in another period of consolidation or a pullback towards the right shoulder and the lower support area around $7.00–$7.30.
In addition, Universal Store's performance remains sensitive to consumer spending, discretionary retail conditions, employment trends and household confidence. Weakening consumer Demand or increased promotional activity across the fashion retail sector could place pressure on sales growth and gross margins.
The company is also continuing to invest in its store network, team capability and technology. H1 FY26 cost of doing business increased as the group invested in personnel and systems, while a new point-of-sale implementation was scheduled to commence in Q4 FY26. These investments are intended to support future growth but could increase operating costs if sales growth moderates.
Furthermore, the CTC business remains exposed to wholesale-market Volatility . Management noted that CTC wholesale sales declined during H1 FY26 partly because of a planned reduction in exports to the United States following tariff-related conditions.
Technical Outlook
UNI's Daily Chart is approaching an important technical inflection point as a potential Inverse Head & Shoulders pattern moves towards confirmation.
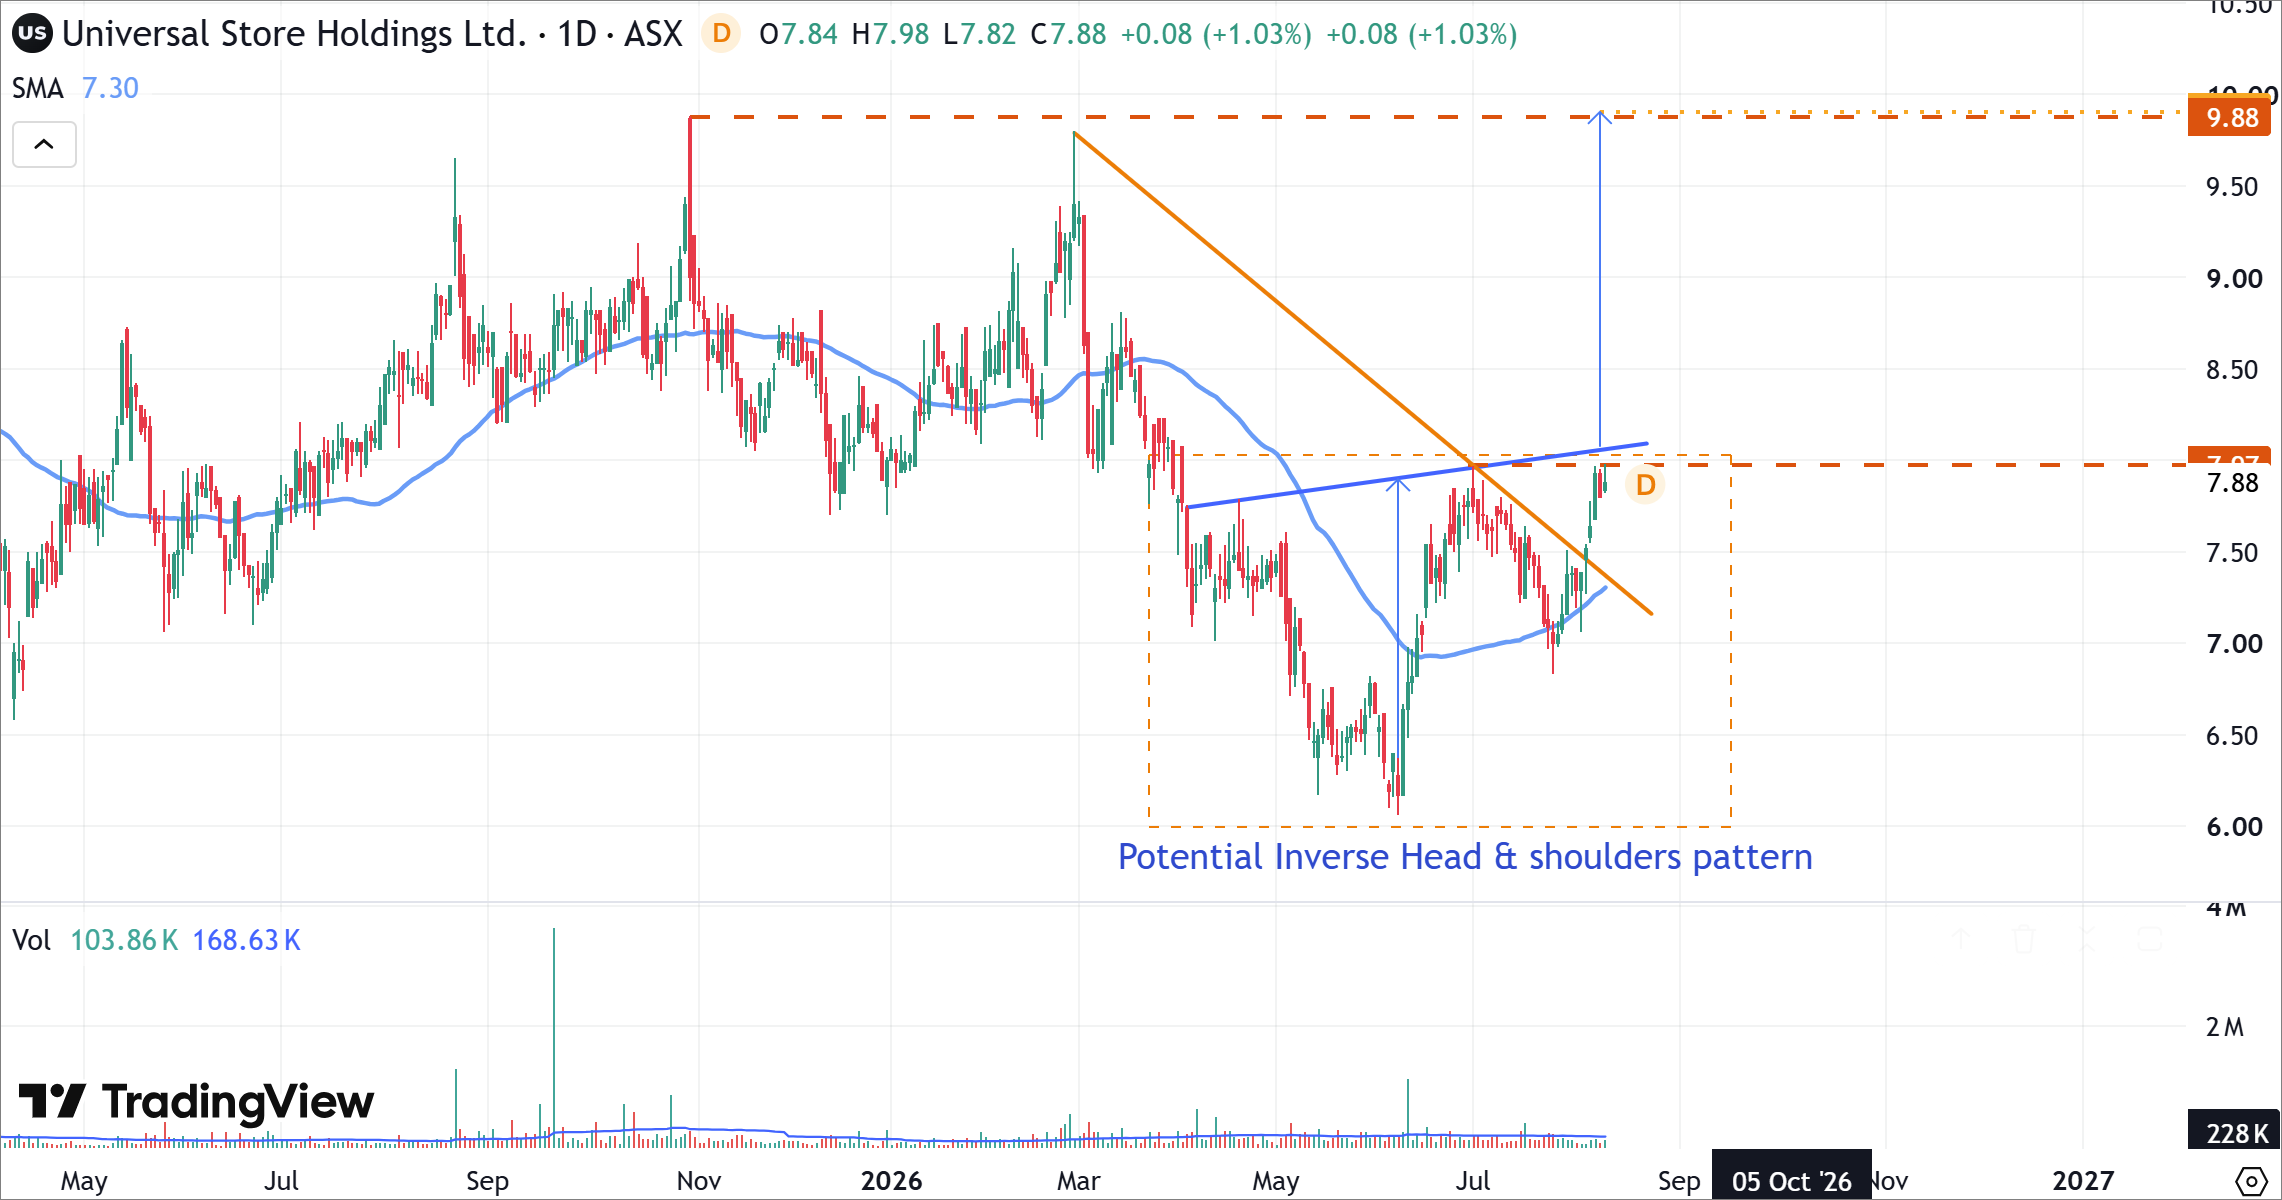
UNI's Daily Price Chart (at the closing price of 10/08/2026). Powered by: tradingview.com.
- UNI has developed a potential Inverse Head & Shoulders pattern following the significant decline from its March 2026 high. This structure suggests that bearish momentum has weakened and buyers have gradually regained control.
- The neckline of the potential pattern is positioned around $8.07. A sustained close above $8.07 would confirm the Inverse Head & Shoulders pattern and substantially strengthen the bullish technical outlook.
- The neckline coincides closely with the descending trendline extending from the March 2026 peak. This creates a particularly important technical resistance zone. A breakout above both the horizontal neckline and descending trendline would represent a dual technical breakout and could signal a transition from the previous downtrend into a medium-term recovery.
- Applying the traditional measured-move projection from the potential Inverse Head & Shoulders pattern produces an upside objective of approximately $9.88, as shown on the chart.
Universal Store Holdings Ltd (ASX: UNI) appears to be approaching a significant technical turning point after recovering strongly from its May 2026 low. The development of a potential Inverse Head & Shoulders pattern, combined with price testing the neckline and a major descending trendline, suggests that the prolonged correction may be nearing completion.
The company's improving operating performance provides a supportive fundamental backdrop, with H1 FY26 sales rising 14.2%, underlying EBIT increasing 23.2%, and continued strong growth from both Universal Store and Perfect Stranger.
A decisive breakout above $8.07 would confirm the bullish reversal and initially open the way towards the measured target near $9.88. Until then, the $8.07 neckline and descending trendline remain the most important technical levels to monitor. A successful breakout would substantially strengthen UNI's medium-term recovery outlook, while failure to overcome resistance could result in further consolidation or a retest of the $7.30 support area.


 Nov 12, 2026





 Please wait processing your request...