
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Company Overview
Smartgroup Corporation Ltd is Australia's leading provider of salary packaging and novated leasing services, primarily serving employees of public sector organisations including hospitals, universities, not-for-profits, and government departments. The company administers salary packaging benefits on behalf of employers and their staff, enabling employees to reduce their Taxable Income by packaging eligible expenses including vehicles, living expenses, and Superannuation through pre-tax salary arrangements.
The Australian salary packaging sector is characterised by high regulatory barriers to entry, deep integration with employer HR systems, and strong customer retention driven by switching costs and multi-year contracts. Smartgroup has achieved market-leading positions through a combination of organic growth, strategic acquisitions, and technology Investment in its digital administration platforms.
The electric vehicle salary packaging incentive introduced by the Australian government has been a material positive catalyst for Smartgroup's novated leasing Business, with Demand for EV novated leases significantly exceeding conventional vehicle leases in recent periods. This structural tailwind from government EV policy is expected to drive accelerating growth in the novated leasing book. Seven analysts cover the stock, reflecting its institutional quality and Earnings predictability.
Fundamental Insights
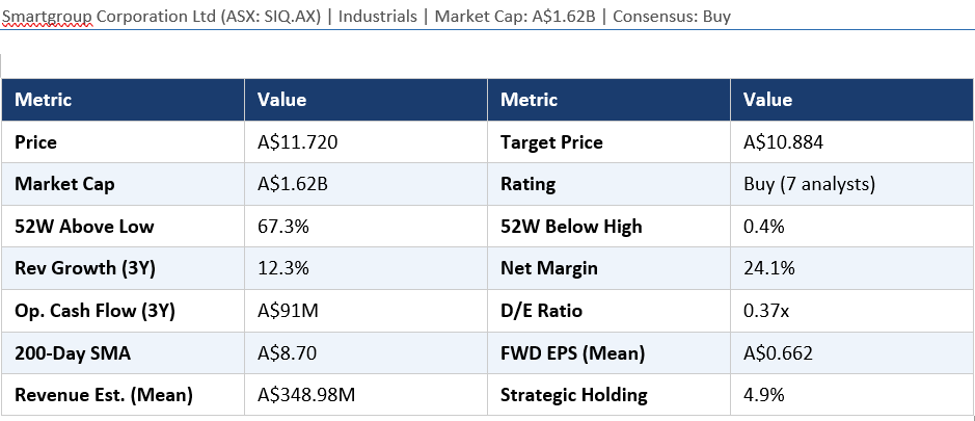
Smartgroup's financial metrics confirm a high-quality, Recurring Revenue business. Revenue has grown at 12.3% per annum over three years — consistent, sustainable growth driven by salary packaging Volume growth and EV novated Lease momentum. Net profit Margin of 24.1% is exceptional for a financial services and technology platform, demonstrating the Operating Leverage of the digital administration model.
Operating Cash Flow of A$91 million over three years is strong relative to the A$1.62 billion Market Capitalisation, providing a cash flow Yield in the high single digits. Debt-to-Equity of 0.37x is appropriate for a financial services business with defined-term lease books. The 200-day SMA at A$8.70 versus the current price of A$11.72 confirms a powerful re-rating has occurred over the medium term.
Seven analysts provide tight EPS estimates of A$0.649-A$0.690, reflecting high earnings visibility and predictability. Revenue consensus of A$348.98 million is the mean. At the current price of A$11.72, the forward P/E on mean EPS of A$0.662 is approximately 17.7x — a fair multiple for a market-leading financial services platform with recurring revenue and EV growth optionality.
Broker Views and Analyst Consensus
Seven analysts cover Smartgroup with 1 Strong Buy, 4 Buy, and 2 Hold ratings — a broadly positive consensus. The consensus target of A$10.884 sits below the current price of A$11.72, with the market having traded ahead of analyst models. This is a common scenario for quality businesses where momentum and strategic news flow carry the price above fundamental targets temporarily.
The bull case centres on Smartgroup's market leadership in the salary packaging sector, the EV novated leasing tailwind, high earnings predictability, and the technology platform creating barriers to entry. The 2 Hold ratings reflect the premium valuation and the fact that the stock is trading above broker targets.
Key risks include changes to the FBT (Fringe Benefits Tax) exemption regime that underpins salary packaging Economics, competitive pressure from emerging digital salary packaging providers, and customer concentration in government and health sectors.
Technical Analysis
Smartgroup is at a remarkable point technically — sitting at 67.3% above its 52-week low and only 0.4% below its 52-week high. This near-52-week-high positioning indicates the stock is in strong bullish momentum and trading at the apex of its annual range. The 200-day SMA at A$8.70 is dramatically below current levels, confirming the exceptional strength of the re-rating.
The technical picture is bullish momentum approaching resistance at the all-time high. A new 52-week high break on volume would be a strong signal of continued appreciation. Support sits at A$11.00 and A$10.50. RSI is likely elevated given the proximity to the 52-week high, but momentum-driven quality stocks can sustain elevated RSI during fundamental uptrends. The broker consensus target below current price is a potential moderator of further upside.
Investor Insights
Smartgroup is a quality institutional compounder approaching its all-time high range. Despite trading above broker consensus targets, the business quality — 24.1% net margin, A$91 million operating cash flow, near-Monopoly market position — justifies a hold for existing investors and a selective buy on any pullback toward A$11.00. The EV novated lease tailwind is a multi-year structural driver that analyst models may underestimate if adoption accelerates faster than expected. For new investors, a 5% pullback from current levels would improve the risk-reward position.


 Nov 12, 2026





 Please wait processing your request...