
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Company Overview
Servcorp Ltd is a global provider of premium serviced offices, virtual offices, and coworking spaces, with operations across Asia-Pacific, the Middle East, the Americas, and Europe. The company occupies premium floors in landmark buildings in major financial centres and sublets these spaces to businesses seeking flexible, high-prestige office solutions. Servcorp's model is asset-light relative to traditional office property - the company leases space rather than owns it, adding value through technology, reception, and administrative services. The Business has benefited from the structural shift toward hybrid and flexible work arrangements post-COVID, with Demand for premium flex office solutions rebounding strongly.
Fundamental Insights
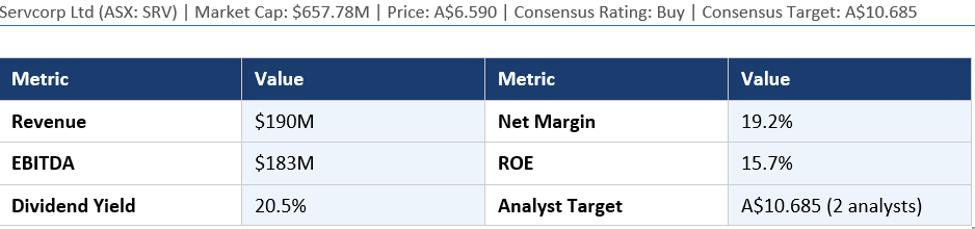
Servcorp's Revenue of $190 million grew 8.2% year-on-year, while EBITDA reached $183 million, a 15% annual increase reflecting strong Operating Leverage. Net Margin of 19.2% is healthy and EBITDA-to-revenue metrics are exceptional, suggesting very high recurring fee income relative to stated revenue. ROE of 15.7% is solid for a services business. The 20.5% Dividend Yield is one of the most attractive in this peer group, reflecting Servcorp's Capital-light model and strong cash generation. Revenue growth of 12.8% adjusted confirms solid organic expansion. The modest EBITDA margin of 5.8% on a reported basis may reflect leasehold accounting treatments under IFRS 16.
Broker Views and Analyst Consensus
Despite only two analysts providing formal coverage, both maintain a Buy rating with an aggressive consensus target of $10.685 - implying upside of 62% from the current price of $6.59. This is one of the widest analyst-to-price gaps in the peer group, suggesting Servcorp may be significantly undervalued or is under-covered by the market. The bullish case centres on global occupancy recovery, pricing power in premium markets, and the dividend yield that dwarfs peers. The limited analyst coverage itself creates an information inefficiency that sophisticated investors may exploit.
Technical Analysis
Servcorp at $6.59 has already staged a strong 50.9% price recovery from its lows. Technically, the stock is consolidating below the $7.00 resistance level. A close above $7.00 on strong Volume would be a meaningful bullish signal targeting the $8.50-$9.00 zone in the near term, with broker targets of $10.69 representing the longer-term aspiration. Support is solid at $6.00-$6.20. RSI is moderate, suggesting the stock has more room to run. The wide analyst-to-price gap of 62% is a rare opportunity in established ASX names.
Investor Action Points
A 62% potential return to target, combined with a 20.5% dividend yield, creates a healthy total return case. The key risk is thin analyst coverage, which can mean less information flow and larger price swings on news. Investors should conduct proprietary research into Servcorp's occupancy rates and contract renewals before sizing up. A starting position now with a plan to add on any pullback toward $6.00-$6.20 is a prudent approach.
Disclaimer: This article is for informational purposes only and does not constitute financial advice. Investors should conduct their own Due Diligence and consult a licensed financial adviser before making Investment decisions. Past performance is not indicative of future results.


 Nov 12, 2026





 Please wait processing your request...