
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
- Sandfire Resources is a global copper producer with operations including MATSA in Spain and Motheo in Botswana, while continuing to advance its growth pipeline.
- FY26 group copper-equivalent production reached 154.2kt, with Q4 production increasing 38% quarter-on-quarter to 47.6kt.
- Q4 FY26 delivered record sales Revenue of $574 million and underlying EBITDA of $343 million, while net cash increased to $353 million at 30 June 2026.
- FY27 group copper-equivalent production guidance is 150,000–166,000 tonnes, with management expecting a more even production profile across the year.
- Technically, SFR has now broken above the neckline of a potential Inverse Head & Shoulders pattern following an extended period of consolidation.
- The share price closed at $22.44 on the updated chart, above the previous resistance and neckline around $21.75.
- The confirmed breakout strengthens the bullish technical outlook and points towards the chart-based measured-move target of approximately $28.43.
Sandfire Resources Limited (ASX: SFR) has reached an important technical inflection point after several months of consolidation. The Daily Chart now shows a confirmed breakout above the neckline of an Inverse Head & Shoulders pattern, with the share price closing at $22.44 and moving decisively above the previous resistance around $21.75. The breakout strengthens the potential for a new medium-term recovery phase.
The Copper Growth Story
Sandfire has strengthened its position as a global copper producer through its MATSA operations in Spain and Motheo operation in Botswana. The company's latest operating performance provided a strong finish to FY26, with group copper-equivalent production reaching 154.2kt. Q4 production increased 38% to 47.6kt, supported by improved performance from both major operating assets.
- Record Q4 Production: Group copper-equivalent production increased 38% quarter-on-quarter to 47.6kt in Q4 FY26, contributing to annual production of 154.2kt.
- Motheo Improvement: Motheo's quarterly copper-equivalent production increased 65%, supported by the higher-grade A4 open pit and record mill throughput of approximately 7.1Mtpa.
- MATSA Performance: MATSA delivered annual copper-equivalent production of 94.5kt, with record annualised processing rates supporting stronger output.
- Strong Financial Performance: Q4 sales revenue reached a record $574 million, while underlying EBITDA was $343 million, representing a 60% margin.
- Stronger Balance Sheet: Sandfire ended FY26 with $353 million in net cash, a substantial improvement from its net Debt position a year earlier.
- FY27 Production Outlook: Management has guided to 150,000–166,000 tonnes of copper equivalent production for FY27 and expects a more even production profile across the year.
- Growth Pipeline: Sandfire is progressing the Kalkaroo Copper-Gold Project in South Australia, with drilling underway to support a pre-feasibility study targeted for the second half of FY28.
The combination of strong operating performance, improving balance-sheet strength and a substantial copper production base provides a supportive fundamental backdrop. However, Sandfire remains exposed to commodity-price movements, operating costs and the execution of its development pipeline.
Associated Risks
The technical outlook has strengthened following the breakout, but confirmation of the bullish scenario will depend on SFR sustaining its position above the former neckline around $21.75. A failure to hold above this level could result in a false breakout and renewed consolidation.
The rising long-term Trendline remains an important underlying support reference. Based on the updated chart, this trendline is currently positioned around the $17.50–$18.00 area. A deeper decline toward this zone would weaken the current bullish structure. The lower part of the previous consolidation around $14.00–$15.00 remains a more significant structural support area.
Sandfire also remains exposed to fluctuations in copper and other Commodity prices. A sustained decline in copper prices could affect realised revenue, margins and cash generation. At the same time, higher energy, labour and Mining costs could put pressure on operating margins.
Operational execution is another important consideration. Sandfire's FY27 outlook includes planned shutdowns at Motheo, while the company is increasing Capital Investment in areas such as the T3 open-pit cutback, the MATSA tailings Facility and exploration and development activities. Delays, cost increases or weaker-than-expected production could affect the company's growth trajectory.
Technical Outlook
SFR's daily chart has now broken above the neckline of the Inverse Head & Shoulders pattern, strengthening the bullish technical outlook and opening the potential for further upside.
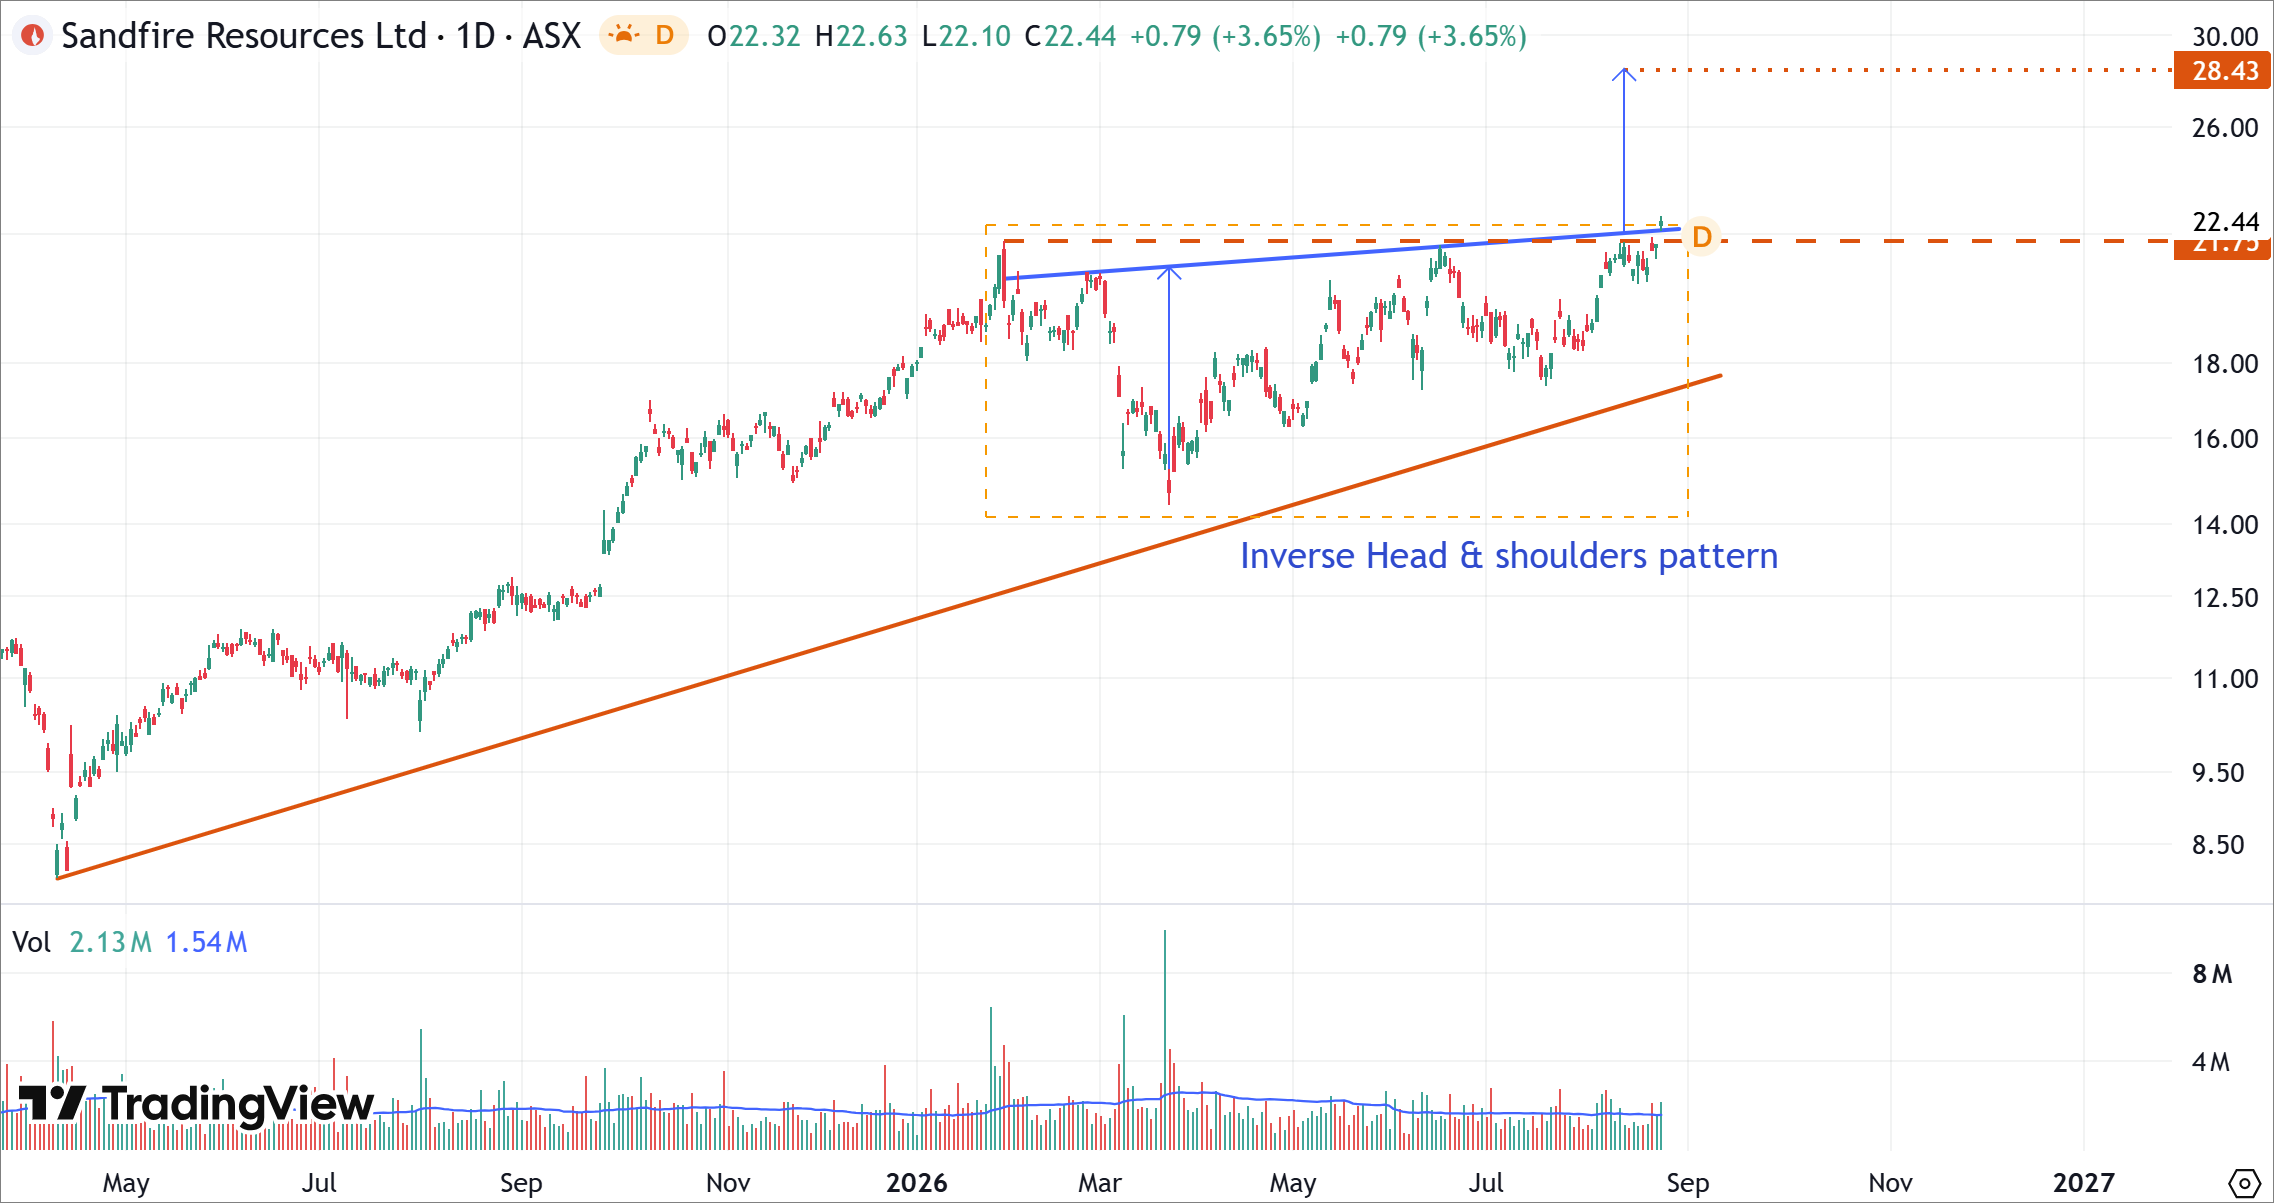
NWH's Daily Price Chart (at the closing price of 24/08/2026). Powered by: tradingview.com.
- SFR has completed a significant technical breakout after moving above the neckline at $21.75. The share price subsequently reached an intraday high of $22.63 and closed at $22.44 on the updated chart.
- The breakout follows several months of consolidation during 2026 and completes the bullish Reversal structure identified in the previous analysis.
- The rising orange trendline from the earlier 2025 low continues to provide underlying support, helping maintain the broader bullish structure.
- The previous neckline around $21.75 now becomes an important potential support level. A successful retest and hold above this area would strengthen the breakout signal.
- The measured-move projection shown on the chart points towards approximately $28.43.
- From the $21.75 neckline, the $28.43 target represents potential upside of approximately 30.7%.
- The latest move above resistance is accompanied by increased price momentum, although continued trading Volume would provide additional confirmation of the breakout.
Bottom Line
Sandfire's strong FY26 operating performance, record Q4 revenue, improved net cash position and FY27 production guidance of 150,000–166,000 tonnes of copper equivalent provide a supportive fundamental backdrop. The company's improving Motheo performance, solid MATSA contribution and continued investment in growth projects further support its longer-term copper production strategy.
Technically, SFR has moved beyond the key $21.75 neckline of the Inverse Head & Shoulders pattern, confirming a bullish breakout. With the share price closing at $22.44, the pattern's measured-move projection points towards approximately $28.43, representing potential upside of around 30.7% from the neckline.
The key level to monitor is now the former $21.75 resistance, which could act as support during any subsequent pullback. Sustained trading above this level would keep the bullish breakout structure intact, while a decisive move back below it could raise the risk of a failed breakout.


 Nov 12, 2026





 Please wait processing your request...