
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Company Overview
Resolute Mining Ltd is a veteran Australian gold mining company with operations in West Africa, specifically the Syama Gold Mine in Mali and the Mako Gold Mine in Senegal. The company has decades of experience in African gold mining and has built operational expertise in managing complex logistics, community relations, and regulatory environments across multiple African jurisdictions.
Syama is one of the largest gold mines in West Africa by resource base, featuring a large sulphide ore body processed through a roaster circuit as well as an oxide ore body processed through a conventional carbon-in-leach plant. Mako in Senegal is a lower-complexity open-cut operation delivering consistent production at strong margins. The combination of these two Assets provides production Diversification within the African gold sector.
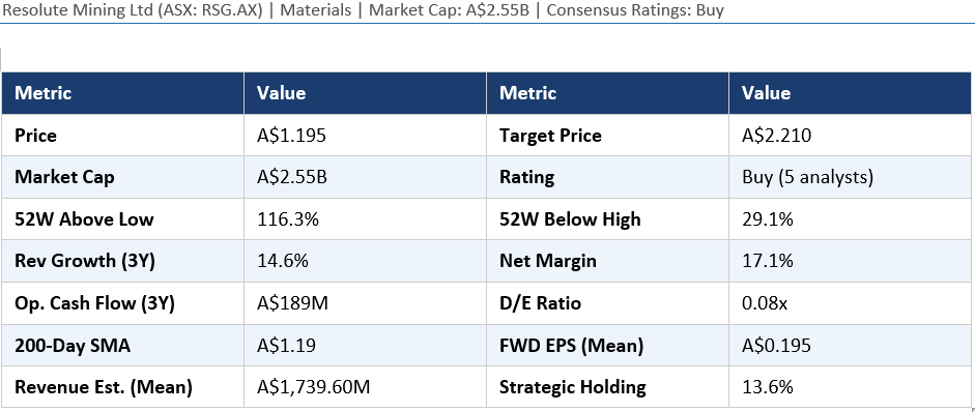
At current elevated gold prices, Resolute's operations generate substantial Cash Flow, and the company has been deploying Capital into extending mine life at both operations through exploration and infill drilling. The 29.1% pullback from its 52-week high and the 85% upside implied by the consensus analyst target suggest significant fundamental undervaluation at current prices, likely reflecting geopolitical risk discounts applied to Mali and Senegal operations.
Fundamental Insights
Resolute Mining's financials reflect a large, established gold producer. Revenue growth of 14.6% over three years is modest in percentage terms but meaningful in absolute dollar value given the company's A$1.74 billion projected revenue base. Net profit Margin of 17.1% confirms profitable operations across both the Syama and Mako mines at current gold prices.
Operating Cash Flow of A$189 million over three years is a strong indicator of cash generation quality, particularly given the scale of the operations and the capital requirements of maintaining and expanding underground and open-cut gold mines. Debt-to-Equity of 0.08x is exceptionally low for a large-scale mining company, confirming conservative financial management and strong cash flow conversion.
Five analysts provide a range of EPS estimates from A$0.153 to A$0.219, with a mean of A$0.195. At the current price of A$1.195, the implied forward P/E is approximately 6.1x — extraordinarily low for a profitable, multi-asset gold producer at historically high gold prices. This valuation anomaly is the central thesis for the analyst community's Buy consensus.
Broker Views and Analyst Consensus
Five analysts cover Resolute Mining and all five carry Buy ratings — a complete sweep that is one of the strongest analyst consensus signals in this peer group. The consensus target of A$2.21 implies 85% upside from the current A$1.195, an exceptional potential return that reflects the magnitude of the valuation gap between current price and fundamental value.
The broker thesis is straightforward: Resolute's assets are high-quality, cash-generative gold operations at a gold price environment that is generating exceptional margins. The 6x forward P/E is materially below gold sector peers trading at 15-20x, and the gap is attributable almost entirely to geopolitical risk premiums on Mali and Senegal operations.
Brokers argue that the geopolitical discount is excessive relative to actual operational risk, as Syama and Mako have continued to produce consistently despite political changes in both countries. Key risks are sovereign/geopolitical risk in Mali and Senegal, gold price sensitivity, and operational complexity at the Syama roaster which requires technical expertise to maintain.
Technical Analysis
Resolute sits 116.3% above its 52-week low but 29.1% below its 52-week high — one of the larger pullbacks from peak among peers in this analysis. The stock's 200-day SMA at A$1.19 is essentially equal to the current price of A$1.195, meaning the stock is sitting right at this critical technical level. A sustained hold above A$1.19 is essential for the bullish thesis; a break below would signal technical deterioration toward A$1.05.
The 85% upside to broker target is too large to achieve without fundamental catalysts — news flow around production results, Senegal and Mali government relations, and gold price direction will all be significant drivers. Support at A$1.10-A$1.15 and resistance at A$1.50 (prior consolidation zone) are the near-term technical parameters to monitor.
Investor Insights
Resolute is a high-upside, geopolitical-Risk-adjusted gold Investment. For investors comfortable with West African mining Jurisdiction risk, the current valuation of 6x forward P/E against a 85% upside target and analyst Buy ratings is a healthy proposition. The A$1.19 SMA support provides a natural entry and stop-loss reference level.


 Nov 12, 2026





 Please wait processing your request...