
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Company Overview
Regal Partners Ltd is an Australian alternative asset manager specialising in Hedge Funds, private Credit, and long-short equity strategies. Listed on the ASX, the company manages money for institutional and high-net-worth investors, deploying Capital across global markets with a performance-fee-driven Business model. Regal has grown rapidly through a combination of organic inflows and strategic acquisitions, most notably the Merger with PM Capital's listed vehicle and integration of several boutique managers. The business benefits from a scalable fee structure where performance fees act as a high-Margin Earnings Kicker on top of steady management fee income.
Fundamental Insights
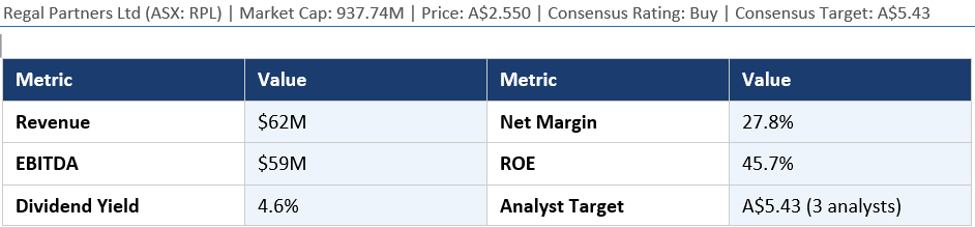
Regal Partners delivers standout Economics rarely seen in small-cap financials. Net margin of 27.8% and Return on Equity of 45.7% reflect the capital-light, high-margin nature of the fund management model. Revenue has grown 31.1% year-on-year to $62 million, driven by rising funds under management and strong performance fees. EBITDA of $59 million represents a 9.2% annual uplift, and the EBITDA margin of 23.4% reflects ongoing Investment in distribution and headcount to support growth ambitions. A Dividend Yield of 4.6% adds an income dimension to an otherwise growth-oriented profile, making the stock appealing across investor styles. The gross margin of 35.7% underscores the Operating Leverage inherent in the model as AUM grows.
Broker Views and Analyst Consensus
With a consensus Buy rating from 3 covering analysts and a target price of $5.43, Regal Partners offers a potential upside of over 113% from its current price of $2.55. Brokers highlight the company's ability to compound AUM growth, a diversified strategy mix that reduces single-fund risk, and the alignment of management interests through co-investment. The stock's 817.1% historical price appreciation has attracted momentum-focused coverage, and analysts are increasingly constructive on the private credit ramp as an incremental FUM driver. Key risks flagged by brokers include performance fee Volatility in bear markets and key-man dependency on portfolio managers.
Technical Analysis
At $2.55, RPL is trading well below its consensus target of $5.43, suggesting material fundamental undervaluation by the market. The stock has been in a consolidation phase following its extraordinary historical run. Key support sits around the $2.20-$2.40 zone, while a sustained move above $2.80 would signal re-rating momentum. RSI levels are neutral, leaving room for a meaningful upside push before the stock reaches overbought territory. Volume patterns suggest accumulation by longer-term holders rather than speculative chasing.
Investor Action Points
Regal Partners is a growth story with income characteristics. Investors with a 12–18-month horizon should consider near current levels, given the wide gap between current price and consensus target. A stop-loss below $2.20 would define downside risk. Given the 4.6% dividend yield, the total return case is compelling even under conservative assumptions.
Disclaimer: This article is for informational purposes only and does not constitute financial advice. Investors should conduct their own Due Diligence and consult a licensed financial adviser before making investment decisions. Past performance is not indicative of future results.


 Nov 12, 2026





 Please wait processing your request...