
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key highlights
- PEXA has demonstrated a significant financial turnaround in the first half of FY2026
- The company achieved a 10% increase in Group revenue to $215.3 million for the first half of FY26.
- The group returned to statutory profitability, with an NPAT of $15.4 million from continuing operations.
- Strategic cost management led to a significant EBITDA margin expansion to 39.9%.
Although H1 FY26 results indicate a fundamental turnaround, the question remains: can this momentum be sustained? We will evaluate this transition from a technical perspective.
Strong H1 FY26 Financial Turnaround
- PEXA Group Limited (ASX: PXA) has demonstrated a significant financial turnaround in the first half of FY2026, driven by record settlement volumes in Australia and a strategic pivot toward its core operations.
- The company reported a 10% increase in revenue to $215.3 million and a return to statutory profitability with an NPAT of $15.4 million, compared to a loss in the previous year. A key pillar of its growth is the expansion into the UK market, where it has recently onboarded Tier 1 lender NatWest and seen a 24% rise in remortgage volumes.
- While PEXA recently trimmed its full-year revenue guidance to $395-$415 million due to expected seasonal softening, it upgraded its EBITDA margin guidance to 34-37%, reflecting disciplined cost management and the successful exit from its non-core Digital Solutions segment.
Associated Risks
- A primary concern is the potential for seasonal softening in the Australian property market, which recently led the company to trim its full-year revenue guidance to a range of $395–$415 million.
- Additionally, while the expansion into the UK market offers significant growth potential, the successful and timely implementation of the NatWest program remains a critical execution risk.
- Finally, the group’s decision to divest its Digital Solutions businesses introduces short-term transition risks as it narrows its focus exclusively on the core exchange platform.
Technical Outlook
PEXA Group Limited (ASX: PXA)
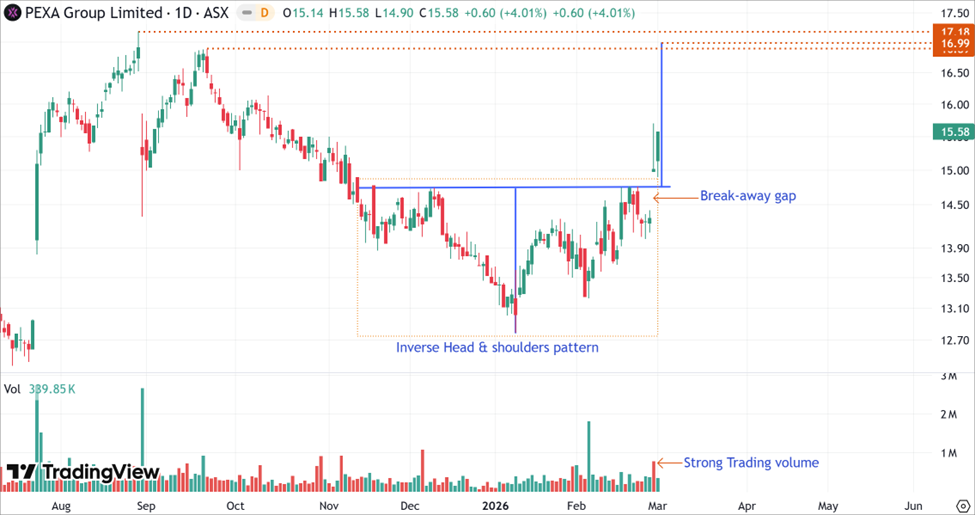
PXA’s Daily Price Chart (at the closing price of 27th February 2026). Powered by: tradingview.com
- On the daily chart, PXA’s stock price broke above the neckline of an Inverse Head and Shoulders pattern, coupled with a breakaway gap and strong trading volume; this indicates a strong positive signal of a short-term trend reversal from downward to upward.
- The pattern’s projected target is placed at $16.99, which can be viewed as the short-term price target. As this target is situated near a significant resistance zone established by previous peaks, strong selling pressure is expected to emerge around this level.
Bottom Line
- PEXA Group Limited has established a robust foundation for a recovery, though its sustainable success depends on navigating near-term market headwinds. The company’s decisive return to statutory profitability and significant EBITDA margin expansion in H1 FY26 provide a strong fundamental catalyst for the current technical breakout.
- While the daily chart signals a bullish trend reversal with a projected short-term target of $16.99, investors should remain mindful of the $395–$415 million revised revenue guidance and the selling pressure likely to emerge at historical resistance levels. Ultimately, PEXA’s momentum will be defined by its ability to execute its UK expansion and manage seasonal softening in the Australian property market.


 Nov 12, 2026





 Please wait processing your request...