
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
- NIB Holdings is experiencing renewed institutional interest as it leverages approved premium rate increases to offset broader medical claims inflation and repair its underwriting margins.
- As the broader market seeks out defensive, cash-generative legacy assets in the face of macroeconomic uncertainty, institutional capital appears to be actively rotating back into the battered private health insurer.
- The technical price action is exceptionally bullish, characterized by a forceful +3.79% daily advance on elevated volume that has decisively shattered the neckline of a pristine localized Inverse Head & Shoulders base.
While NIB Holdings Limited (ASX:NHF) spent the vast majority of the past year navigating a brutal, highly volatile cyclical downtrend driven by fears of rising hospital claims and policyholder lapse rates, the technical landscape has just undergone a definitive structural reversal. As the broader market frantically re-evaluates the margin-expansion potential of insurers operating in a hardened premium cycle, NHF appears to have successfully carved out a massive localized bottoming structure. The recent explosion in buying pressure suggests that the grueling distribution and capitulation phase has thoroughly exhausted, paving the way for a dynamic new cyclical mark-up phase.
Margin Recovery and Defensive Appeal
NHF’s fundamental investment thesis is heavily anchored to its pricing power and its defensive characteristics during periods of economic contraction:
- The Premium Cycle: NHF's core value proposition relies on successfully navigating the regulatory environment to secure annual premium rate increases. By passing these increases on to its policyholders, the company is actively working to repair underwriting margins that were previously compressed by inflation in specialized medical and hospital care costs.
- Investment Yield Tailwinds: As a major insurer, NHF holds a substantial investment portfolio backing its technical claims reserves. The sustained "higher-for-longer" interest rate environment provides a significant boost to the running yield on its fixed-income assets, creating a powerful secondary engine for earnings growth.
- Deep-Value Repricing: Having aggressively priced in the worst of the claims inflation headwinds over the past cycle, active value investors appear to be stepping in. They are capitalizing on a heavily discounted valuation multiple before the full extent of the margin recovery materializes in the upcoming earnings cycles.
Associated Risks
A primary risk for NIB Holdings remains the intense cost-of-living pressure facing Australian households. If household budgets tighten further, the company faces the risk of elevated policyholder lapse rates as consumers downgrade their coverage or abandon private health insurance entirely. Furthermore, NHF is highly sensitive to regulatory stroke-of-the-pen risk; any government intervention to cap future premium increases below the rate of medical inflation would severely compress the company's net margins. Finally, unexpected spikes in specialized hospital admissions or elective surgeries could rapidly deplete its claims allowances and impact bottom-line profitability.
Technical Outlook
The daily chart for NIB Holdings provides a textbook masterclass in structural exhaustion and breakout mechanics, highlighting a sudden, violent transition from a prolonged distribution phase into a fresh momentum phase.
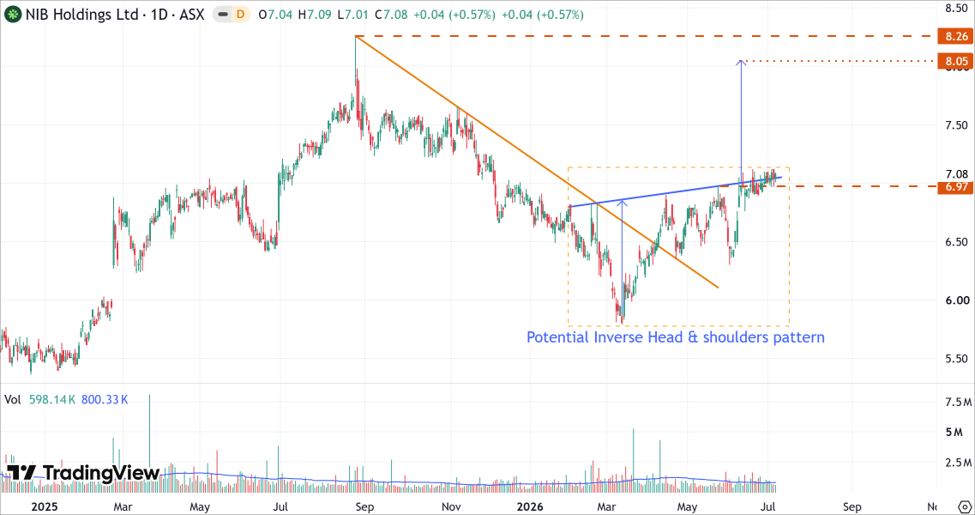
NHF’s Daily Price Chart (at the closing price of 08/07/2026). Powered by: tradingview.com
- On the daily chart, NHF's share price has developed a potential Inverse Head & Shoulders pattern dating back to February 2026, indicating a bullish bias.
- Should a decisive structural breakout above the pattern's neckline at $6.97 be confirmed, the path of least resistance would point higher, with the pattern's full measured move projecting a highly attractive structural target near the major horizontal resistance level at $8.05.
Bottom Line
NIB Holdings (ASX:NHF) appears to be entering a potentially significant recovery phase as improving industry pricing conditions, rising investment income, and renewed institutional interest combine to support a more constructive outlook. The stock's successful formation of a potential Inverse Head & Shoulders pattern suggests that the prolonged downtrend may be approaching exhaustion, while a confirmed breakout above the $6.97 neckline would further strengthen the bullish technical case. Although risks surrounding claims inflation, policyholder retention, and regulatory intervention remain, NHF's defensive earnings profile and emerging margin-recovery story position the company as an increasingly attractive turnaround candidate for investors seeking exposure to Australia's private health insurance sector.


 Nov 12, 2026





 Please wait processing your request...