
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Company Overview
Metro Mining Ltd is a Queensland-based bauxite producer operating the Bauxite Hills Mine on Cape York Peninsula, exporting shipments of high-quality bauxite directly to Chinese aluminium refiners (alumina producers). Bauxite is the primary input ore for aluminium production, and Metro's Bauxite Hills operation is one of the highest-purity direct-shipping bauxite deposits in Australia.
The company operates under a unique Business model — bauxite is extracted during Queensland's dry season window (typically April to October) and shipped directly to Chinese customers via cape-size vessels, with the wet season limiting the operational window but also reducing operating cost periods. This seasonal model creates lumpy but predictable Revenue flows aligned with the production season.
China is the world's largest aluminium producer and therefore the largest bauxite consumer, creating a natural market for Metro's high-purity product. The company has established long-term Supply relationships with Chinese aluminium producers that provide revenue visibility and pricing certainty. With global bauxite supply increasingly constrained by Indonesian and Guinean export restrictions, Australian high-quality bauxite commands a premium in the international market.
Fundamental Insights
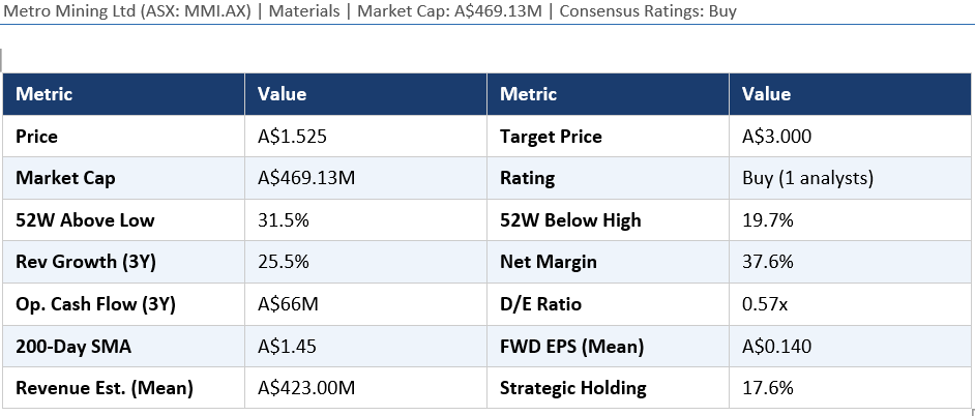
Metro Mining delivers impressive financial metrics for a mid-size resources company. Revenue has grown at 25.5% per annum over three years, driven by higher shipment volumes and improved bauxite pricing. Net profit Margin of 37.6% is outstanding, reflecting the high-margin nature of a direct-shipping, low-cost, high-purity bauxite operation with minimal processing requirements.
Operating Cash Flow of A$66 million over three years is substantial relative to the company's A$469 million Market Capitalisation, implying a high trailing cash flow Yield. Debt-to-Equity of 0.57x is moderate and appropriate for a mining operation with Capital Investment requirements for fleet and infrastructure.
The single analyst's EPS estimate of A$0.14 and revenue of A$423 million have no dispersion — a single model with no competing views. At the current price of A$1.525, the implied forward P/E is approximately 10.9x on A$0.14 EPS, a reasonable multiple given the growth profile and margin quality. The 200-day SMA of A$1.45 is close to the current price, confirming a modest positive trend.
Broker Views and Analyst Consensus
One analyst covers Metro Mining with a Buy rating and an aggressive target of A$3.00, implying 96.7% potential upside from the current price of A$1.525. This is the largest analyst-to-price upside gap in the peer group, suggesting either significant market undervaluation or that the analyst's modelling includes optimistic production scaling assumptions.
The bull thesis centres on Metro's competitive positioning as a direct-shipping high-purity bauxite supplier to China in a market where other major suppliers (Indonesia, Guinea) are facing export restrictions or logistical constraints. The seasonal production model creates Operating Leverage — as the company expands its seasonal shipment window and fleet, revenue scales with limited additional Fixed Cost.
Risks include the concentrated single-customer geography of China, the operational window limitation imposed by Queensland wet season conditions, Commodity price exposure to bauxite and aluminium markets, and the thin analyst coverage creating information gaps for investors. The 19.7% pullback from the 52-week high also indicates some market caution.
Technical Analysis
Metro Mining is only 31.5% above its 52-week low — one of the smaller recoveries in this peer group — and sits 19.7% below its 52-week high, suggesting the stock is in a soft period relative to some peers. The 200-day SMA at A$1.45 is close to the current price of A$1.525, confirming a tenuous uptrend that needs to hold above the SMA to remain constructive.
The near-100% upside implied by the analyst target of A$3.00 is extraordinary but would require significant positive catalysts — likely production expansion announcements or a bauxite price spike — to materialise. Support is at A$1.45 (SMA) and A$1.30 below that. Resistance at A$1.80 is the first meaningful target. RSI appears moderate, leaving room for upside if catalysts emerge.
Investor Insights
Metro Mining is a speculative high-upside opportunity for investors who believe in the Chinese bauxite Import Demand story. The 97% upside to target price is healthy if the analyst model is achievable, but the thin coverage and seasonal business model Warrant conservative approach. Current price near the 200-day SMA offers a technically supported entry with a defined stop-loss below A$1.30. The primary catalyst is the annual production and shipping season update, which drives the key revenue metric.


 Nov 12, 2026





 Please wait processing your request...