
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Company Overview
Metals X Ltd is Australia's largest tin producer, operating the Renison Bell Tin Mine in Tasmania through its 50% ownership interest in the Bluestone Mines Tasmania joint venture with PT Timah of Indonesia. Renison Bell is one of the highest-grade tin mines in the world and one of the few major tin-producing operations outside of Southeast Asia and China, giving it significant strategic importance in the global tin Supply chain.
Tin is increasingly recognised as a critical mineral essential for the global energy transition and technology sector, with significant Demand coming from the semiconductor industry (solder), the electric vehicle battery sector, and solar panel Manufacturing. As the world electrifies, tin demand is structurally growing while new large-scale mine supply remains difficult to bring online.
Metals X's financial profile has been transformed by elevated tin prices and strong operational performance at Renison Bell. The company also holds exploration Assets including the Wingellina Nickel-Cobalt Project in Western Australia, providing additional critical minerals optionality. The near-Debt-free Balance Sheet (D/E of 0.01x) reflects the cash-generative quality of the tin operations and prudent Capital management.
Fundamental Insights
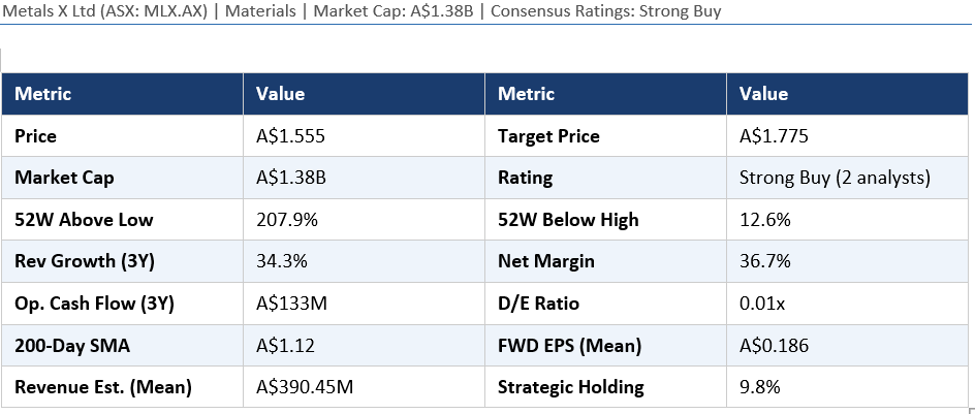
Metals X delivers exceptional financial metrics driven by its high-grade tin operations. Revenue has grown at 34.3% per annum over three years, reflecting both Volume growth as Renison Bell expands and tin price tailwinds from critical minerals demand. Net profit Margin of 36.7% is outstanding, placing Metals X among the most profitable mid-tier miners on the ASX.
Operating Cash Flow of A$133 million over three years is a standout metric — equivalent to 9.6% of the current Market Capitalisation annually — suggesting the stock may be significantly undervalued on a cash flow basis. The virtually debt-free balance sheet (D/E of 0.01x) is exceptional, confirming that the company has generated sufficient cash to fund operations and growth without external debt.
Two analysts project EPS of A$0.170-A$0.202 and revenue of A$376-A$405 million. At the current price of A$1.555 and mean EPS of A$0.186, the forward P/E is approximately 8.4x — very low for a high-margin, growth-oriented critical minerals producer. The 200-day SMA at A$1.12 is well below the current price, confirming the powerful uptrend of the past year.
Broker Views and Analyst Consensus
Two analysts cover Metals X with one Strong Buy and one Buy, and a consensus target of A$1.775, implying 14.1% upside from the current A$1.555. The positive ratings and the strong track record of Earnings delivery support the positive consensus. The bull case is centred on tin's critical minerals status, Renison Bell's Tier 1 asset quality, and Metals X's extraordinarily low valuation relative to cash flow.
Brokers highlight the company's optionality from its nickel-cobalt exploration assets as a potential re-rating catalyst if nickel and cobalt prices recover. The joint venture structure with PT Timah also provides access to Indonesian tin sector expertise, though it dilutes Metals X's economic interest to 50%.
Key risks include tin price Volatility — while tin has structural demand drivers, it remains a Commodity subject to cyclical price movements. Underground Mining operations at Renison Bell carry inherent operational risks, and the 50/50 joint venture structure means Metals X has limited unilateral control over major operational decisions.
Technical Analysis
Metals X has experienced one of the most dramatic price surges in this peer group, with a 207.9% gain above its 52-week low. The stock remains 12.6% below its 52-week high, suggesting some pullback from the peak. The 200-day SMA at A$1.12 is substantially below the current A$1.555, confirming the strength of the uptrend. Near-term support sits at A$1.45-A$1.50, and the analyst target of A$1.775 represents the next meaningful upside level.
A sustained hold above A$1.45 and a break above A$1.70 would be technically constructive for a run toward the analyst target. RSI has likely normalised from the overbought peak, offering technical room for further appreciation. Volume patterns should be monitored for confirmation of institutional accumulation.
Investor Insights
Metals X is a high-quality critical minerals Investment at a healthy valuation. The 8.4x forward P/E, A$133 million in three-year operating cash flow, debt-free balance sheet, and analyst Buy ratings create a strong multi-Factor investment case. Current prices offer 14.1% near-term upside to consensus target, with additional medium-term upside if tin prices remain elevated or nickel-cobalt assets attract interest. A pullback toward A$1.45 would be a strong buy opportunity. Stop-loss below A$1.30 defines downside risk. Long-term investors should treat this as a core critical minerals holding.


 Nov 12, 2026





 Please wait processing your request...