
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Company Overview
Macquarie Group Ltd is one of Australia's most globally recognised financial institutions, operating across asset management, banking and financial services, commodities and global markets, and Macquarie Capital. Often described as the 'millionaire's factory' for its generous staff bonuses, Macquarie has built a reputation as a world-class infrastructure investor and dealmaker. The group manages over $900 billion in Assets globally, with a particularly strong footprint in green energy infrastructure, renewables financing, and private Credit. It operates in more than 30 countries and has become a benchmark-independent, performance-driven Business that consistently delivers above-cost-of-capital returns.
Fundamental Insights
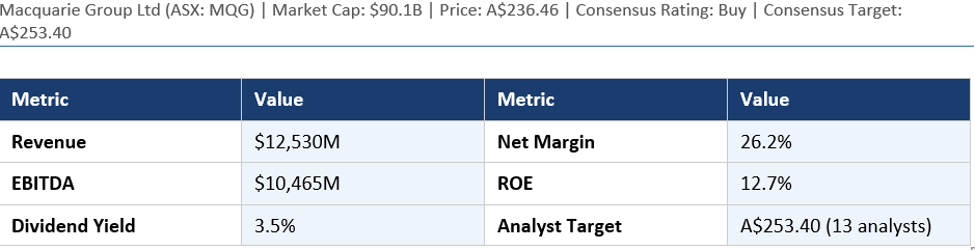
Macquarie's scale is reflected in its $12.5 billion in Revenue, a figure that grew 97.8% year-on-year reflecting the impact of asset realisations, fee income, and market activity. EBITDA of $10.5 billion and an EBITDA Margin of 22.2% confirm strong operational efficiency across its diversified divisions. Net margin of 26.2% is impressive for a financial conglomerate of this size. ROE of 12.7% remains healthy given capital allocation discipline and the mix of asset-heavy and asset-light businesses. The 3.5% Dividend Yield provides steady income, while a gross margin of 22.9% reflects the revenue mix of fee income and principal activities. Revenue growth of 5.2% on an adjusted basis points to solid organic momentum.
Broker Views and Analyst Consensus
Macquarie carries one of the broadest and most consistent Buy-Side coverages of any ASX-Listed Stock, with 13 analysts maintaining a Buy recommendation and a consensus target of $253.40. This implies roughly 7% upside from current levels of $236.46, a modest premium that reflects the stock's status as a core institutional holding. Brokers cite Macquarie's green energy infrastructure platform as a multi-decade growth driver, with billions in capital to be deployed across wind, solar, and battery storage globally. The asset management business continues to attract co-Investment capital, compounding AUM growth. Key risks include macro-driven slowdowns in deal activity and regulatory changes in key markets.
Technical Analysis
MQG is trading at $236.46, within 7% of its 13-analyst consensus target of $253.40. The stock has been constructively trending higher following a period of base-building. Near-term resistance sits at $245, which aligns with prior highs. Support is firm at $225-$228, supported by institutional buying interest. RSI in the mid-50s suggests room for further upside before technical exhaustion. The stock's large-cap status means it is less susceptible to sharp corrections absent sector-wide events.
Investor Action Points
MQG is a core holding for long-term investors seeking exposure to global infrastructure, green energy, and diversified financial services. The buy case is strongest for those with a 2-3 year horizon, where Macquarie's infrastructure pipeline and AUM growth compound meaningfully. At $236, the stock is positioned below a near-unanimous analyst target. Dollar-cost averaging into weakness is a sound strategy. Income investors benefit from a probable 3.5% yield.
Disclaimer: This article is for informational purposes only and does not constitute financial advice. Investors should conduct their own Due Diligence and consult a licensed financial adviser before making investment decisions. Past performance is not indicative of future results.


 Nov 12, 2026





 Please wait processing your request...