
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Company Overview
Korvest Ltd is a South Australian industrial manufacturing company that produces cable management systems, including cable trays, conduits, and supports used in commercial construction, mining, defence, and infrastructure projects. The company operates under two primary brands — EzyStrut and Tank Holdings — serving electricians, electrical contractors, and industrial engineers across Australia and selected export markets.
Korvest's products are essential components in any building or industrial installation requiring electrical cabling management, making the company a quiet but critical enabler of Australia's construction and infrastructure boom. With the Australian government committing billions of dollars to infrastructure, defence, and renewable energy projects, demand for Korvest's core products is strongly linked to the infrastructure investment cycle.
The company has operated profitably for decades, earning a reputation for product quality, technical support, and reliable supply chain execution. Its South Australian manufacturing base provides geographic proximity to the defence and naval industries centred on Osborne, where naval shipbuilding projects represent a multi-decade demand driver. Strategic entities hold 32.1% of shares, with the founding family maintaining meaningful involvement in the business. Korvest is a low-profile but resilient compounder with a track record of consistent earnings and dividends.
Fundamental Insights
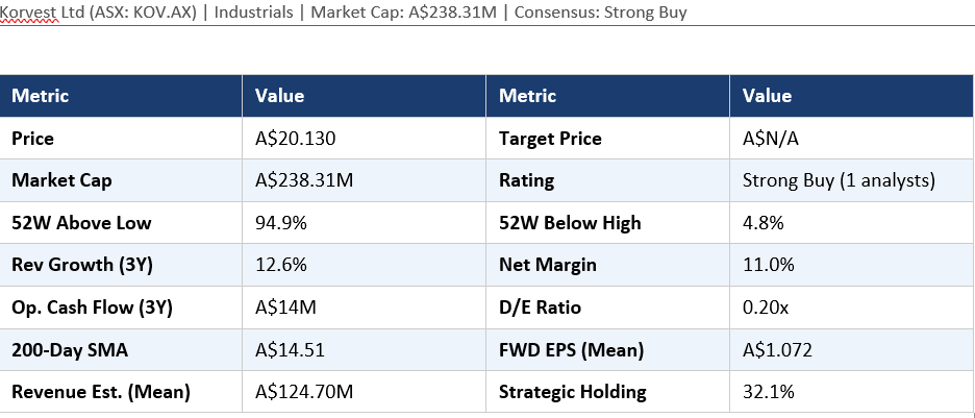
Korvest's financial profile is that of a mature industrial business with steady, reliable growth. Three-year average revenue growth of 12.6% reflects the improvement in construction activity and infrastructure spending across Australia's eastern and southern seaboards. Net profit margin of 11.0% is healthy for an industrial manufacturer, demonstrating operational efficiency and pricing discipline in competitive supply markets.
Operating cash flow of A$14 million over three years confirms strong cash generation relative to the company's market capitalisation of A$238 million, implying a high-single-digit cash flow yield. Debt-to-equity of 0.20x is conservative, reflecting the founders' preference for balance sheet prudence and providing resilience through industry downturns.
No formal target price is available from the covering analyst, but the Strong Buy rating carries significant weight as a signal of conviction. At EPS of A$1.072, the forward P/E based on the current price of A$20.13 is approximately 18.8x — a reasonable multiple for an industrial leader in a structural growth phase. The 200-day SMA of A$14.51 versus current price of A$20.13 confirms a powerful uptrend driven by re-rating and earnings momentum.
Broker Views and Analyst Consensus
Korvest has a single covering analyst who rates it Strong Buy with no published formal price target, an unusual but not unprecedented situation where the analyst conviction is high but target price model is either pending update or not publicly disseminated. The stock has nonetheless responded with a 94.9% gain above its 52-week low, suggesting the market itself has been building a strong buying case independent of formal analyst targets.
The bull thesis centres on Korvest's exposure to Australia's sustained infrastructure investment pipeline, including NDIS-related construction, renewable energy infrastructure, and the massive AUKUS submarine and defence shipbuilding programme centred in South Australia. The company's supply relationships with major electrical and construction contractors create recurring demand, and the proprietary EzyStrut system has become an industry standard specification.
Risks include the cyclical nature of construction activity, potential cost inflation in raw materials including steel and aluminium, and the risk that infrastructure project timelines slip or are repriorised. The micro-cap size and limited coverage also mean that negative news can create outsized price declines in the absence of a broad institutional shareholder base.
Technical Analysis
Korvest has been one of the standout performers in the industrial sector, with a 94.9% price gain above its 52-week low and only 4.8% below its 52-week high. The 200-day SMA at A$14.51 is dramatically below the current price of A$20.13, confirming a very strong and sustained uptrend. The stock is approaching the top of its annual range with minimal overhead resistance, suggesting further price discovery is possible.
The immediate technical picture shows a stock in a momentum-driven uptrend approaching its highs. Support levels sit at A$18.50 (recent consolidation) and A$17.00 below that, with A$14.51 as the major SMA support. The absence of a formal price target from the covering analyst means technical levels are particularly important for setting exit and risk management points. RSI is likely elevated given the magnitude of the move.
Investor Insights
Korvest is a quality Australian industrial compounder that offers infrastructure thematic exposure in a small, liquid package. The Strong Buy conviction from the covering analyst and the extraordinary price performance validate the investment case. For new investors, a pullback toward A$18.50-A$19.00 would offer a better risk-adjusted entry than chasing the current all-time high zone. The EPS of A$1.072 provides a reasonable earnings floor, and the conservative balance sheet limits downside risk.
Disclaimer: This article is for informational and educational purposes only and does not constitute financial advice or a recommendation to buy or sell any security. Investors should conduct independent due diligence and seek advice from a licensed financial adviser before making any investment decisions. Past performance is not indicative of future results. All figures sourced from publicly available market data.


 Nov 12, 2026





 Please wait processing your request...