
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Company Overview
Kingsgate Consolidated Ltd is an ASX-listed gold and silver producer operating the Chatree Gold Mine in Phichit Province, central Thailand. After a prolonged period of suspension due to regulatory challenges with Thai authorities, Chatree was successfully recommissioned and returned to production in 2022, marking a transformative recovery for the company. The mine has since been steadily ramping up output, and with the gold price at historic highs, the financial recovery has been rapid.
Chatree is a large, long-life open-cut gold and silver mine with substantial resources and a proven processing circuit. The mine's restart has been executed methodically, with production escalating through successive quarters as additional equipment and workforce have been mobilised. The silver co-product provides meaningful by-product revenue that reduces the effective cost per gold ounce, improving overall economics.
Kingsgate operates in Thailand, a stable mining jurisdiction with established legal infrastructure for foreign miners operating under appropriate licences. The resumption of Chatree represents one of the more successful mine restarts in recent ASX gold sector history, and the company has rebuilt operational credibility with investors, analysts, and financing counterparties since recommissioning. The relatively low strategic shareholding of 9.6% leaves significant float for institutional accumulation as the investment case broadens.
Fundamental Insights
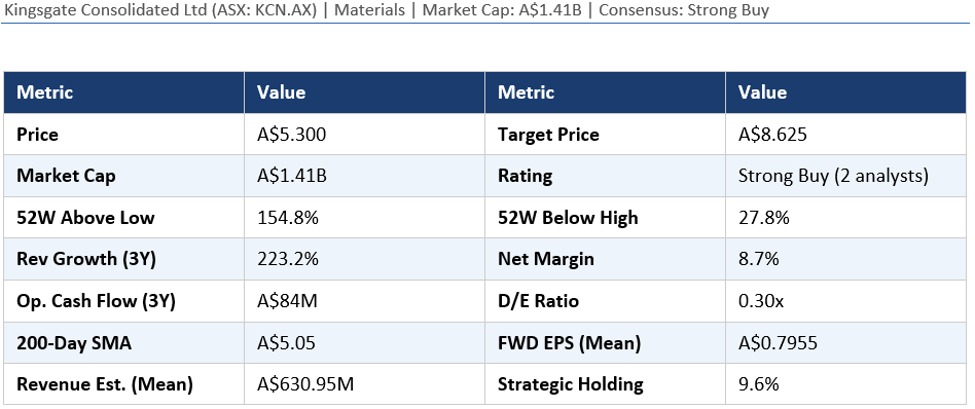
Kingsgate's three-year revenue CAGR of 223.2% is one of the most extraordinary in any sector on the ASX, reflecting the dramatic contrast between zero-revenue suspension years and the now-operational Chatree mine at an elevated gold price. This metric should be interpreted in the context of the mine restart rather than as organic growth from an established production base, but it nonetheless illustrates the scale of the financial transformation.
Operating cash flow of A$84 million over three years is substantial for a company that was generating no revenue during the suspension period, confirming the genuine economic merit of Chatree as a cash-generating asset. Debt-to-equity of 0.30x is moderate and appropriate given the financing required for mine restart capital expenditure.
Two analysts provide forward estimates with EPS of A$0.75-A$0.841 and revenue of A$627.8-A$634.1 million. At the current price of A$5.30, the forward P/E on mean EPS of A$0.796 is approximately 6.7x — a remarkably low multiple for a mine now generating significant gold production at historic gold prices. This dislocation between fundamental value and market price is the central bull case for KCN.
Broker Views and Analyst Consensus
Two analysts cover Kingsgate, with one Strong Buy and one Buy rating, and an aggressive consensus target of A$8.625 — implying 62.7% potential upside from the current price of A$5.30.
The core broker thesis is a classic valuation gap story: the market has not yet fully priced in the sustained Chatree production ramp-up, the impact of current elevated gold prices on earnings, and the exploration potential of Kingsgate's broader Thai licence holdings. Analysts argue the current forward P/E of approximately 7x is inconsistent with the quality and growth trajectory of the asset.
Key risks include Thai regulatory environment, which has previously caused the mine suspension and remains a tail risk for ongoing operations. Gold price sensitivity is material — the economics of Chatree are highly leveraged to spot gold prices. Currency risk from AUD/USD and AUD/THB movements also affects reported earnings.
Technical Analysis
Kingsgate has appreciated 154.8% above its 52-week low, confirming the strong recovery narrative that has driven the re-rating. However, the stock is currently 27.8% below its 52-week high, suggesting it has pulled back meaningfully from peak levels — an entry opportunity for new investors relative to recent highs.
The 200-day SMA at A$5.05 is close to the current price of A$5.30, meaning the stock is hovering just above its major moving average — a technically important level. A sustained hold above A$5.05 is critical for the bullish thesis. Support below sits at A$4.80 and A$4.50. The broker target of A$8.625 represents a potential 62.7% total return, providing a fundamental upside target.
Investor Insights
Kingsgate is a high-potential, high-conviction opportunity for investors comfortable with emerging market mining risk. The combination of a 7x forward P/E, 62.7% analyst upside target, and Buy consensus makes the fundamental case very strong. The current price hovering above the 200-day SMA provides a technically supported entry. Set a stop-loss below A$4.80 (below SMA and recent support). The primary catalyst is continued quarterly production reports showing Chatree output growth and cash flow generation. Gold price direction is the macro variable that will amplify or dampen the return profile significantly.
Disclaimer: This article is for informational and educational purposes only and does not constitute financial advice or a recommendation to buy or sell any security. Investors should conduct independent due diligence and seek advice from a licensed financial adviser before making any investment decisions. Past performance is not indicative of future results. All figures sourced from publicly available market data.


 Nov 12, 2026





 Please wait processing your request...