
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Company Overview
Karoon Energy Ltd is an ASX-listed oil and gas producer with its primary Assets in offshore Brazil, operating the Bauna and Patola oil fields in the Santos Basin. The company transformed from an explorer to a producer through the 2020 Acquisition of the Bauna field from Petrobras, and has since delivered consistent production growth and strong financial results from its Brazilian operations.
Brazil is one of the world's premier deepwater oil producing nations, with the Santos Basin hosting some of the largest and most prolific offshore oil discoveries of the past two decades. Karoon's assets benefit from established subsea infrastructure, well-understood reservoir characteristics, and Brazil's stable oil sector regulatory environment governed by the ANP (National Petroleum Agency).
The company has a highly experienced Brazilian oil operations team and strong working relationships with Brazilian government agencies and service providers. With oil prices remaining constructive and the production base established, Karoon is generating significant Operating Cash Flow that supports both reinvestment in drilling programmes and potential Capital returns to shareholders. The low strategic shareholding of 2.3% means the float is almost entirely free-trading, which improves Liquidity for institutional investors.
Fundamental Insights
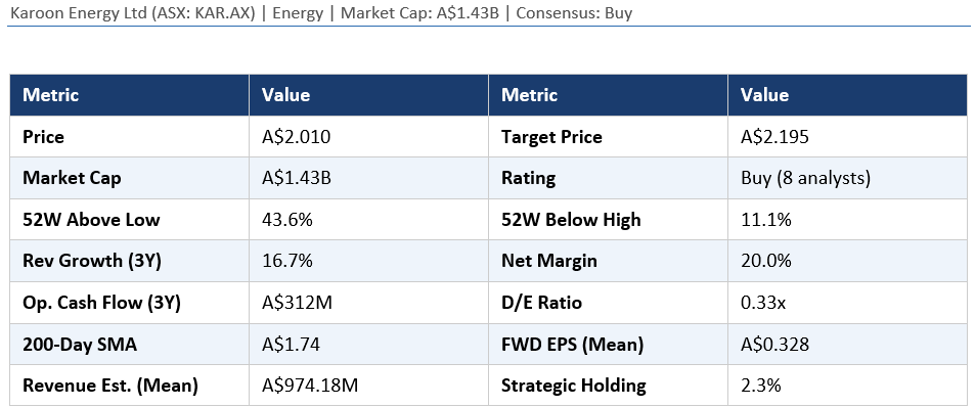
Karoon Energy's financial profile is that of an established, profitable oil producer. Revenue has grown at 16.7% per annum over three years, reflecting the progression of production from the Bauna field following the acquisition and subsequent development drilling. Net profit Margin of 20.0% is solid for an oil producer, though the extraordinarily wide EPS estimate range (A$0.120 to A$0.495) reflects the oil price sensitivity of the Earnings model.
Operating cash flow of A$312 million over three years is a standout metric — equivalent to 21.8% of the current Market Capitalisation annually, suggesting a very high free cash flow Yield that is the central value proposition for the stock. Debt-to-Equity of 0.33x is moderate and appropriate for an oil company with production assets requiring ongoing capital Investment.
Eight analysts provide coverage with the mean EPS estimate of A$0.328 and mean revenue of A$974 million. At the current price of A$2.01, the forward P/E on mean EPS is approximately 6.1x — very low for a profitable, cash-generative oil producer. This low multiple reflects both oil price uncertainty and the market's scepticism about offshore Brazilian oil operations for a relatively small company.
Broker Views and Analyst Consensus
Eight analysts cover Karoon Energy — the largest analyst panel in this peer group — with 2 Strong Buy, 2 Buy, and 4 Hold ratings. The consensus target of A$2.195 implies 9.2% upside from the current A$2.01. The 4 Hold ratings moderate the consensus, but the 4 Buy/Strong Buy ratings from more bullish analysts indicate genuine conviction among active advocates of the stock.
The bull case centres on Karoon's Brazilian asset quality, the very high operating cash flow yield at current oil prices, and the potential for exploration success at the company's additional Santos Basin licences. The bears (Hold raters) focus on oil price sensitivity, the execution challenges of deepwater operations, and the single-Jurisdiction concentration risk of all production in offshore Brazil.
Key risks include oil price decline, which would compress margins significantly given the operating cost base, Brazilian regulatory and currency risk (BRL/AUD movements affect reported results), and the inherent operational risk of deepwater oil production.
Technical Analysis
Karoon is 43.6% above its 52-week low and 11.1% below its 52-week high — a moderate position within its annual range, suggesting neither extreme momentum nor deep value recovery. The 200-day SMA of A$1.74 is meaningfully below the current price of A$2.01, confirming a positive medium-term trend.
Near-term support at A$1.90-A$1.95 (recent consolidation) and A$1.74 (200-day SMA) provide defined risk management levels. The analyst target of A$2.195 sits 9.2% above current price, and a move toward A$2.20 is the near-term technical objective. The 4 Hold ratings moderate the bullish technical picture, suggesting the stock may trend sideways until an oil price or production catalyst materialises.
Investor Insights
Karoon Energy is a solid income-growth hybrid for investors seeking oil sector exposure with strong cash flow credentials. The A$312 million in three-year operating cash flow at a A$1.43 billion market capitalisation represents a very free cash flow yield. The mixed analyst consensus (4 Hold alongside 4 Buy/Strong Buy) suggests balanced risk-reward. Look for weakness toward A$1.90, with the analyst target of A$2.195 as the near-term trend. Stop-loss below A$1.74 (200-day SMA). Oil price direction remains the dominant macro variable.


 Nov 12, 2026





 Please wait processing your request...