
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Company Overview
IPH Ltd is the Asia-Pacific's leading intellectual property services group, providing Patent filing, trade mark registration, and related IP management services across Australia, New Zealand, Canada, Singapore, Hong Kong, Indonesia, Malaysia, Thailand, and China. The company operates through a portfolio of IP professional services firms including Spruson & Ferguson, Pizzeys, and FPA Patent Attorneys — brands with decades of history in their respective markets.
The intellectual property services sector is a structurally growing industry driven by rising innovation activity globally, increasing recognition of IP as a valuable corporate asset, and expanding filing requirements as companies seek to protect their technologies in multiple jurisdictions simultaneously. The growth of the Asia-Pacific technology and pharmaceutical sectors has been a particular driver of Demand for IPH's services.
IPH's Business model is highly recurring — patent annuities and trade mark renewals require periodic filings that generate multi-year Revenue streams from each client relationship. The company has also grown through acquisitions of smaller IP professional firms across its geographic footprint, integrating them into its scalable operational infrastructure and cross-selling additional services. Six analysts cover the stock, reflecting its institutional quality and Earnings predictability.
Fundamental Insights
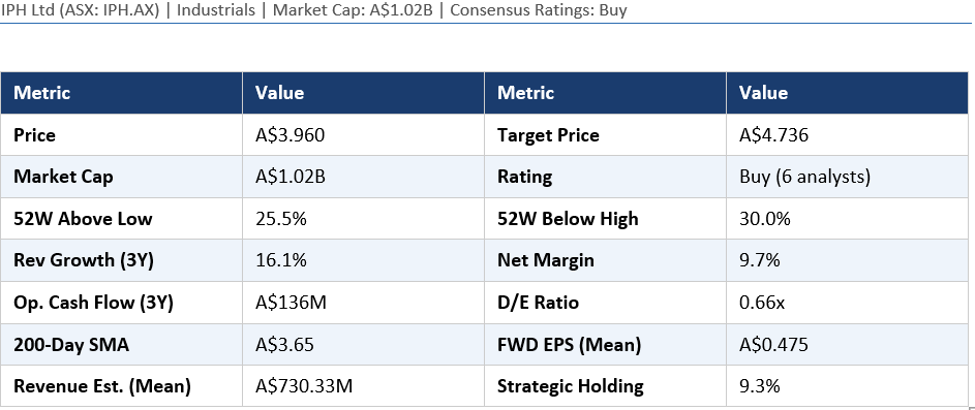
IPH's financial profile is that of a mature professional services group. Revenue has grown at 16.1% per annum over three years, driven by organic Volume growth and acquisitions. Net profit Margin of 9.7% is modest for the professional services sector, reflecting the cost structure of a Partnership-model IP firm where professional staff compensation is the primary Variable Cost.
Operating Cash Flow of A$136 million over three years is a strong metric relative to the A$1.02 billion Market Capitalisation — implying a high trailing cash flow Yield that is a key value signal for income-oriented institutional investors. Debt-to-Equity of 0.66x is moderate and primarily reflects Acquisition financing for the expansion of the IP firm portfolio.
Six analysts provide tight EPS estimates of A$0.457-A$0.482, reflecting high earnings predictability. Revenue consensus of A$730.33 million signals continued steady growth. At the current price of A$3.96 and mean EPS of A$0.475, the forward P/E is approximately 8.3x — a low multiple that reflects the stock's 30% pullback from its 52-week high and what appears to be a value opportunity within the professional services sector.
Broker Views and Analyst Consensus
Six analysts cover IPH Ltd with 1 Strong Buy, 3 Buy, and 2 Hold ratings — a broadly positive consensus. The mean target price of A$4.736 implies 19.6% upside from the current A$3.96, making IPH one of the more compelling valuation opportunities in this peer group relative to analyst conviction and business quality.
The bull thesis centres on the structural growth of IP filings in Asia-Pacific, IPH's market leadership position and Brand recognition in key markets, the recurring nature of Annuity and renewal revenue, and the acquisition pipeline that provides growth optionality beyond organic filing volume trends. The stock's 30% pullback from its 52-week high has created what Brokers argue is an unwarranted valuation discount.
The 2 Hold-rated analysts point to margin pressure from competition in the professional services market, integration risks from acquisitions, and the stock's relative complexity for investors not familiar with the IP services sector. Currency risk from multi-geography operations is also cited as a Factor.
Technical Analysis
IPH presents an interesting technical picture — it is 25.5% above its 52-week low but 30.0% below its 52-week high, meaning it has recovered only partially from what appears to have been a significant correction. This recovery-within-a-pullback setup is often where value investors find entry points.
The 200-day SMA at A$3.65 is below the current A$3.96, suggesting the immediate trend is positive but the stock has not fully recovered from the 52-week high decline. Resistance at A$4.50 and then A$4.74 (analyst target) are the key upside milestones. Support at A$3.65 (SMA) and A$3.40 below that provide defined risk management parameters.
RSI is likely in a neutral zone given the partial recovery, leaving room for upside. The 19.6% potential return to analyst consensus target and the 4 Buy/Strong Buy ratings suggest the fundamental tailwind is building.
Investor Insights
IPH is a quality value opportunity within the professional services sector. The 30% pullback from 52-week highs, 8.3x forward P/E, A$136 million three-year operating cash flow, and 19.6% upside to broker consensus create a well-rounded Investment case. The stock is suitable for value-oriented investors seeking exposure to the Asia-Pacific IP sector with income characteristics from strong cash flow generation. Initiate at current levels with a target of A$4.736 aligned with broker consensus. Stop-loss below A$3.65 (200-day SMA). The primary catalyst is quarterly revenue updates demonstrating continued filing volume growth across the Asia-Pacific region.


 Nov 12, 2026





 Please wait processing your request...