
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key highlights
- The company delivered a strong 15.2% increase in net profit after tax.
- Shareholders will receive a 20.8% increase in the fully-franked interim dividend.
- The company is facing a new class action lawsuit, adding significant risk.
- Strategic growth in the British market resulted in $10 million in establishment losses.
Given the tug-of-war between strong fundamentals and associated risks, we will examine the (ASX:HVN) short-term trend from a technical perspective.
Financial Resilience and Asset-Backed Strength
- Harvey Norman maintains a robust fundamental profile, highlighted by its recent 1H26 results (ending December 31, 2025) which showed a 15.2% increase in net profit to $321.91 million.
- The company operates a unique "three-pillar" model, comprising Australian franchising, overseas company-operated stores, and a massive $4.4 billion property portfolio, which provides a stable asset base and diversified income streams.
- Financially, the group is conservatively geared with a low net debt-to-equity ratio of 13.02% and strong cash conversion of 96.2%.
- This balance sheet strength supported a 20.8% increase in the fully-franked interim dividend to 14.5 cents per share, reflecting management's commitment to returning capital even as it continues an on-market share buyback program.
Associated risks and challenges
- The company was recently named as a defendant in a class action lawsuit regarding historical "interest-free" advertising, which could lead to significant financial penalties and damage consumer trust.
- As a consumer discretionary retailer, its earnings remain sensitive to inflationary pressures and high interest rates, which may dampen household spending on "big-ticket" items like furniture and electronics.
- While overseas growth has been strong, the company recently reported $10 million in start-up losses for its UK operations, highlighting the execution risks and high costs associated with competing in crowded international markets.
Technical Outlook
Harvey Norman Holdings Limited (ASX:HVN)
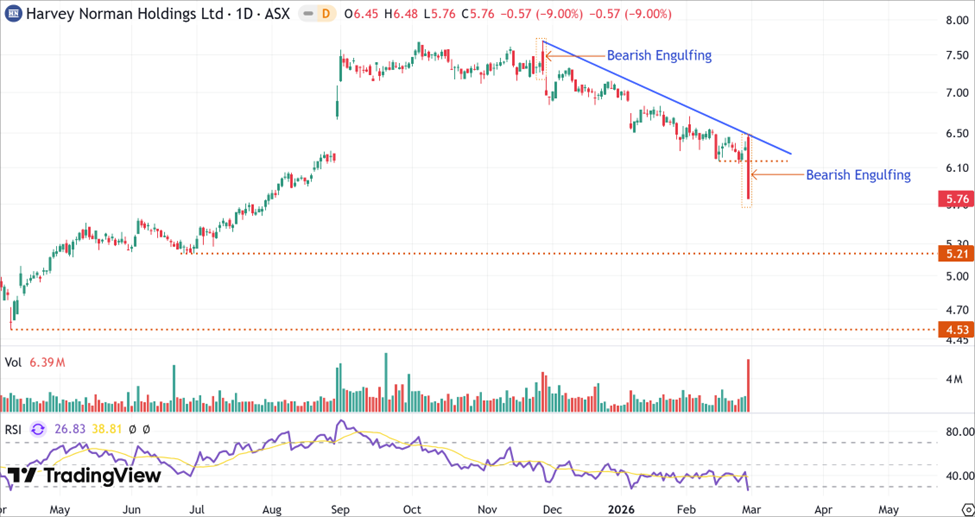
HVN’s Daily Price Chart (at the closing price of 27th February 2026). Powered by: tradingview.com
- Since October 2025, HVN’s stock price has been undergoing a short-term downtrend characterized by lower highs and lower lows on the daily chart, indicating a negative bias.
- This downtrend strengthened on 27 February 2026, as the stock broke below its nearest trough, a significant support, coupled with a Bearish Engulfing candlestick pattern and a spike in trading volume.
- The immediate support for the stock is now placed at $5.21. In case this support is penetrated, the stock might find stronger support near the April 2025 trough at $4.53.
Bottom Line
Harvey Norman remains a fundamentally strong business with a $4.4 billion property portfolio and double-digit profit growth. However, the combination of a high-volume technical breakdown and a new class action lawsuit has created significant short-term downward pressure. Until the stock stabilizes above the $5.21 support level, the current bearish momentum is likely to outweigh the company’s strong asset base in the immediate future.


 Nov 12, 2026





 Please wait processing your request...