
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
- FPH suffered from "swampy waters" in 2024-2025 as hospitals used up old stock. The 2026 story is about record revenue and margin repair.
- In its recent half-year update, FPH reported a 39% jump in net profit.
- They achieved $1 billion in half-year revenue for the first time. Gross margins have climbed back to 63%, nearing their long-term target of 65%.
Fisher & Paykel Healthcare (ASX:FPH) exemplified a high-quality 'structural growth' stock navigating a pandemic-driven demand spike. After a painful normalization period, the company has eventually returned to its long-term average performance.
The "reversion to the mean" story
During the COVID-19 crisis, the company experienced a massive "pull-forward" of demand, sending its earnings and share price to unsustainable heights as global hospitals stockpiled respiratory hardware. This was followed by a punishing "hangover" period in 2022 and 2023, where the stock price plummeted nearly 50% as the market overcorrected for a temporary glut in hospital inventory and normalized patient numbers. However, the true reversion occurred when the company’s massive, newly expanded "installed base" of devices began requiring consistent consumable parts again. By 2025 and into early 2026, FPH successfully traded through the volatility, with record revenues of $2.02 billion confirming that the business has not only returned to its mean growth rate of ~10% but is doing so from a structurally larger and more dominant global position.
The associated risks
Despite its strong recovery, investing in Fisher & Paykel Healthcare (FPH) carries inherent risks, particularly as it navigates the final stages of its post-pandemic realignment. The primary concern remains the normalization of hospital buying patterns; if healthcare providers continue to utilize existing stockpiles longer than anticipated, consumable revenue could underperform expectations. Additionally, as a global exporter, FPH is heavily exposed to currency fluctuations and macroeconomic volatility, which was starkly illustrated by the stock's recent 7.1% tumble in February 2026 amid broader global sector fears.
Technical Analysis Outcook
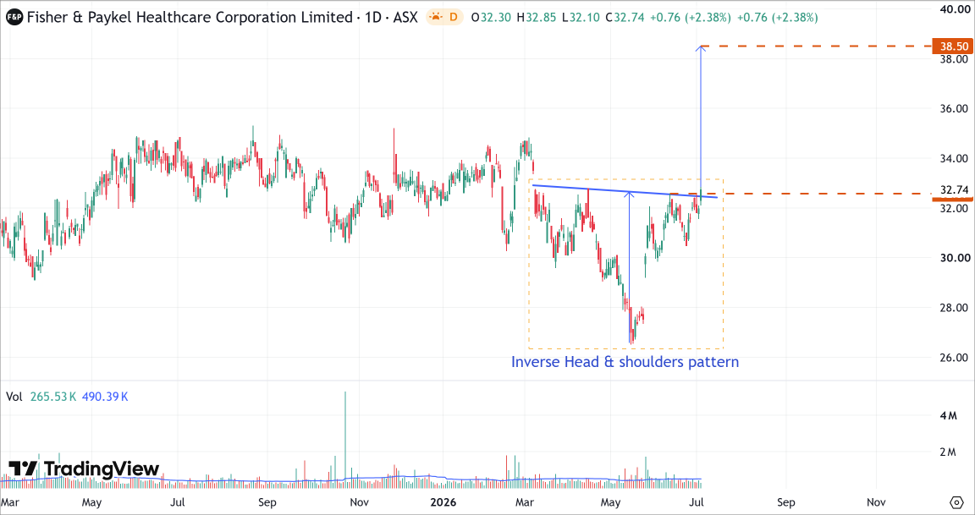
FPH’s Daily Price Chart (at the closing price of 03/07/2026). Powered by: tradingview.com
On the weekly chart, FPH’s stock price is developing a consolidation phase characterized by an inverse head and shoulders pattern within an established uptrend. This price action suggests that if the stock decisively breaks above the neckline at $35.00, it could resume its broader bullish trajectory. Such a breakout would indicate that the company has finally completed its reversion to the mean, with a technical price target of $41.50, a projection equal to the pattern's vertical height.
Bottom Line
Fisher & Paykel Healthcare (ASX:FPH)‘s multi-year "reversion to the mean" is entering its final. By navigating the "swampy waters" of hospital destocking and restoring gross margins toward the 65% gold standard, the company has transformed its pandemic-era volatility into a structurally larger, high-performance growth engine. Technically, the stock is establishing a potent inverse head and shoulders pattern on the weekly chart, with a decisive breakout above $35.00 paves the way for a technical price target of $41.50.


 Nov 12, 2026





 Please wait processing your request...