
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
- EVT Limited continues to face operational headwinds as cost-of-living pressures may be moderating middle-income discretionary spending across its hotel and cinema divisions.
- As the broader market reviews the valuation multiples of hospitality Assets in a higher Interest Rate environment, institutional Capital might be reducing its exposure.
- The technical price action is flashing potential warning signs, characterized by the development of what appears to be a large-scale Head &Amp; Shoulders distribution pattern that is testing critical structural support.
While EVT Limited (ASX:EVT) spent previous cycles relying on the post-Pandemic recovery in domestic tourism and entertainment, the technical landscape has recently shown a potential shift toward structural exhaustion. As the broader market evaluates the resilience of consumer discretionary Assets against a backdrop of persistent Inflation, EVT appears to be experiencing a phase of institutional distribution. The recent softening in price action suggests that the long-term mark-up phase might be concluding, which could potentially lead to a new cyclical downtrend.
Discretionary Pressures and Valuation
EVT’s fundamental Investment thesis is anchored to consumer mobility and entertainment spending, which are currently facing notable pressure:
- The Discretionary Contraction: The primary profit engine for EVT relies on discretionary spending. With elevated Mortgage rates impacting household budgets, consumers might be scaling back on domestic travel and entertainment.
- Property Valuation Pressures: While EVT is backed by a tangible property portfolio, higher Interest Rate environments can be challenging for Commercial Real Estate valuations. Institutional Capital may be becoming hesitant to pay a premium for property-heavy Assets facing potential downward cap-rate revaluations.
- Margin Compression: Operating premium hotels and cinemas involves notable labor and energy costs. Persistent Inflation across these operational inputs may structurally impact EVT’s core operating margins if top-line Revenue growth moderates.
Associated Risks
A primary risk for EVT Limited would be a broader economic slowdown. If a domestic Recession were to trigger a rise in Unemployment, the resulting dip in consumer confidence could impact the company's hotel occupancy rates and box office yields. Furthermore, the company’s Thredbo resort operations remain vulnerable to weather Volatility; consecutive poor snow seasons might compound existing macroeconomic Margin pressures.
Technical Outlook
The Daily Chart for EVT Limited reveals a potential deterioration in market structure, highlighting a classic example of buyer exhaustion.
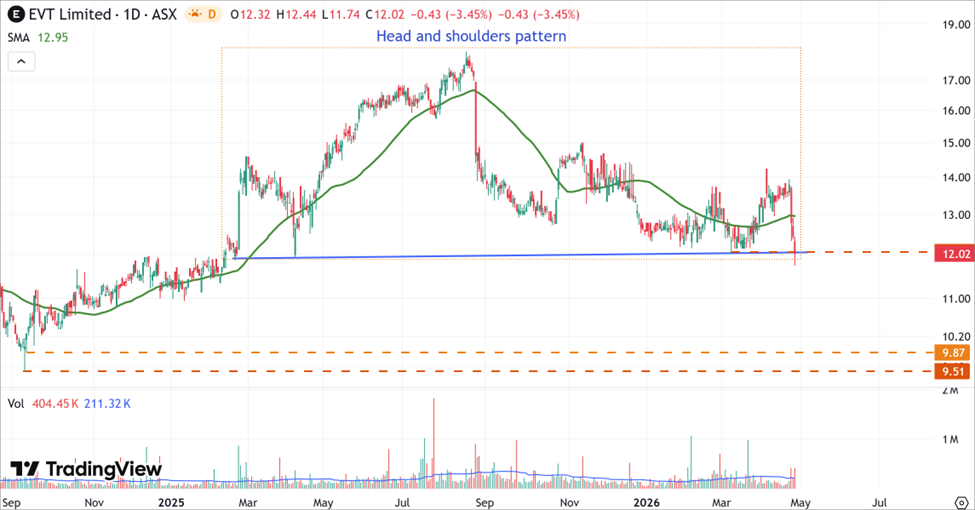
EVT’s Daily Price Chart (at the closing price of 29th April 2026). Powered by: tradingview.com
- On the Daily Chart, EVT’s stock price has developed a large-scale Head &Amp; Shoulders pattern dating back to February 2025, indicating a snegative bias.
- The critical structural support is positioned at the pattern’s neckline of $12.02. A decisive structural breakdown and daily close below this level would open the door to the next significant support zone, established by the September 2024 trough between $9.51 and $9.87.
EVT Limited (ASX:EVT) currently appears to be exhibiting signs of a cyclical breakdown. The stock is facing technical challenges as it finalizes a potential Head &Amp; Shoulders distribution pattern dating back to February 2025. Testing its critical structural support, the stock is now operating in a vulnerable technical environment. Investors and active traders may want to exercise caution and closely monitor the $12.02 neckline. A confirmed structural breakdown below this level could signal the end of the prior cycle and might favor a continued descent toward the $9.51 to $9.87 support floor.


 Nov 12, 2026





 Please wait processing your request...