
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Company Overview
Eureka Group Holdings Ltd is a specialist affordable senior housing provider listed on the ASX, operating a growing portfolio of villages designed for independent, low-to-moderate-income retirees across Queensland, New South Wales, Victoria, and South Australia. The company's model focuses on permanent rental accommodation rather than the deferred management fee structure common among larger listed retirement village operators, offering more transparent and predictable cash flow dynamics.
Eureka's villages typically serve retirees who do not qualify for government-funded aged care but cannot afford premium retirement living options, occupying a large and structurally underserved segment of the Australian retirement housing market. As Australia's population ages rapidly — with the number of Australians over 65 expected to double by 2050 — the demand for affordable, community-oriented senior housing is forecast to grow substantially.
The company has pursued a disciplined acquisition and development strategy, adding villages in high-demand regional and suburban markets. Strategic entities hold 37.9% of shares, reflecting strong alignment between management, major shareholders, and long-term investors. The company's social infrastructure mandate — providing quality housing for seniors on fixed incomes — also gives it an ESG relevance that institutional investors increasingly prize.
Fundamental Insights
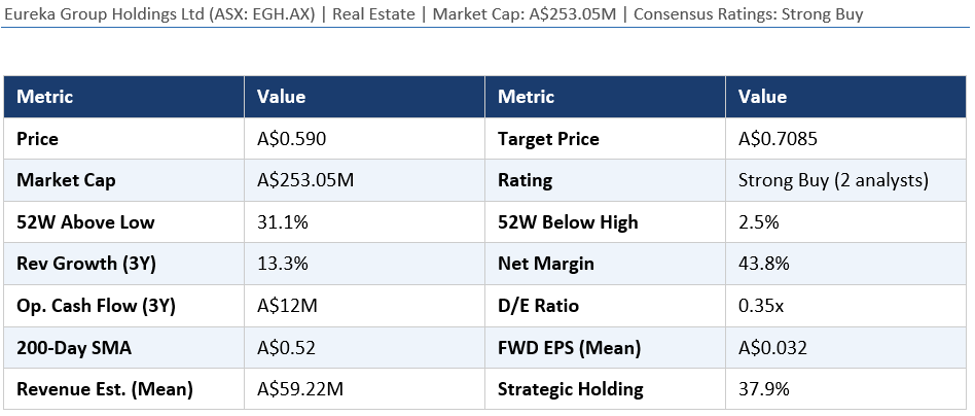
Eureka Group's financial metrics reveal a business with exceptional profit quality. The net profit margin of 43.8% is extraordinary and reflects both the recurring rental income model and the relatively low variable cost structure of operating senior housing villages. Revenue has grown steadily at 13.3% per annum over three years, consistent with both like-for-like occupancy improvements and village acquisitions.
Operating cash flow of A$12 million over three years underpins the sustainability of distributions and reinvestment capacity. Debt-to-equity of 0.35x is appropriate for a real estate business and is conservatively managed relative to the stability of the underlying rental income stream. The 200-day SMA of A$0.52 versus current price of A$0.59 confirms a positive medium-term trend.
Forward EPS estimates are tightly clustered between A$0.030 and A$0.034, signalling high earnings visibility and analyst confidence in the recurring revenue model. Revenue estimates range from A$56.94 million to A$61.5 million, with a mean of A$59.22 million. At the current price of A$0.59, the forward P/E on mean EPS is approximately 18.4x — a reasonable multiple for a real estate business with 43.8% net margins and a strong demographic demand tailwind.
Broker Views and Analyst Consensus
Two analysts cover Eureka Group, with one carrying a Strong Buy and one a Buy rating, generating the highest possible consensus signal for the company. The consensus target of A$0.7085 implies 20.1% upside from the current price of A$0.59, a meaningful return for a low-volatility real estate income stock. The Strong Buy designation from one analyst indicates exceptional conviction beyond the standard Buy recommendation.
The core broker thesis is straightforward: Eureka operates in an underserved market where structural demographic demand is almost guaranteed to grow, the company's rental model generates predictable high-margin cash flows, and the current valuation does not fully reflect the quality and durability of earnings. Analysts highlight the ESG appeal of affordable senior housing as an increasingly important factor in institutional allocation decisions.
Risks include the capital-intensive nature of village acquisitions, which requires ongoing access to debt markets at reasonable rates, and the regulatory environment around affordable housing policy, which could shift in ways that affect rent economics. The company is also small-cap in nature, with limited liquidity that can amplify price movements on news.
Technical Analysis
Eureka Group has posted 31.1% gains above its 52-week low and sits just 2.5% below its 52-week high, suggesting the stock is in the upper portion of its annual range and has significant upward momentum. The 200-day SMA at A$0.52 provides meaningful support well below the current A$0.59, and the gap between SMA and price confirms an established uptrend.
Near-term resistance at the 52-week high just above A$0.60 is the immediate technical hurdle. A close above A$0.62 on volume would constitute a breakout with the broker target of A$0.71 as the next meaningful level. Support sits at A$0.55 (recent consolidation base) and A$0.52 (200-day SMA). RSI appears moderate, leaving technical room for further appreciation before overbought signals emerge.
Investor Insights
Eureka Group is an income-growth hybrid for investors seeking small-cap real estate exposure with demographic tailwinds. The Strong Buy/Buy consensus and 20% upside to target make it an addition at current levels. The 43.8% net margin and tight EPS estimate range signal earnings predictability, which supports Buy rationale. A stop-loss below A$0.52 (200-day SMA) provides a risk management level. The 3-5 year horizon is optimal, aligned with the long demographic cycle driving affordable senior housing demand.
Disclaimer: This article is for informational and educational purposes only and does not constitute financial advice or a recommendation to buy or sell any security. Investors should conduct independent due diligence and seek advice from a licensed financial adviser before making any investment decisions. Past performance is not indicative of future results. All figures sourced from publicly available market data.


 Nov 12, 2026





 Please wait processing your request...