
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Company Overview
Elsight Ltd is an Australian-listed technology company specialising in advanced drone connectivity and autonomous unmanned systems solutions. Its flagship Halo platform provides multi-link, AI-assisted communications that enable drones and unmanned ground vehicles to maintain mission-critical connectivity in challenging and contested environments. Elsight's technology has attracted significant interest from defence agencies, border security organisations, and commercial drone operators globally, with its solutions deployed across Israel, the United States, Europe, and the Asia-Pacific region.
The company operates in one of the world's fastest-growing technology sectors, with the global drone connectivity market projected to expand at a compound annual growth rate exceeding 25% over the next decade. Elsight differentiates itself through proprietary bonding algorithms and edge AI processing capabilities that aggregate multiple cellular and satellite networks into a single resilient communications link. This architecture delivers military-grade reliability at commercially viable price points, positioning Elsight as a healthy choice for both defence prime contractors and civilian drone service providers.
Elsight is headquartered in Israel, with ASX listing providing Australian investor access to its global growth story. Strategic relationships with major defence integrators underpin a pipeline of repeat and scalable contracts, giving the company a visibility advantage over pure-play hardware competitors.
Fundamental Insights
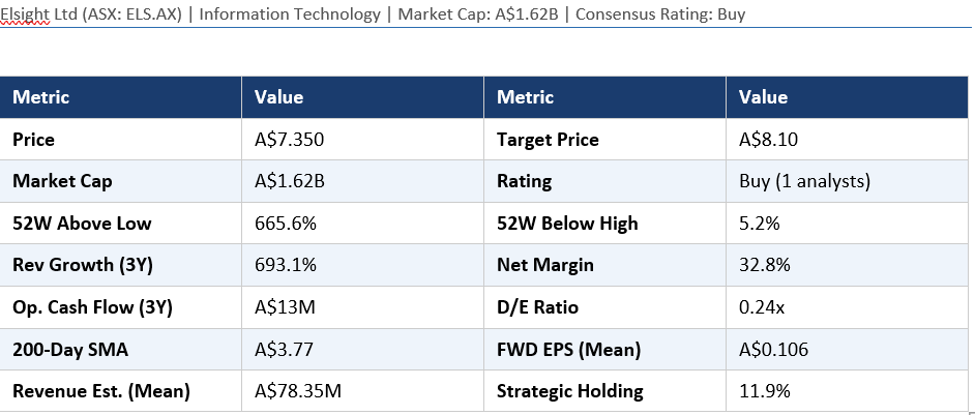
Elsight's fundamental metrics tell the story of a company in hyper-growth mode. Three-year average revenue growth of 693.1% is exceptional by any measure and reflects the explosive commercial traction of the Halo platform following its initial deployments. Net profit margin of 32.8% is remarkable for a company at this stage of development, confirming that Elsight has found a business model that scales profitably rather than burning cash on growth.
Operating cash flow averaging A$13 million over three years demonstrates genuine cash generation, a critical differentiator from many early-stage technology companies that show accounting profits but negative cash flow. The debt-to-equity ratio of 0.24x is very low, indicating a conservatively financed balance sheet with significant capacity for future investment or acquisitions without excessive leverage risk.
Forward estimates from the single covering analyst project EPS of A$0.106 and revenue of A$78.35 million, suggesting sustained but more normalised growth as the company matures from its initial explosive phase. At a current price of A$7.35 versus a 200-day SMA of A$3.77, the stock has materially re-rated higher as the market recognises its growth credentials. The stock sits only 5.2% below its 52-week high, confirming strong and sustained momentum. The implied price-to-earnings ratio based on forward EPS is approximately 69x, reflecting growth-stock premium pricing that is justified by the revenue trajectory and margin quality.
Broker Views and Analyst Consensus
With a single analyst covering Elsight and maintaining a Buy rating with a target price of A$8.10, the implied upside from the current price of A$7.35 is approximately 10.2%. While coverage breadth is limited, the conviction level from the covering analyst is high, and the target price reflects confidence in continued commercial momentum.
The bull case centres on Elsight's position at the intersection of drone autonomy, defence technology, and AI-driven communications, all of which are experiencing structural demand increases driven by geopolitical tensions and the professionalisation of unmanned systems across military and civilian applications. Strategic entities hold 11.9% of the company, providing a degree of institutional validation and alignment of interest.
Key risks flagged in broker analysis include concentration risk from a small number of large defence contracts, currency exposure from USD and ILS-denominated revenues, and the execution risk inherent in scaling a technology platform globally. However, the track record of 693% revenue CAGR suggests that management has demonstrated the ability to execute under competitive conditions.
Technical Analysis
Elsight has been one of the most dramatic re-rating stories on the ASX, with the stock sitting 665.6% above its 52-week low and only 5.2% below its 52-week high. This positioning — deep into a long-term uptrend and approaching the peak — suggests the stock is in price discovery mode rather than a defined range.
The 200-day SMA of A$3.77 confirms the extraordinary momentum, sitting roughly half the current price. In trending markets, the 200-day SMA acts more as a long-term anchor than a near-term support, and ELS is well above it. Near-term technical support sits around the A$6.80-A$7.00 zone, which aligns with recent consolidation. Resistance is at the 52-week high just above current levels.
RSI is likely elevated given the magnitude of the price run, suggesting short-term consolidation or pullback risk before the next leg higher. Volume patterns should be monitored — a healthy uptrend maintains above-average volume on advancing days. Given the thin analyst coverage, news-driven volatility can be sharp in either direction, creating both risk and opportunity for active traders.
Investor Insights
Elsight presents a high-risk, high-reward proposition for growth-oriented investors. The fundamental case is strong — profitable, cash-generative, and growing at an extraordinary rate — but the single-analyst coverage and premium valuation demand careful analysis.
Stop-loss discipline is important given the stock's volatility profile. A close below A$6.00 would signal meaningful technical deterioration and warrant reassessment. For longer-term investors, the drone connectivity secular growth story provides a 3-5 year thesis that justifies holding through short-term volatility.
Disclaimer: This article is for informational and educational purposes only and does not constitute financial advice or a recommendation to buy or sell any security. Investors should conduct independent due diligence and seek advice from a licensed financial adviser before making any investment decisions. Past performance is not indicative of future results. All figures sourced from publicly available market data.


 Nov 12, 2026





 Please wait processing your request...