
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Company Overview
EDU Holdings Ltd is an ASX-listed education services company operating private higher education colleges and vocational training facilities, primarily serving domestic and international students across Australia. The company operates across registered higher education provider licences and offers bachelor degrees, graduate diplomas, and vocational qualifications in business, accounting, IT, and community services disciplines.
The Australian international education market is one of the country's largest export industries and a key driver of demand for private higher education providers like EDU. The company has benefited from the recovery and growth of international student enrolments post-pandemic, as students from China, India, Nepal, the Philippines, and Southeast Asia increasingly seek Australian higher education credentials for their career development and migration pathways.
EDU's business model is highly scalable — fixed costs including campus leases and regulatory infrastructure can support significantly higher student volumes with minimal incremental cost. This creates powerful operating leverage as enrolments grow. Strategic entities hold 35.8% of shares, indicating concentrated ownership aligned with long-term growth objectives. The 97% three-year revenue CAGR reflects the company's extraordinary growth trajectory through both organic enrolment growth and strategic acquisitions of additional registered provider entities.
Fundamental Insights
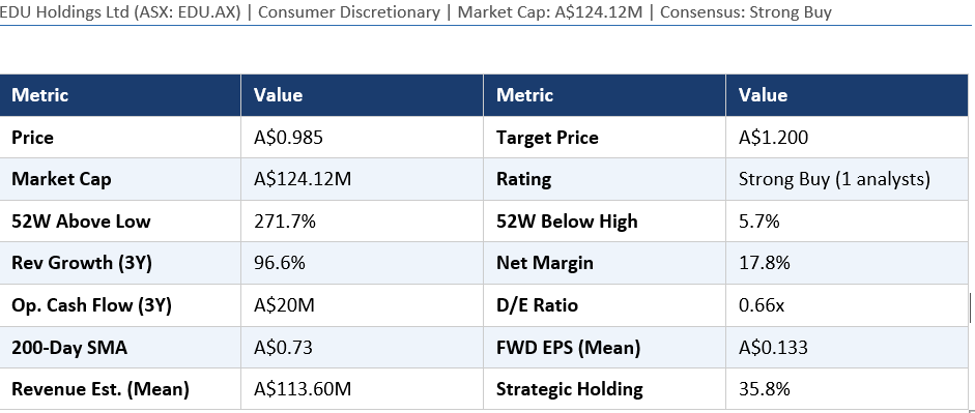
EDU Holdings' fundamentals are those of a company in explosive growth mode. Three-year average revenue growth of 96.6% reflects the combination of organic enrolment growth, acquisitions of additional education providers, and the structural recovery of international student volumes. Net profit margin of 17.8% is strong for an education services business, confirming that growth is being delivered profitably rather than at the expense of margins.
Operating cash flow of A$20 million over three years confirms the business generates meaningful real cash, supporting reinvestment in campus infrastructure and regulatory compliance. Debt-to-equity of 0.66x is moderate and appropriate for a growing services business with predictable fee income. The 200-day SMA of A$0.73 compared to the current price of A$0.985 reflects the dramatic re-rating the stock has undergone as revenue growth has materialised.
The single analyst projects EPS of A$0.133 and revenue of A$113.6 million. At a current price of A$0.985, the implied forward P/E is approximately 7.4x on EPS — a very low multiple for a company growing revenue at nearly 100% per annum. This dislocation between growth rate and valuation multiple often indicates either that the market is sceptical of sustainability or that coverage is too thin to attract institutional capital flows.
Broker Views and Analyst Consensus
EDU Holdings has a single analyst covering it with the highest possible conviction rating of Strong Buy and a target price of A$1.20, implying 21.8% upside from the current A$0.985. The Strong Buy designation is notable because it goes beyond the standard Buy recommendation, signalling the analyst believes the risk-reward skew is particularly favourable.
The core thesis includes EDU operates in a structurally growing market, is growing revenue at nearly double per year, maintains strong profitability, and trades on a forward P/E of approximately 7x — a valuation that appears inconsistent with the quality and growth profile of the business. The analyst argues that limited institutional coverage and small-cap size have kept the stock under-owned relative to its fundamental merit.
Risks include regulatory exposure around international student visa policy, which the Australian government has periodically tightened in ways that impact enrolment volumes. Competition from larger and better-resourced private and public education providers is also a consideration, and the dependence on international student enrolments creates sensitivity to global travel restrictions, geopolitical events, and source country economic conditions.
Technical Analysis
EDU Holdings has experienced one of the most dramatic price recoveries in this peer group, sitting 271.7% above its 52-week low and only 5.7% below its 52-week high. This positioning — near the top of its annual range after a massive appreciation — reflects the market's recognition of the company's fundamental re-rating story. The 200-day SMA at A$0.73 is dramatically below the current price of A$0.985, confirming the exceptional strength of the uptrend.
Near-term resistance sits at the 52-week high just above the current level. A sustained break above A$1.00 on volume would be a significant technical catalyst, as round-number levels often attract additional buying interest and media coverage for micro-cap stocks. Support sits at A$0.90 and then A$0.85. RSI is likely elevated given the magnitude of the price run, but momentum-driven stocks can remain overbought for extended periods during strong fundamentally-driven uptrends.
Investor Insights
EDU Holdings is a micro-cap education growth story with an exceptional valuation anomaly — near-100% revenue growth on a 7x forward P/E. The Strong Buy rating and 22% upside to target provide a near-term return case. The primary catalyst to watch is quarterly enrolment update releases, which will be the key driver of sentiment and analyst estimate revisions.
Disclaimer: This article is for informational and educational purposes only and does not constitute financial advice or a recommendation to buy or sell any security. Investors should conduct independent due diligence and seek advice from a licensed financial adviser before making any investment decisions. Past performance is not indicative of future results. All figures sourced from publicly available market data.


 Nov 12, 2026





 Please wait processing your request...