
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Company Overview
Develop Global Ltd is a dual-Business ASX company combining a specialist underground Mining contracting division with a portfolio of base metal mine development Assets, including the Woodlawn Zinc-Copper-Lead Project in New South Wales and the Pioneer Dome Lithium Project in Western Australia. The mining services division provides underground contract mining services to other mine operators, generating Recurring Revenue that funds the exploration and development of the company's own mineral assets.
This business model — using Cash Flow from mining services to self-fund mine development — is a Capital-efficient approach that reduces the need for Shareholder dilution through Equity raisings. Develop's underground mining services arm has developed a strong reputation for technical excellence in complex narrow-vein mining, a specialisation that commands premium rates and reduces commoditisation risk.
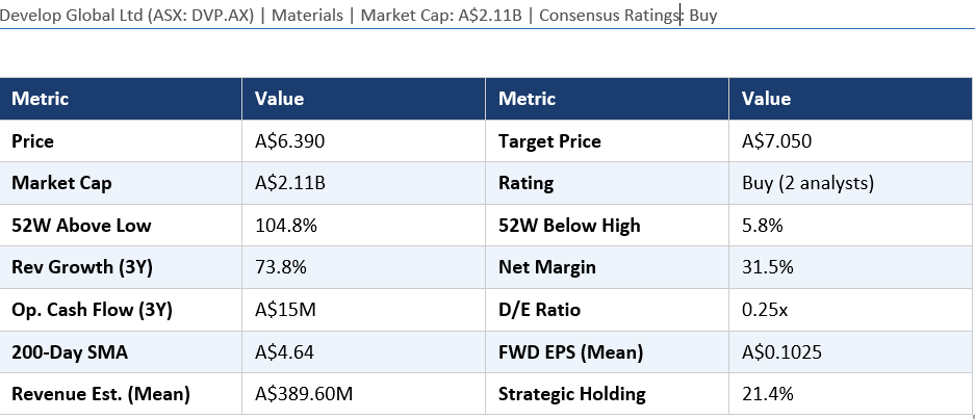
The company's mineral assets provide significant exploration upside, particularly at Woodlawn, where a historic zinc-copper-lead mine with an established processing circuit is being redeveloped. Strategic entities hold 21.4%, and the 104.8% price appreciation above the 52-week low reflects growing market recognition of the dual-asset strategy's value creation potential. Revenue growth of 73.8% over three years reflects both services contract wins and the progression of mineral asset revenues.
Fundamental Insights
Develop Global's revenue has grown at 73.8% per annum over three years, a high rate driven by services contract wins and the progression of its mineral development pipeline. Net profit Margin of 31.5% is impressive and reflects the high value-add of specialist underground mining services combined with asset development income streams.
Operating Cash Flow of A$15 million over three years is lower relative to the margin profile, suggesting significant capital reinvestment into mineral asset development during this phase. Debt-to-equity of 0.25x is manageable and appropriate given the development-stage nature of the mineral assets. The 200-day SMA at A$4.64 versus the current price of A$6.39 confirms strong price appreciation well above the medium-term average.
Two analysts provide a wide range of EPS estimates — A$0.075 to A$0.130 — reflecting genuine uncertainty around the timing of mineral asset development milestones and services contract pipeline. At current price and mean EPS of A$0.1025, the forward P/E is approximately 62x, which appears elevated but may be justified if the mineral assets are approaching development decisions that unlock significantly larger Earnings streams.
Broker Views and Analyst Consensus
Two analysts cover Develop Global, both maintaining Buy ratings with a consensus target of A$7.05, implying 10.3% upside from the current A$6.39. The uniformly positive coverage reflects confidence in both the mining services earnings base and the optionality of the mineral development pipeline.
Brokers focus on the strategic logic of the dual-business model: the contracting arm funds development without equity dilution, and the mineral assets provide a growth option that could re-rate the stock materially if development decisions are positive. The Woodlawn Zinc-Copper-Lead project is of particular interest given the current shortage of zinc and copper Supply globally.
Risks include the lumpy nature of mining services contract wins, execution risk in transitioning from services company to mine developer-operator, and the wide dispersion in earnings estimates highlighting genuine uncertainty about the mineral development timeline.
Technical Analysis
Develop Global has risen 104.8% above its 52-week low and sits only 5.8% below its 52-week high — near the top of its annual range with strong momentum. The 200-day SMA at A$4.64 is well below the current A$6.39, confirming the entrenched uptrend. The stock is approaching its 52-week high, which will be the next technical resistance test.
A break above the 52-week high on Volume would signal a continuation of the uptrend toward and potentially beyond the broker target of A$7.05. Support sits at A$6.00 (recent consolidation) and A$5.50 below that. The wide EPS estimate range means news flow around contract wins and development milestones will be high-impact events for the stock price.
Investor Insights
Develop Global is a dual-exposure Investment combining mining services income with mineral development optionality. At 10.3% upside to broker target and Buy ratings, the near-term return case is modest but the medium-term upside from positive mineral development decisions could be substantial. Investors should watch for any pullback toward A$6.00 for improved risk-reward. Watch for contract win announcements and Woodlawn development updates as key catalysts. Stop-loss below A$5.50 defines the technical risk parameter.


 Nov 12, 2026





 Please wait processing your request...