
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
- Deterra Royalties continues to showcase the immense power of its ultra-high-Margin, asset-light Business model, delivering exceptionally resilient cash flows despite a highly volatile bulk commodities backdrop.
- As institutional Capital seeks refuge from severe Capital Expenditure Inflation, DRR’s low-overhead Royalty structure is acting as a premier defensive magnet for income-focused portfolios.
- The technical price action is exceptionally bullish, characterized by a forceful structural breakout on elevated Volume that has decisively shattered the neckline of a pristine, multi-month Inverse Head & Shoulders base.
While Deterra Royalties Limited (ASX:DRR) navigated a grueling, multi-month consolidation phase driven by fluctuating iron ore spot prices and broader Commodity sector rotations, the underlying market structure has just undergone a definitive bullish Reversal. As the broader market begins to aggressively penalize capital-intensive producers facing escalating operating costs, Deterra’s pure-play royalty model is being heavily re-rated. The recent surge in buying pressure suggests that the extensive accumulation and base-building phase has thoroughly exhausted, paving the way for a dynamic new cyclical mark-up phase.
Asset-Light Cash Generation and Growth Diversification
DRR’s fundamental Investment thesis is anchored to its unrivaled operating margins and a highly insulated corporate structure:
- The MAC Cash Engine: Deterra’s foundation remains the world-class Mining Area C (MAC) iron ore royalty operated by BHP. Despite a softer iron ore pricing environment in the March 2026 quarter, MAC delivered A$56.6 million in royalty Revenue, supported by record production of 39.5 million wet metric tonnes. Because DRR bears 0% of the operational costs, extraction inflation, or capital expenditures, this revenue flows almost entirely to the Bottom Line, preserving an EBITDA margin that historically exceeds 90%.
- Fortress Balance Sheet and Payouts: Following a highly profitable first half of the 2026 fiscal year, which delivered a record NPAT of A$87.2 million (up 36% year-on-year), Deterra rewarded shareholders with a surging, fully franked 12.4 cent Interim Dividend. Supported by the divestment of non-core precious metals Assets for ~A$124 million, the company has drastically deleveraged, leaving over A$340 million in undrawn Debt capacity to target future value-accretive royalties.
- The Lithium Horizon: Beyond iron ore, DRR holds a massive 4.8% gross revenue royalty over Lithium Americas’ flagship Thacker Pass project in Nevada. With construction advancing at full pace and backed by a massive US$2.23 billion U.S. Department of Energy Loan, Thacker Pass remains on track for first production by late 2027, promising a highly lucrative secondary cash-flow engine for the group.
Associated Risks
A primary risk for Deterra Royalties remains its severe, near-term concentration risk. With over 95% of current revenues derived solely from BHP’s Mining Area C, any localized operational disruptions, transport bottlenecks, or a severe, prolonged collapse in global seaborne iron ore prices would directly impact group Earnings and dividend distributions. Furthermore, while the long-term pipeline is highly attractive, earlier-stage royalty projects face ongoing development, funding, and permitting risks, meaning that meaningful cash-flow diversification away from MAC is still several years from fully materializing.
Technical Outlook
The Daily Chart for Deterra Royalties provides a textbook masterclass in structural exhaustion and breakout mechanics, highlighting a sudden, violent transition from a prolonged accumulation phase into a fresh momentum phase.
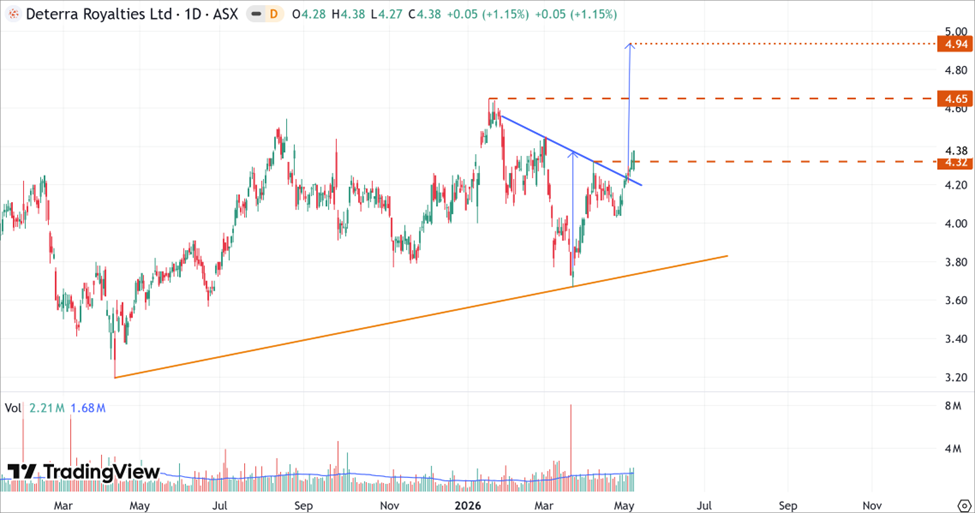
DRR’s Daily Price Chart (at the closing price of 08th May 2026). Powered by: tradingview.com
- On the daily chart, DRR’s stock price has completed an Inverse Head & Shoulders pattern. This classic bullish reversal formation visually demonstrates a gradual contraction of the prior consolidation phase and a complete transfer of power from exhausted sellers back to aggressive institutional accumulators.
- With the confirmation of a decisive structural breakout above the pattern’s $4.32 neckline, the path of least resistance points directly North. Ultimately, the pattern's full measured move projects a structural target at $4.94, though temporary pauses or pullbacks may emerge near the significant resistance established by the January 2026 peak at $4.65.
Bottom Line
Deterra Royalties (ASX:DRR) presents an exceptional convergence of fundamental cash-flow resilience and pristine, high-momentum technical execution. The forceful resolution of the localized Inverse Head & Shoulders pattern suggests that the path of least resistance is heavily skewed to the upside. Active investors should closely monitor the newly established $4.32 breakout floor; a confirmed structural defense of this zone could definitively validate the accumulation cycle and favor a dynamic advance toward the ultimate $4.94 measured move objective.


 Nov 12, 2026





 Please wait processing your request...