
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Company Overview
Deterra Royalties Ltd is Australia's only dedicated pure-play Royalty company listed on the ASX, operating a portfolio of Mining royalties primarily tied to BHP's Mining Area C (MAC) iron ore operations in the Pilbara region of Western Australia. The company receives royalty payments proportional to iron ore production volumes and prices at MAC, providing highly predictable, Capital-light cash flows with no direct operational risk. Deterra was demerged from Iluka Resources in 2020 and has since established itself as a unique income vehicle, combining Commodity exposure with royalty-company Economics. The company is also actively diversifying its royalty portfolio beyond iron ore.
Fundamental Insights
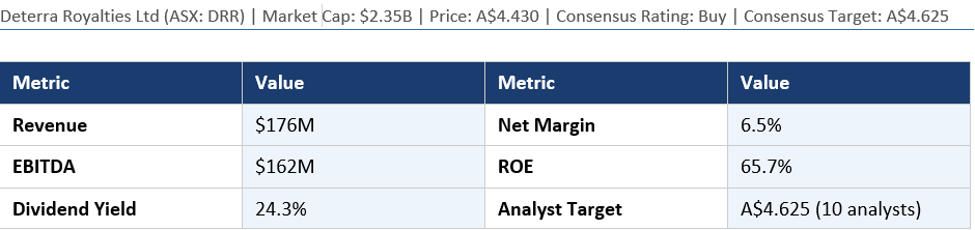
Deterra's financials are quintessentially royalty-company in nature: very high gross margins, exceptional ROE, and minimal Capital Expenditure. The 64.6% gross Margin and ROE of 65.7% reflect the zero-capex, zero-operational-risk royalty model. Revenue grew 28.2% to $176 million, with EBITDA rising 14.3% to $162 million - confirming the high Operating Leverage. The net margin of 6.5% may reflect Amortisation charges on royalty Assets rather than Cash Flow weakness. Dividend Yield of 24.3% is among the highest in the peer group, underpinned by the company's policy of paying out substantially all distributable Earnings. Revenue growth of 16.5% adjusted signals continued iron ore Volume expansion at MAC.
Broker Views and Analyst Consensus
Ten analysts cover Deterra with a consensus Buy rating and a target of $4.625, implying 4.4% upside from the current $4.43. The modest price gap reflects near-consensus valuation but strong conviction in the income thesis. Analysts are constructive on iron ore Demand from India's steel industry as a structural alternative to China-driven demand. The company's expansion into gold and copper royalties is viewed as a value-additive Diversification strategy. Risks include iron ore price corrections and BHP production decisions at MAC.
Technical Analysis
DRR at $4.43 is approaching the broker target of $4.625 from below, suggesting limited price upside in the near term. The 20.9% historical price gain reflects recovery momentum. Key support is at $4.10-$4.20, and resistance at $4.70 would need to fall for a fresh leg higher. RSI is in a neutral zone. The income story dominates the Investment case, making Deterra more a dividend accumulation play than a capital growth trade at current prices.
Investor Action Points
Deterra Royalties is the ideal core holding for income-focused investors seeking commodity exposure without operational risk. The 24.3% dividend yield is exceptional by any measure and is backed by genuine cash flow generation rather than capital returns. Investors should accumulate on weakness toward the $4.10-$4.20 support zone. Deterra's royalty model means it performs better in high-iron-ore-price environments, making it a natural hedge within a diversified resources portfolio.
Disclaimer: This article is for informational purposes only and does not constitute financial advice. Investors should conduct their own Due Diligence and consult a licensed financial adviser before making investment decisions. Past performance is not indicative of future results.


 Nov 12, 2026





 Please wait processing your request...