
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
- Underlying net profit after tax rose by 12.5% to $676 million.
- 8% hike in the fully-franked interim dividend to 41 cents per share.
- Coles is currently defending an ACCC Federal Court case regarding alleged misleading promotional pricing practices.
- The segment remains a significant drag on results, with EBIT plunging 37.3% due to decreased consumer demand.
Given the tug-of-war between strong fundamental growth in supermarkets and significant regulatory headwinds, we will examine the ASX:COL short-term trend from a technical perspective.
Automation-Driven Profit Growth and Dividend Strength
- Coles Group Limited (ASX:COL) remains a dominant force in the Australian retail landscape, recently demonstrating strong operational resilience in its 1H26 results for the 27 weeks ending January 4, 2026.
- The company reported a 2.5% increase in group sales revenue to $23.62 billion, with underlying NPAT rising 12.5% to $676 million, primarily fueled by a robust 14.6% surge in Supermarkets This growth was supported by a 27% jump in eCommerce sales and significant efficiency gains from its "Simplify and Save" automation programs, which delivered $133 million in savings.
- Financially, Coles maintains a solid shareholder return profile, increasing its fully franked interim dividend by 10.8% to 41 cents per share, although headline profits were tempered by a $165 million after-tax provision for historical staff underpayments.
Associated Risks and Challenges
- Despite its strong underlying performance, Coles Group (ASX:COL) faces significant headwinds, most notably from intensifying regulatory and legal scrutiny. The company is currently defending a major ACCC Federal Court case initiated in February 2026 regarding alleged misleading promotional pricing, while also navigating new legislation that outlaws "excessive pricing" for large retailers starting July 2026.
- Furthermore, headline profits remain under pressure from substantial provisions for historical staff underpayments, and the Liquor division continues to struggle with declining revenue and earnings. These factors, combined with a sharp market reaction to rival profit beats and ongoing inflationary input costs, create a volatile environment that could dampen investor sentiment in the short term.
Technical Outlook
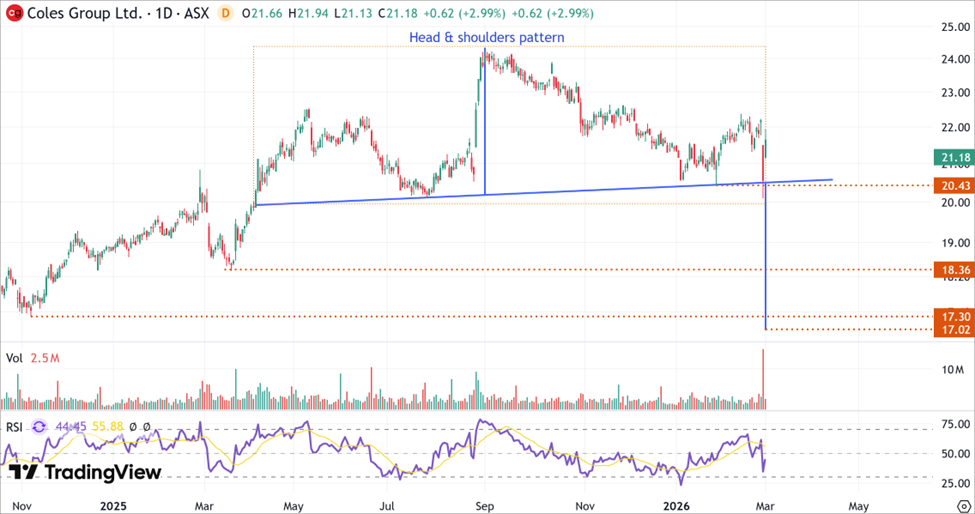
COL’s Daily Price Chart (at the market price of 02nd March 2026). Powered by: tradingview.com
- On the daily chart, COL’s stock price is forming a Head and Shoulders pattern; however, this pattern is not yet complete.
- The immediate support is placed at the pattern’s neckline of $20.43. A decisive break below this support would indicate a negative bias and push the stock price lower.
- The pattern’s projected target is $17.02, which serves as the price objective in this case, although buying pressure may emerge near two significant support levels at $18.36 and $17.30, formed by previous troughs.
Bottom Line
Coles Group (ASX:COL) is currently a study in contrast, boasting robust 12.5% underlying profit growth and a double-digit dividend increase driven by high-tech automation and a booming eCommerce sector. However, this fundamental strength is being overshadowed by a high-stakes ACCC Federal Court case and a struggling Liquor division. From a technical standpoint, the stock is at a critical juncture; while the business is performing well, the formation of a Head and Shoulders pattern suggests that a decisive breach of the $20.43 neckline could override the positive earnings narrative and trigger a move toward the $17.02 price objective.


 Nov 12, 2026





 Please wait processing your request...