
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Company Overview
Cobram Estate Olives Ltd is Australia's largest producer of extra virgin olive oil and one of the most recognised premium olive oil brands in the world. The company operates vast olive groves across Victoria and New South Wales in Australia, as well as in California in the United States, giving it a geographically diversified production base that spans both the Northern and Southern Hemispheres. This dual-hemisphere production is a significant competitive advantage, allowing Cobram to supply fresh-harvest extra virgin olive oil year-round.
Cobram Estate has built a premium consumer brand that commands pricing power in both Australian and US retail channels, with products stocked in major supermarket chains including Woolworths, Coles, Costco, and Whole Foods. The brand's credibility is underpinned by rigorous quality standards, harvest-date labelling, and a series of international olive oil competition medals that validate its premium positioning.
The company's business model benefits from structural tailwinds as health-conscious consumers globally shift consumption toward extra virgin olive oil, driven by its well-documented cardiovascular and anti-inflammatory health properties. At the same time, European olive oil production has faced significant supply disruptions from drought and disease, creating market share opportunities for Cobram as a reliable alternative supplier. Strategic entities hold 27.9% of the company, reflecting strong founder and institutional alignment.
Fundamental Insights
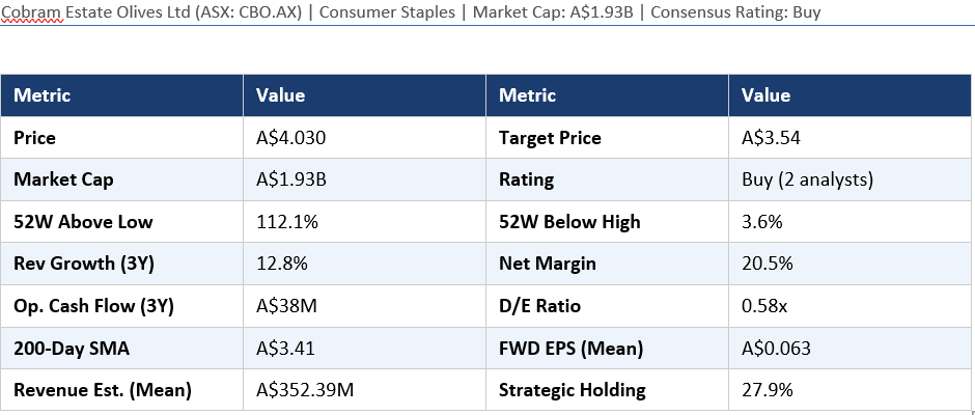
Cobram Estate's financial profile reflects a high-quality consumer branded goods business. Revenue growth of 12.8% over three years is solid and consistent for a food producer, reflecting both volume and price growth. Net profit margin of 20.5% is strong for an agricultural business, demonstrating the value of brand premium and operational efficiency across large-scale grove management.
Operating cash flow of A$38 million over three years confirms robust cash generation, supporting the dividend and providing capital for grove expansion and brand investment. The debt-to-equity ratio of 0.58x is moderate and appropriate for an asset-intensive agricultural business with significant land and tree assets. The 200-day SMA of A$3.41 is well below the current price of A$4.03, confirming the uptrend that has been in place over the medium term.
Forward EPS estimates range from A$0.046 to A$0.080, with a mean of A$0.063, and revenue is projected to reach A$352 million. At a current price of A$4.03, the implied forward P/E is approximately 64x on mean EPS — a premium multiple that reflects the company's brand quality, growth runway, and the scarcity of high-quality food and beverage assets on the ASX. The wide EPS estimate range highlights the earnings sensitivity to olive oil yields and pricing, both of which can vary significantly between harvests.
Broker Views and Analyst Consensus
Two analysts cover Cobram Estate and both maintain Buy ratings, demonstrating consistent conviction in the investment thesis. The consensus target price of A$3.54, however, sits below the current price of A$4.03, suggesting the market has traded ahead of broker fundamental valuations. This is not uncommon for high-quality consumer brands where the market assigns a scarcity premium above near-term earnings-based targets.
The broker Buy thesis centres on Cobram's durable competitive advantages: brand equity, geographical production diversification, the health megatrend behind olive oil consumption, and the structural supply gap created by European production disruptions. The US California groves provide a locally-produced narrative increasingly valued by American consumers who prefer domestically-grown products.
Key risks include olive harvest variability due to weather events, Australian dollar strength reducing competitiveness in export markets, and competition from both European producers recovering from supply disruptions and lower-cost private label alternatives. The premium valuation also means the stock is sensitive to any earnings miss relative to market expectations.
Technical Analysis
Cobram Estate sits 112.1% above its 52-week low and only 3.6% below its 52-week high, positioning it at the top of its annual range. The stock's trajectory has been strongly positive, with the 200-day SMA at A$3.41 sitting well below the current A$4.03 price, confirming a sustained uptrend. The current price is above the broker consensus target of A$3.54, a scenario that often leads to near-term price consolidation.
Near-term support sits at A$3.75-A$3.85, which represents a potential pullback zone to the recent breakout level. Resistance is thin given the proximity to the 52-week high, and a new all-time high above current levels would be technically bullish. RSI is likely in elevated territory given the proximity to 52-week highs, suggesting caution for new buyers at current levels. Volume behaviour should be monitored — heavy selling volume on down days would signal distribution rather than healthy consolidation.
Investor Insights
Cobram Estate is a high-quality consumer staples holding for long-term investors seeking branded food exposure with global growth potential. The stock's current price above broker consensus target of A$3.54 suggests limited near-term upside on fundamental grounds, making immediate new entries less attractive on a risk-reward basis. Investors should watch for a pullback toward the A$3.75-A$3.85 zone for a better-risk-adjusted potential.
For existing holders, the quality of the business and the structural olive oil demand story support a hold through near-term volatility. The modest EPS yield at current prices means income investors should factor in the total return picture including dividend growth rather than yield alone. A 3-5 year investment horizon allows the US grove expansion and brand investment thesis to fully play out.
Disclaimer: This article is for informational and educational purposes only and does not constitute financial advice or a recommendation to buy or sell any security. Investors should conduct independent due diligence and seek advice from a licensed financial adviser before making any investment decisions. Past performance is not indicative of future results. All figures sourced from publicly available market data.


 Nov 12, 2026





 Please wait processing your request...