
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Company Overview
Clover Corporation Ltd is a specialist Australian food ingredients company that produces and supplies microencapsulated omega-3 oils, particularly DHA (docosahexaenoic acid), for use in infant formula, medical nutrition, and functional food products. DHA is an essential long-chain polyunsaturated fatty acid critical for infant brain and eye development, and Clover's proprietary microencapsulation technology protects delicate omega-3 oils from oxidation during processing and storage — a key commercial differentiator.
The company's primary customers are infant formula manufacturers in Australia, China, Southeast Asia, and the Middle East, where regulatory requirements increasingly mandate DHA inclusion in formulated products. Clover's production facility is based in New South Wales, and the company has developed strong relationships with major formula companies over decades of operation.
The infant formula ingredient market benefits from structural growth drivers including rising birth rates in developing markets, increasing adoption of premium formulated nutrition products, and regulatory tailwinds favouring enhanced nutritional ingredients. Clover also supplies to the growing medical nutrition sector serving clinical patients requiring specialised dietary support, providing diversification from infant formula concentration risk. The near-debt-free balance sheet provides comfort and strategic flexibility.
Fundamental Insights
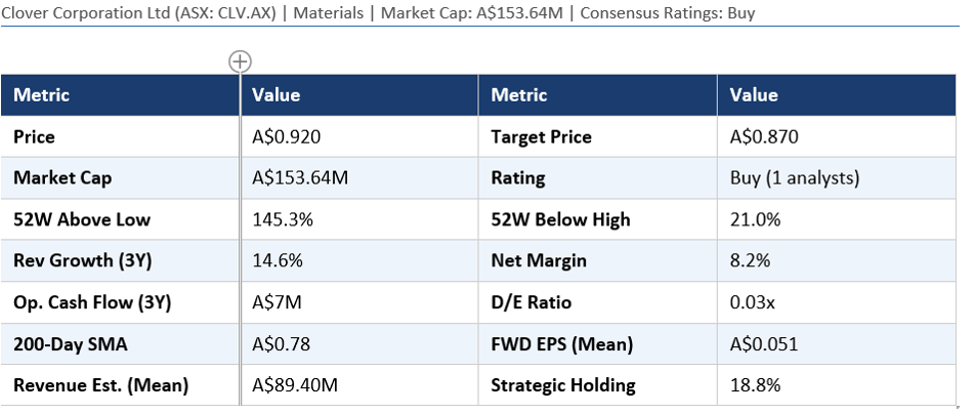
Clover Corporation's fundamentals reflect a specialist ingredient supplier with steady but moderate growth. Revenue has grown at 14.6% per annum over three years, driven by volume growth in core DHA supply contracts and margin improvement from production efficiency. Net profit margin of 8.2% is in line with specialty ingredients businesses and reflects the cost structure of nutrient extraction and microencapsulation operations.
Operating cash flow of A$7 million over three years confirms consistent cash generation, and the essentially debt-free balance sheet (D/E of 0.03x) gives Clover exceptional financial resilience and capital allocation flexibility. The 200-day SMA of A$0.78 versus the current price of A$0.92 confirms a positive medium-term trend, and the 145% gain above the 52-week low reflects a significant re-rating of the company's prospects.
The single analyst covering Clover projects EPS of A$0.051 and revenue of A$89.4 million with no dispersion in estimates, reflecting consensus on near-term trajectory. At a current price of A$0.92, the forward P/E is approximately 18x, a reasonable multiple for a specialty ingredients business with monopoly-like positioning in microencapsulated omega-3 supply for Australian infant formula manufacturers. The 21% discount from the 52-week high suggests the stock has pulled back from its recent peak.
Broker Views and Analyst Consensus
One analyst covers Clover Corporation with a Buy rating and a target price of A$0.87, which sits below the current price of A$0.92. This creates the unusual situation where the analyst is bullish on the business fundamentals but the market has outrun the formal valuation model. This often occurs when positive momentum and newsflow drive prices above model-based targets temporarily.
The Buy thesis rests on Clover's dominant positioning as a specialist supplier of microencapsulated DHA to infant formula manufacturers, the regulatory-mandated inclusion of DHA in formula products across key Asian markets, and the company's clean balance sheet that enables distribution of surplus capital to shareholders. The brand equity with major formula manufacturers after decades of supply relationships creates high switching costs and revenue stickiness.
Risks include the heavily concentrated customer base in infant formula manufacturers, exposure to Chinese birth rate trends that drive formula demand, and competition from global omega-3 suppliers including DSM-Firmenich and Lonza. The single analyst coverage creates information inefficiency risk — positive or negative company news can move the stock sharply without pre-existing market preparation.
Technical Analysis
Clover Corporation has been one of the stronger performers in its peer group, sitting 145.3% above its 52-week low — a dramatic recovery from what appears to have been severely depressed price levels. However, the stock now sits 21% below its 52-week high and below the analyst target, suggesting it has given back some recent gains.
The 200-day SMA at A$0.78 is well below current levels, providing solid medium-term support. The immediate technical picture shows the stock consolidating after a strong run, with support at A$0.85-A$0.87 (which aligns with the broker target and acts as a fundamental floor) and resistance at the 52-week high above A$1.00. RSI has likely normalised from overbought levels reached at the 52-week peak. A sustained hold above A$0.87 and subsequent break above A$1.00 would be bullish for the next leg higher.
Investor Insights
Clover Corporation is a niche quality compounder with a virtually debt-free balance sheet and a defensible market position. The current price above the analyst target warrants patience — investors should target entry points at or below A$0.87 to align with broker valuation and improve the risk-reward equation. A pullback toward the A$0.85 zone would represent an entry with the A$0.92+ price as near-term target and further upside if the analyst revises their model higher. Investors focused on specialty food ingredients and the infant nutrition secular trend should maintain in their watchlist.
Disclaimer: This article is for informational and educational purposes only and does not constitute financial advice or a recommendation to buy or sell any security. Investors should conduct independent due diligence and seek advice from a licensed financial adviser before making any investment decisions. Past performance is not indicative of future results. All figures sourced from publicly available market data.


 Nov 12, 2026





 Please wait processing your request...