
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Company Overview
Centuria Capital Group is one of Australia's largest listed real estate fund managers, overseeing a diversified portfolio of office, industrial, and healthcare property funds. The group manages Assets across its listed and unlisted platforms, including Centuria Industrial REIT and Centuria Office REIT, creating a fee-driven Earnings model that complements its Balance Sheet co-investments. Centuria's healthcare property exposure has been a notable growth differentiator, reflecting increasing institutional appetite for social infrastructure assets. The company has grown assets under management significantly over the past five years through acquisitions and organic growth.
Fundamental Insights
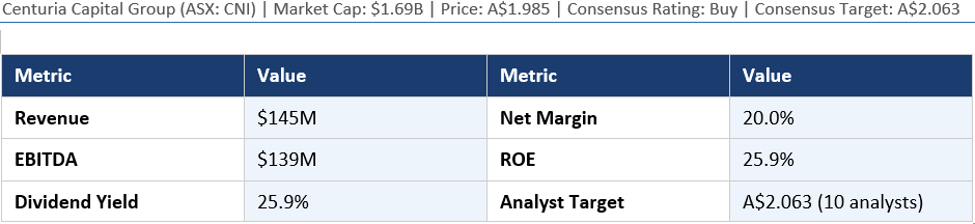
Centuria Capital's Revenue of $145 million reflects a 43.7% annual increase, driven by AUM growth across its diversified fund platforms. EBITDA rose 13.7% to $139 million, generating a very high EBITDA-to-revenue ratio that reflects the Fund Manager's earnings quality. Net Margin of 20.0% and ROE of 25.9% are strong for the real estate sector. The Dividend Yield of 25.9% stands out as one of the most compelling income metrics in this analysis, though investors should assess the sustainability of this level against distributable earnings. Revenue growth of 5.0% on an adjusted basis signals steady organic AUM expansion. EBITDA margin of 6.1% on an adjusted basis may reflect management fee compression or higher distribution costs.
Broker Views and Analyst Consensus
Ten analysts back Centuria with a Buy rating and a consensus target of $2.063, implying just 4% upside from the current price of $1.985. The narrow gap to target price reflects the market's near-consensus with broker valuation. Key bullish arguments include the healthcare property megatrend, industrial REIT Demand from E-commerce logistics, and management's ability to source off-market deals. A 59% historical price appreciation highlights the recovery already underway from prior lows. Risks include rising interest rates compressing property cap rates and Redemption pressure in unlisted funds.
Technical Analysis
CNI at $1.985 is approaching the consensus target of $2.063, leaving limited near-term upside on price terms alone. However, the stock has been in a constructive recovery from its 52-week lows. Key support is at $1.85, and a move above $2.10 would signal a fresh technical breakout. With RSI in the mid-range, the stock is not technically overbought. Volume trends suggest steady accumulation by income-focused investors. A consolidation around $1.95-$2.00 would create a tighter base for the next leg higher.
Investor Action Points
Centuria Capital is an income investor's primary consideration given the exceptional dividend yield. Investors should verify the sustainability of distributions by reviewing per-unit distributable income rather than headline accounting profits. At current prices, the entry point is close to Fair Value based on broker estimates, making it more a hold than a strong buy for new money. However, the 25.9% yield provides substantial cushioning against capital risk. Reinvesting distributions accelerates compound returns significantly over a 5-year horizon.
Disclaimer: This article is for informational purposes only and does not constitute financial advice. Investors should conduct their own Due Diligence and consult a licensed financial adviser before making Investment decisions. Past performance is not indicative of future results.


 Nov 12, 2026





 Please wait processing your request...