
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Highlights
- Liontown Resources reported its strongest financial quarter since production began, generating $33 million in positive net Cash Flow.
- Institutional broker Bell Potter Securities issued a Buy rating with a price target of A$2.56, following sustained operational and financial improvement.
- The company ended the quarter with A$424 million cash, transitioning to a net cash position after major Liability reduction linked to LG Energy Solution convertible note conversion.
Shares of Liontown Resources Limited (ASX:LTR) traded at A$2.35 on 18 May 2026, remaining broadly flat on the day despite a strong backdrop of operational and financial momentum reported in its latest quarterly activities update. Over the past 12 months, the stock has appreciated by more than 245%, reflecting a broader cyclical recovery in lithium markets alongside the company’s transition into production at its Kathleen Valley operation.
Trading sentiment might be influenced by increasing institutional attention following Bell Potter Securities’ initiation of coverage with a Buy rating and a A$2.56 price target. While broker research often contributes to sentiment momentum in mid-cap resource equities, the broader market reaction indicated a more measured reassessment rather than speculative repricing.
Operational Performance and Production Transition
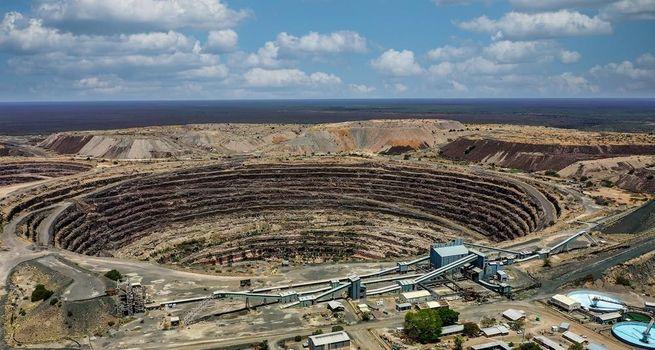
The Quarterly Report highlighted a significant milestone for Liontown Resources Limited, with its Kathleen Valley operation running as a fully underground mine for the first time over a complete quarter. The company achieved a 1.5 million tonnes per annum annualised underground run-rate ahead of schedule, marking a key step in its transition from ramp-up to steady-state production.
Production data showed 96 thousand dry metric tonnes of spodumene concentrate output, with 84 thousand tonnes sold across five shipments. Average grade was reported at 5.1% Li₂O, reflecting consistent product quality in line with market specifications. Processing performance remained stable, though recoveries fluctuated during the quarter due to a temporary reliance on stockpiled open-pit material.
A notable operational improvement emerged toward the end of the period, as underground ore feed increased to 67% of plant input in early April. This shift contributed to improved lithia recovery rates, which reached the company’s 70% target as underground material became dominant in the processing mix. The transition is significant in the context of underground Mining Economics, where ore consistency and grade control typically influence long-term operational efficiency.
Financial Performance and Cash Flow Strength
The March quarter represented a pivotal financial milestone for Liontown Resources Limited, recording its first-ever positive net cash flow since production commenced. Operating cash inflow reached A$55 million, supported by Revenue of A$197 million generated from spodumene concentrate sales.
Net cash flow for the period stood at A$33 million after accounting for investing and financing activities. The result was underpinned by strong realised pricing, with spodumene concentrate achieving an average realised price of US$1,845 per dry metric tonne SC6e. This pricing environment provided meaningful support to revenue generation despite ongoing cost pressures associated with underground development.
The company closed the quarter with A$424 million in cash and 26,270 tonnes of saleable inventory, indicating strong Liquidity heading into the next reporting period. Importantly, operational cash generation was partially offset by A$26 million in investing outflows, largely directed toward underground mine development and sustaining infrastructure.
A key structural change during the quarter was the conversion of US$250 million in convertible notes by LG Energy Solution, eliminating approximately A$482 million in liabilities. This transaction simplified the Capital Structure and moved the company into a net cash position of A$61 million at quarter-end, significantly altering its Balance Sheet profile.
Strategic Positioning and Expansion Outlook
Beyond near-term production metrics, the quarterly update outlined early-stage work on the expansion of Kathleen Valley, originally detailed in the 2021 definitive feasibility study. Liontown Resources Limited has commenced early works and procurement activities ahead of a formal final Investment decision expected in FY2027.
Key initiatives include procurement of a 5.5MW ball mill, underground development works at the Northwest Flats ore body, and construction of a permanent mine services area. These investments signal a staged expansion approach aimed at increasing throughput and improving plant efficiency over time.
The capital commitment for early works has been estimated between A$15 million and A$18 million for FY2026, with broader pre-FID expenditure potentially reaching up to A$77 million. The staged nature of the expansion strategy reflects a measured approach to capacity growth, balancing operational scaling with financial discipline in a cyclical Commodity environment.
Institutional Views and Broker Sentiment
The release of Bell Potter Securities’ Buy rating added an additional layer of market attention to Liontown Resources Limited. The broker’s A$2.56 target reflects a constructive view of the company’s operational trajectory, particularly its transition toward steady underground production and improving cash generation.
Capital Structure and Balance Sheet Evolution
The quarter marked a structural transformation in the financial profile of Liontown Resources Limited. The conversion of LG Energy Solution’s convertible notes eliminated a significant liability burden and materially simplified the capital structure.
Following the conversion, the company retains limited borrowings, including a Ford Facility and a Western Australian State Government Loan under the Lithium Industry Support Program. The reduction in Leverage has improved financial flexibility at a critical stage of operational ramp-up, particularly as the company prepares for expansion-related capital deployment.
Cash reserves of A$424 million provide a buffer against commodity price Volatility and ongoing development requirements. The presence of substantial inventory also reflects a transitional production phase where shipment timing and market conditions can influence short-term cash flow dynamics.
Conclusion
The latest quarterly update from Liontown Resources Limited reflects a period of significant operational maturation, financial strengthening, and strategic progression. The combination of record cash flow generation, improved underground production performance, and a simplified balance sheet has positioned the company in a markedly different financial posture compared to earlier stages of its development.
Despite this progress, market pricing of the stock at A$2.35 suggests that investors continue to weigh strong execution against broader lithium market cyclicality and the capital requirements associated with expansion. The presence of a new institutional Buy rating with a higher price target has added further complexity to market interpretation, highlighting a divergence between near-term trading behaviour and longer-term broker expectations. The coming quarters are likely to be shaped by sustained production performance, lithium price trends, and execution of the company’s staged expansion strategy.


 Nov 12, 2026





 Please wait processing your request...