
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
- Bega Cheese is facing aggressive institutional distribution as the broader market rapidly re-evaluates the pricing power and margin resilience of domestic Consumer Staples.
- The technical price action is exceptionally bearish, characterized by a violent gap down (Falling Window) on elevated trading volume, completely fracturing a primary macro uptrend.
- With the primary structural support shattered, the stock is currently in a freefall phase, heavily favoring a continued descent toward the next critical horizontal support floors at $5.01 and $4.85.
While Bega Cheese Limited (ASX:BGA) spent the vast majority of 2024 and early 2025 in a robust primary uptrend driven by perceived defensive qualities and brand strength, the technical landscape has just undergone a brutal and definitive structural breakdown. As the broader market frantically reprices the Consumer Staples sector amid severe cost-of-living pressures, BGA has suffered a massive localized distribution event. The sudden explosion in selling pressure, highlighted by a sharp -3.16% daily decline to $5.21, suggests that institutional capital is actively abandoning the stock, paving the way for a dynamic new cyclical downtrend.
Margin Compression and Pricing Power
BGA’s fundamental investment thesis is heavily anchored to its iconic brand portfolio and its ability to navigate complex agricultural supply chains:
- Margin Squeeze: The core headwind for Bega, and the broader Consumer Staples complex, is the relentless squeeze on operating margins. The company must navigate sticky, elevated input costs—ranging from farmgate milk prices to logistics and packaging—while simultaneously facing a highly strained domestic consumer.
- Pricing Power Exhaustion: Institutional capital is likely evaluating the limits of BGA's pricing power. As household budgets tighten, the risk of consumers "trading down" to cheaper supermarket private-label alternatives increases dramatically. If Bega cannot seamlessly pass these input costs onto the consumer via the major supermarket chains, net margins will inevitably compress.
- Defensive Rotation: Traditional "safe haven" sectors are experiencing a structural liquidation. Value investors may be actively rotating out of FMCG (Fast-Moving Consumer Goods) stocks like BGA, prioritizing capital preservation as the underlying narrative shifts from "defensive reliability" to "earnings vulnerability."
Associated Risks
The primary risk for Bega Cheese remains its inherent sensitivity to agricultural commodity cycles and fierce domestic retail competition. Any unexpected spikes in global dairy commodity prices or localized weather events affecting milk supply can rapidly erode its cost base. Furthermore, the company remains highly vulnerable to aggressive promotional discounting by rival brands attempting to capture market share. Finally, a prolonged structural economic downturn could permanently alter consumer purchasing habits, heavily impacting BGA's higher-margin branded product divisions.
Technical Outlook
The daily chart for Bega Cheese provides a textbook masterclass in structural breakdown mechanics, highlighting a sudden, violent transition from a primary uptrend into a fresh, high-momentum distribution phase.
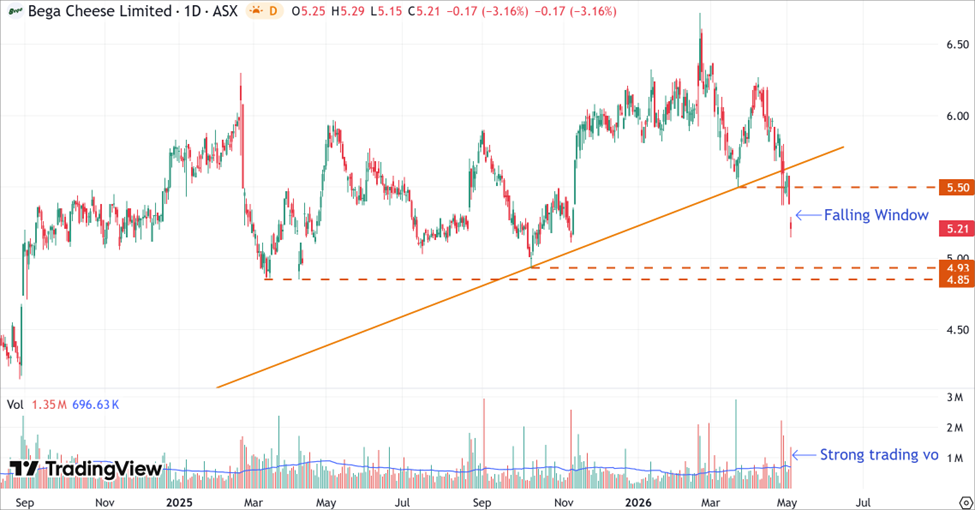
BGA’s Daily Price Chart (at the closing price of 05th May 2026). Powered by: tradingview.com
- On the daily chart, BGA’s stock price has decisively broken below a long-term ascending trendline dating back to September 2023. Executed via a bearish Falling Window on strong trading volume, this breakdown suggests a potential structural reversal of the prior uptrend.
- With the primary uptrend fractured, the initial path of least resistance points directly south. The price action is currently descending toward the first notable horizontal support zone between $4.85 and $4.93.
Bottom Line
Bega Cheese Limited (ASX:BGA) presents a highly toxic alignment of fundamental margin vulnerability and pristine, high-momentum technical breakdown. The forceful fracture of the primary ascending trendline, executed via a bearish Falling Window on massive 1.35M volume, suggests the macro path of least resistance is now firmly to the downside. Active investors should exercise extreme caution and avoid attempting to catch this falling knife. Until the stock can demonstrate genuine structural base-building, the momentum heavily favors a continued dynamic descent toward the $5.01 support zone, with further severe downside risk targeting the $4.85 macro floor.


 Nov 12, 2026





 Please wait processing your request...