
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Washington H. Soul Pattinson (ASX:SOL) is not just another stock—it’s a compounding machine hiding in plain sight. Trading at AUD 40.26, this $14–15 billion powerhouse is now flashing a rare combination: steady 300M+ earnings + breakout technical momentum.
And that’s exactly where smart money starts paying attention.
- 120+ Years of Compounding — But the Market Still Undervalues It
Founded in 1903, SOL isn’t chasing trends—it owns them across cycles.
- ~60% economic exposure to New Hope Corp (ASX: NHC) (coal cash engine)
- ~25% ownership stake in TPG Telecom (ASX: TPG) (recurring income)
- ~44% ownership stake in Brickworks (ASX:BKW) (property + materials)
This isn’t diversification for safety—it’s strategic domination across sectors.
Result: Multiple income streams = lower volatility + consistent compounding
- The Numbers Are Hard to Ignore
Let’s talk raw financial strength:
- Statutory NPAT: AUD 2,303 million (boosted by one-off gains)
- Underlying (Regular) NPAT: AUD 304 million
- Net Asset Value (NAV): AUD 13.8 billion
- Net Cash Flow from Investments (NCFI): AUD 334 million
- NAV Growth: +9.7% (1H26)
This is not a speculative story (Source: company filings).
This is real cash flow, real assets, real discipline.
- Earnings Engine: Where the Money Actually Comes From
SOL’s earnings are not concentrated but distributed across a diversified portfolio, with resources providing cyclical leverage, telecom delivering stable cash flows, and property increasingly contributing post-merger—resulting in a resilient and balanced income profile.
Impact: Cyclical upside (coal) + defensive income (telecom) = powerful balance
- Dividend Machine: 20+ Years of Growth
Here’s where it gets even more interesting:
- Dividend: ~AUD 1.00–1.10/share
- Yield: ~2.5–3.0%
- Track record: 20+ years of consecutive growth
While others cut payouts, SOL keeps compounding investor income.
- The Technical Setup Screams Momentum
Now the real catalyst: price action is aligning with fundamentals.
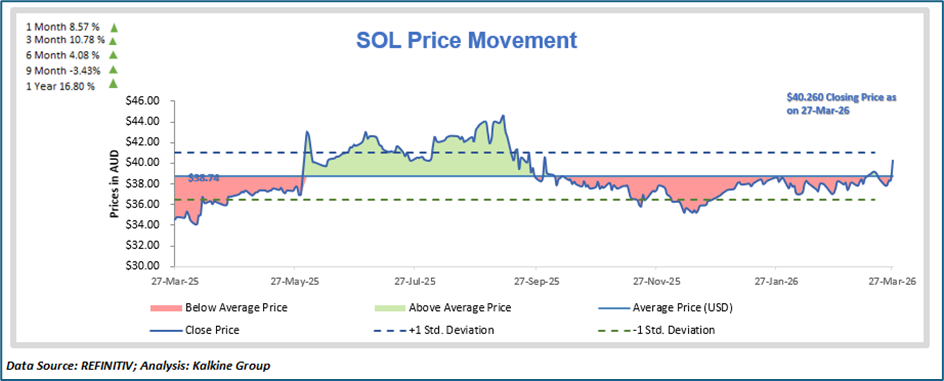
- Trading ABOVE 21-day SMA (~39.20)
- Trading ABOVE 50-day SMA (~38.50)
- RSI: 60–65 (strong, not overbought)
- Breakout above AUD 39.50–40.00 with volume
This is classic institutional accumulation behavior
- The Levels That Could Define the Next Move
- Immediate upside: AUD 41.50–42.00
- Breakout target: AUD 44.00–45.00
- Support: AUD 39.00–39.50
- Strong base: AUD 37.50–38.00
If momentum sustains, AUD 45 isn’t speculation—it’s structure of course with risks associated.
- Why This Stock Is Quietly Dangerous (In a Good Way)
Most investors overlook SOL because it’s not flashy.
But that’s exactly the opportunity.
✔ Multi-sector exposure
✔ Low debt + strong balance sheet
✔ 20+ years dividend growth
✔ Confirmed technical breakout
This is how long-term wealth stocks behave before major rerating phases
Final Take: A Silent Compounder Turning Into a Momentum Play
SOL is entering a rare phase where:
Fundamentals + Income + Technicals = Alignment
And when that happens, markets don’t move slowly—they reprice fast.
The real question is:
Will this remain a “boring compounder”… or is it about to become a breakout leader toward AUD 45+?
- Why is SOL suddenly getting investor attention?
Because fundamentals and momentum are aligning at the same time.
- NAV: AUD 13.8B
- Underlying earnings: AUD 304M (1H26)
- 9.7% portfolio return + market outperformance
This is typically when re-rating cycles begin.
- Is the AUD 2.3B profit real or misleading?
Both.
- Statutory NPAT: AUD 2.3B (headline number)
- Underlying NPAT: AUD 304M (real earnings power)
The spike is driven by one-off gains (Brickworks merger, revaluations)
Serious investors focus on the 304M base
- What actually drives SOL’s earnings?
SOL doesn’t operate businesses—it collects income from investments:
- Dividends (New Hope, TPG)
- Property & real asset income
- Trading and capital gains
Think of it as a cash-generating portfolio, not a traditional company
- Why is NCFI (AUD 334M) more important than profit?
Because cash pays dividends—not accounting profits.
- NCFI (1H26): AUD 334M (+15.4% YoY)
This is the real engine behind SOL’s 20+ years of dividend growth
- Is SOL a cyclical or defensive stock?
It’s both—and that’s the edge.
- Cyclical upside: Resources (New Hope)
- Defensive base: Telecom (TPG), property, credit
This mix creates earnings stability + upside leverage
- How strong is SOL’s balance sheet?
- NAV: AUD 13.8B
- Strong liquidity + disciplined capital allocation
Translation: Downside protection + firepower for new deals
- What is driving the recent stock momentum?
- Trading above key moving averages
- Strong RSI (60–65)
- Volume-backed breakout
This signals institutional accumulation, not retail noise
- Can SOL realistically reach AUD 45+?
Based on structure:
- Breakout zone: 39.5–40
- Next targets: 42 → 45
If momentum + fundamentals hold, AUD 45 becomes a structural move—not speculation
- What makes SOL different from other ASX stocks?
- It’s a multi-sector investment compounder
- Not dependent on one industry
- Generates income from multiple independent sources
Few ASX companies offer this level of diversification + consistency
- What are the biggest risks investors should watch?
- Coal price volatility (New Hope exposure)
- Market downturn impacting portfolio valuations
- Interest rate/macroeconomic shifts
But diversification helps absorb shocks better than single-sector stocks
- Why do long-term investors hold SOL?
Because it delivers:
- Consistent cash flows (NCFI growth)
- Dividend growth track record (decades)
- Capital compounding via NAV expansion
It’s built for long term accumulation, not short-term hype
- What is the real investment takeaway?
SOL is entering a rare phase where:
✔ Earnings stability (AUD 304M base)
✔ Cash flow strength (AUD 334M)
✔ NAV growth (AUD 13.8B)
✔ Technical breakout
When all four align, markets tend to reprice aggressively


 Nov 12, 2026





 Please wait processing your request...