
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
- Health Care Leads the Market: Health Care (XHJ) gained 1.52%, recording the strongest performance among the twelve ASX sectors.
- Consumer Staples and Financials Advance: Consumer Staples (XSJ) rose 0.61%, while Financials (XFJ) increased 0.43%.
- Seven Sectors Finish Higher: Seven of the twelve sectors recorded positive daily performances, indicating an improvement in market breadth.
- Energy and Utilities Also Gain: Energy (XEJ) rose 0.38%, while Utilities (XUJ) advanced 0.33%.
- Real Estate Remains Flat: Real Estate (XPJ) finished unchanged at 0.00%, positioning it between the advancing and declining sectors.
- Materials and Resources Weaken: Materials (XMJ) declined 0.55%, while Resources (XJR) fell 0.39%, indicating continued weakness across resource-related sectors.
- Information Technology Records the Largest Decline: Information Technology (XIJ) fell 1.14%, making it the weakest-performing sector of the session.
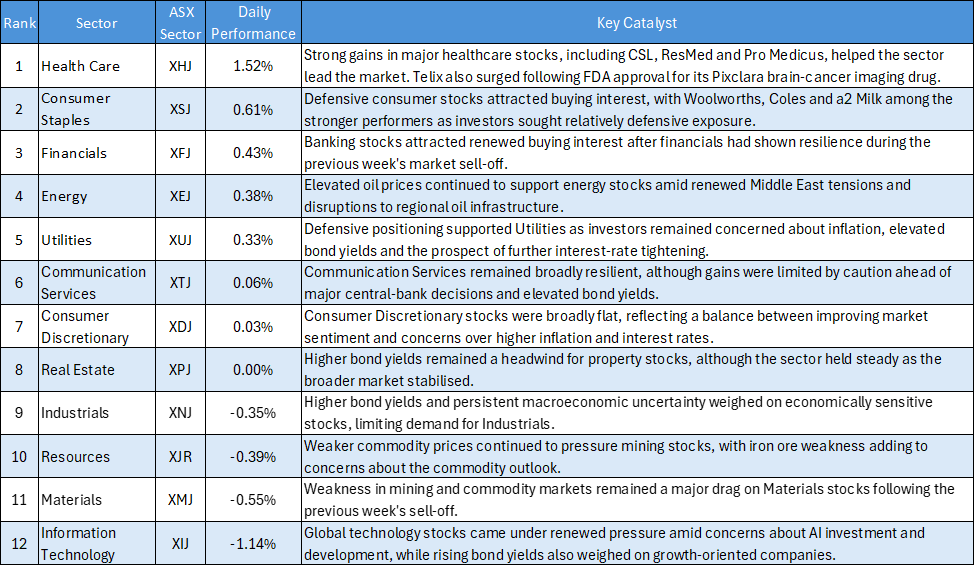
The Australian Equity market showed a clear improvement in breadth on 14 September 2026, with seven of the twelve sectors finishing higher. Health Care recorded the strongest performance with a 1.52% gain, followed by Consumer Staples at 0.61% and Financials at 0.43%. At the other end of the ranking, Information Technology declined 1.14%, while Materials and Resources fell 0.55% and 0.39%, respectively. The positive performance across a majority of sectors indicates that buying interest was relatively broad rather than concentrated in a single industry group.
Daily ASX Sector Performance Summary
Health Care Leads the Market
Health Care recorded the strongest performance on 14 September, gaining 1.52%. This placed the sector well ahead of the rest of the market and represented the clearest area of relative strength during the session.
The difference between Health Care and the weakest-performing sector, Information Technology, was 2.66 percentage points. This relatively wide performance gap highlights the significant divergence between sectors during the session.
Consumer Staples followed with a 0.61% gain, while Financials advanced 0.43%. The performance of these sectors suggests that buying interest extended beyond Health Care and was not restricted to a single industry group.
Broad-Based Market Improvement
The defining feature of the 14 September session was the improvement in market breadth. Seven of the twelve sectors recorded positive performances, while one sector was unchanged and four sectors declined.
This represents a substantially more balanced market structure than a session dominated by widespread selling. The positive performance of Health Care, Consumer Staples, Financials, Energy and Utilities indicates that several major areas of the market attracted buying interest.
Communication Services and Consumer Discretionary also finished marginally higher, although their gains of 0.06% and 0.03%, respectively, were limited. Real Estate was unchanged, leaving the sector positioned between the advancing and declining groups.
The presence of seven advancing sectors indicates that market participation was relatively broad. However, the sizeable decline in Information Technology prevented the overall performance from being uniformly positive.
Defensive Sectors Show Strength
Health Care and Consumer Staples occupied the first and second positions in the daily sector ranking, gaining 1.52% and 0.61%, respectively.
The strength in these two sectors was notable because both are generally regarded as more defensive areas of the equity market. Utilities also advanced 0.33%, further contributing to the relatively strong performance of defensive-oriented sectors.
The combined performance suggests that investors were willing to add exposure to areas that can provide comparatively stable Earnings characteristics. However, the data alone does not establish the specific reason for this sector preference.
Financials and Energy Advance
Financials gained 0.43%, placing the sector third in the daily ranking. The positive performance is important because Financials represent a major component of the Australian equity market and can have a meaningful influence on broader market direction.
Energy also finished higher, gaining 0.38%. The sector remained among the stronger performers despite continued weakness in some resource-related areas.
Utilities followed closely with a 0.33% gain. Together, Financials, Energy and Utilities provided additional breadth to the market advance, reducing the concentration of gains in Health Care and Consumer Staples.
Resource-Related Sectors Remain Under Pressure
Resources declined 0.39%, while Materials fell 0.55%. Both sectors remained in negative territory despite the broader improvement in market breadth.
Materials ranked eleventh, while Resources ranked tenth among the twelve sectors. Their weaker performance indicates that resource-related stocks continued to lag several other areas of the Australian equity market.
The divergence between Energy and the broader resource-related sectors is also notable. While Energy gained 0.38%, Resources and Materials declined 0.39% and 0.55%, respectively. This indicates that sector performance was not uniform across commodity-related industries.
Technology Records the Largest Decline
Information Technology recorded the weakest performance of the session, falling 1.14%.
The sector was the only group to decline by more than 1%, placing it significantly behind the strongest-performing sectors. Its 1.14% decline was 2.66 percentage points below Health Care, which led the market with a 1.52% gain.
The weakness in Information Technology stands out because most other sectors either advanced or experienced relatively moderate declines. The sector therefore represented the clearest area of selling pressure during the session.
Industrials also declined, falling 0.35%, but its loss was considerably smaller than that of Information Technology. The relatively limited decline suggests that weakness was more concentrated in selected sectors rather than uniformly distributed across economically sensitive areas.
Bottom Line
The Australian equity market showed improved breadth on 14 September 2026, with seven of twelve sectors recording gains. Health Care led the market with a strong 1.52% increase, followed by Consumer Staples at 0.61% and Financials at 0.43%.
The strength across Health Care, Consumer Staples, Financials, Energy and Utilities indicates that buying interest was relatively broad. However, the sharp 1.14% decline in Information Technology and continued weakness in Materials and Resources demonstrate that the market remained uneven.
Overall, the latest sector performance suggests a more constructive market structure, although continued strength across a broader range of sectors would be needed to confirm a sustained improvement in overall ASX momentum.


 Nov 12, 2026





 Please wait processing your request...