
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
- Energy Leads the Market: Energy (XEJ) gained 2.19%, recording the strongest performance among the twelve ASX sectors.
- Resources and Materials Rebound: Resources (XJR) rose 1.55%, while Materials (XMJ) advanced 1.28%, marking a strong recovery across commodity-related sectors.
- Eight Sectors Finish Higher: Eight of the twelve sectors recorded positive daily performances, indicating broader buying interest.
- Technology and Communication Services Advance: Technology (XIJ) gained 0.30%, while Communication Services (XTJ) increased 0.46%.
- Financials Remain Relatively Stable: Financials (XFJ) declined only 0.37%, limiting the impact of weakness among selected sectors.
- Consumer Staples Records the Largest Decline: Consumer Staples (XSJ) fell 1.15%, making it the weakest-performing sector of the session.
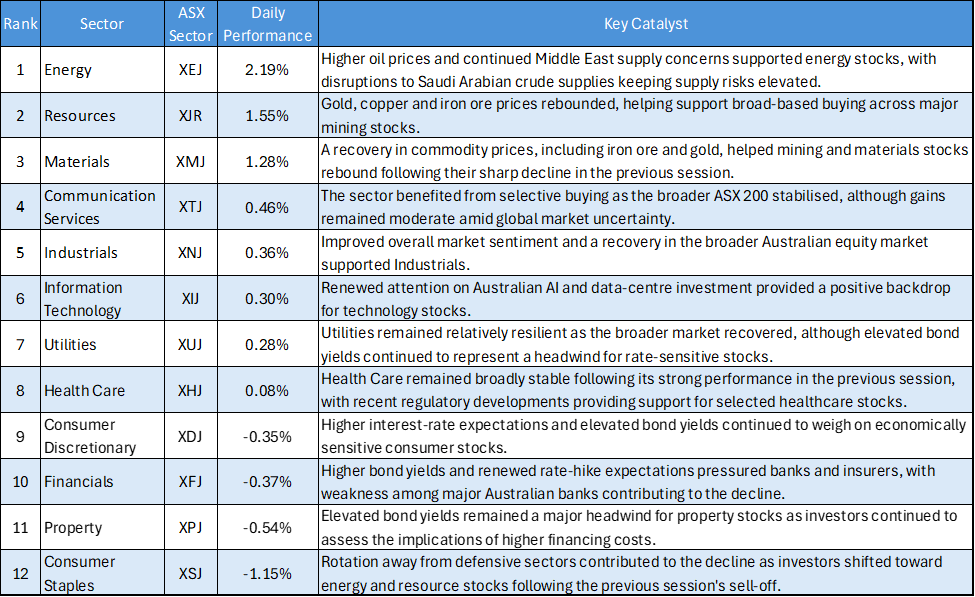
The Australian Equity market displayed a notably stronger sector profile on 16 September 2026, with eight of the twelve sectors finishing higher. Energy recorded the strongest gain at 2.19%, followed by Resources at 1.55% and Materials at 1.28%. At the other end of the ranking, Consumer Staples declined 1.15%, while Consumer Discretionary and Financials also recorded modest losses. The distribution indicates that buying interest was considerably broader than in the previous session, particularly across resource-related sectors.
Daily ASX Sector Performance Summary
Energy Leads the Market
Energy recorded the strongest performance on 16 September, gaining 2.19%. This placed the sector clearly ahead of all other groups and represented a significant improvement compared with the previous session, when Energy was among the weakest-performing sectors. The latest result therefore highlights a substantial change in relative sector performance.
Resources followed with a 1.55% gain, while Materials advanced 1.28%. The simultaneous strength across these three commodity-related sectors is particularly notable because Resources and Materials had previously been positioned at the bottom of the daily ranking. The performance data therefore shows a clear rebound in resource-related market segments.
The gap between Energy, the strongest-performing sector, and Consumer Staples, the weakest-performing sector, was 3.34 percentage points. This relatively wide spread demonstrates that sector performance remained differentiated even as overall Market Breadth improved.
Market Breadth Improves
Eight of the twelve sectors finished higher, compared with the more uneven performance observed in the previous session. The broader participation suggests that buying interest extended beyond a small number of defensive or consumer-oriented sectors.
Communication Services gained 0.46%, ranking fourth overall, while Information Technology increased 0.30%. Utilities also advanced 0.28%, and Health Care was almost unchanged, gaining just 0.08%.
The combination of positive performances across Energy, Resources, Materials, Technology, Communication Services and Utilities indicates that the advance was distributed across several different areas of the market. However, the magnitude of gains outside the resource-related sectors remained relatively modest.
Resource-Related Sectors Rebound
The most notable development was the strong recovery across Energy, Resources and Materials. Energy rose 2.19%, Resources gained 1.55%, and Materials increased 1.28%. Together, these three sectors occupied the top three positions in the daily ranking.
This represents a sharp contrast with the previous session, when Resources and Materials recorded the two largest declines. The latest performance therefore suggests that selling pressure in commodity-linked sectors eased substantially, at least during this session.
However, a single day's performance does not establish a sustained change in sector momentum. Continued strength across subsequent sessions would provide greater evidence of whether the rebound represents a broader improvement in resource-sector performance.
Consumer and Financial Sectors Weaken
Consumer Staples was the weakest-performing sector, declining 1.15%. This was notable because Consumer Staples had been one of the strongest-performing sectors in the previous session. The Reversal highlights the changing nature of short-term sector leadership.
Consumer Discretionary also weakened, falling 0.54%, while Financials declined 0.37%. Property recorded a slightly larger decline of 0.54%, and Industrials fell 0.35%.
Despite these losses, the declines were relatively contained compared with the gains recorded by Energy, Resources and Materials. As a result, the negative performance from these sectors did not prevent the overall sector breadth from becoming more positive.
Technology and Defensive Sectors Remain Resilient
Information Technology gained 0.30%, continuing to provide modest support to the broader market. Communication Services performed slightly better, advancing 0.46%. The positive performance of both sectors suggests that buying interest was not restricted to commodity-related stocks.
Utilities rose 0.28%, while Health Care was broadly unchanged at 0.08%. Their relatively stable performance provided additional balance to the sector landscape, although neither sector displayed the strength seen in Energy, Resources or Materials.
Bottom Line
The Australian equity market presented a broader and more constructive sector picture on 16 September 2026, with eight of twelve sectors recording gains. Energy led the market with a 2.19% increase, followed by Resources at 1.55% and Materials at 1.28%.
The strongest feature of the session was the rebound across resource-related sectors. Energy, Resources and Materials occupied the top three positions, representing a significant shift from the previous session when commodity-linked sectors experienced substantial weakness.
At the same time, Communication Services, Information Technology, Utilities and Health Care also finished higher, indicating that positive performance extended across several areas of the market. However, weakness in Consumer Staples, Consumer Discretionary, Property and Financials shows that the advance was not completely uniform.
Overall, the 16 September sector data points to improved market breadth and a pronounced recovery in resource-related sectors. Further sessions will be important in determining whether this improvement develops into a more sustained shift in sector leadership.


 Nov 12, 2026





 Please wait processing your request...