
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
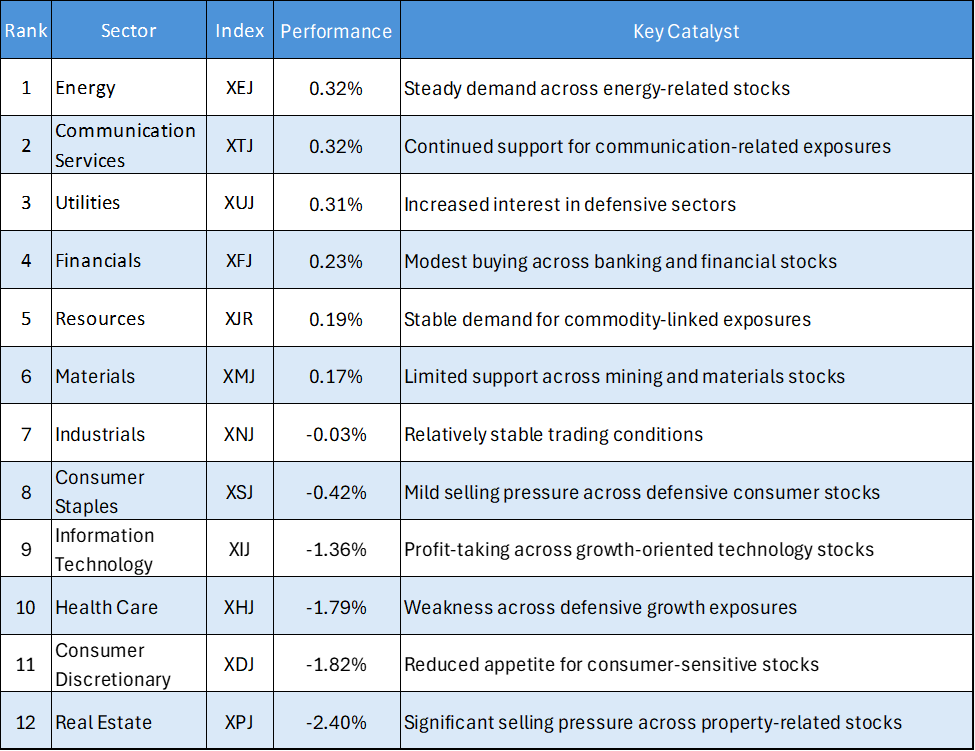
- Utilities Lead the Market: Utilities (XUJ) gained 0.31%, recording the strongest performance among all ASX sectors.
- Energy and Communication Services Advance: Energy (XEJ) and Communication Services (XTJ) both rose 0.32%, providing additional support to the market.
- Financials and Resources Finish Higher: Financials (XFJ) added 0.23%, while Resources (XJR) gained 0.19%.
- Industrials Remain Stable: Industrials (XNJ) edged down just 0.03%, making it one of the most resilient sectors during the session.
- Real Estate Becomes the Weakest Sector: Real Estate (XPJ) fell 2.40%, recording the largest decline among all sectors.
- Negative Market Breadth: Six of the twelve ASX sectors advanced, while six declined, although losses among the weaker sectors significantly outweighed gains elsewhere.
The Australian Equity market delivered a mixed performance on 21 August 2026, with Utilities emerging as the strongest sector after gaining 0.31%. Energy and Communication Services also advanced 0.32%, while Financials and Resources posted modest gains.
Despite an even split between advancing and declining sectors, the overall tone was cautious as several sectors recorded notable losses. Weakness across Real Estate, Consumer Discretionary and Health Care contrasted sharply with the modest gains seen elsewhere, suggesting investors remained selective in their sector allocation. This structure follows the style and analysis framework of the reference article.
Daily ASX Sector Performance Summary
Defensive and Income Sectors Take the Lead
- Utilities (XUJ) gained 0.31%, ranking among the strongest-performing sectors and highlighting Demand for defensive exposures.
- Energy (XEJ) and Communication Services (XTJ) both advanced 0.32%, providing the market's best performance during the session.
- Financials (XFJ) and Resources (XJR) also finished higher, helping offset weakness across several growth-oriented sectors.
The session's Leadership came primarily from defensive and income-oriented areas of the market. Utilities, Energy and Communication Services delivered the strongest gains, although advances remained relatively modest. The positive performance across these sectors suggests investors maintained a cautious stance while still seeking selective opportunities.
Materials and Resources also finished in positive territory, indicating that commodity-related sectors continued to attract some support despite the broader mixed market environment.
Growth and Property Sectors Face Selling Pressure
Information Technology (XIJ) declined 1.36%, making it one of the weaker-performing sectors during the session. Health Care (XHJ) also fell 1.79%, reflecting selling pressure across sectors that had previously benefited from defensive growth demand.
Consumer Discretionary (XDJ) dropped 1.82%, while Consumer Staples (XSJ) lost 0.42%. The declines suggest investors reduced exposure across both cyclical and defensive consumer-related segments.
The largest decline came from Real Estate (XPJ), which fell 2.40% and significantly underperformed the broader market. The gap between the strongest-performing sectors and Real Estate highlights a clear divergence in investor positioning during the session.
Bottom Line
The Australian equity market displayed mixed sector momentum on 21 August 2026, with Energy, Communication Services and Utilities leading gains of around 0.3%. Financials, Resources and Materials also contributed modestly to positive market performance.
However, weakness across Real Estate, Consumer Discretionary, Health Care and Information Technology weighed on overall sentiment. While Market Breadth was evenly balanced between advancing and declining sectors, the magnitude of losses among the weakest sectors suggests a more defensive and selective Investment environment.
Looking ahead, a recovery in Real Estate and growth-oriented sectors such as Technology and Health Care would help improve overall market participation. Continued strength in Utilities, Energy and Financials would provide further support for broader market stability.


 Nov 12, 2026





 Please wait processing your request...