
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
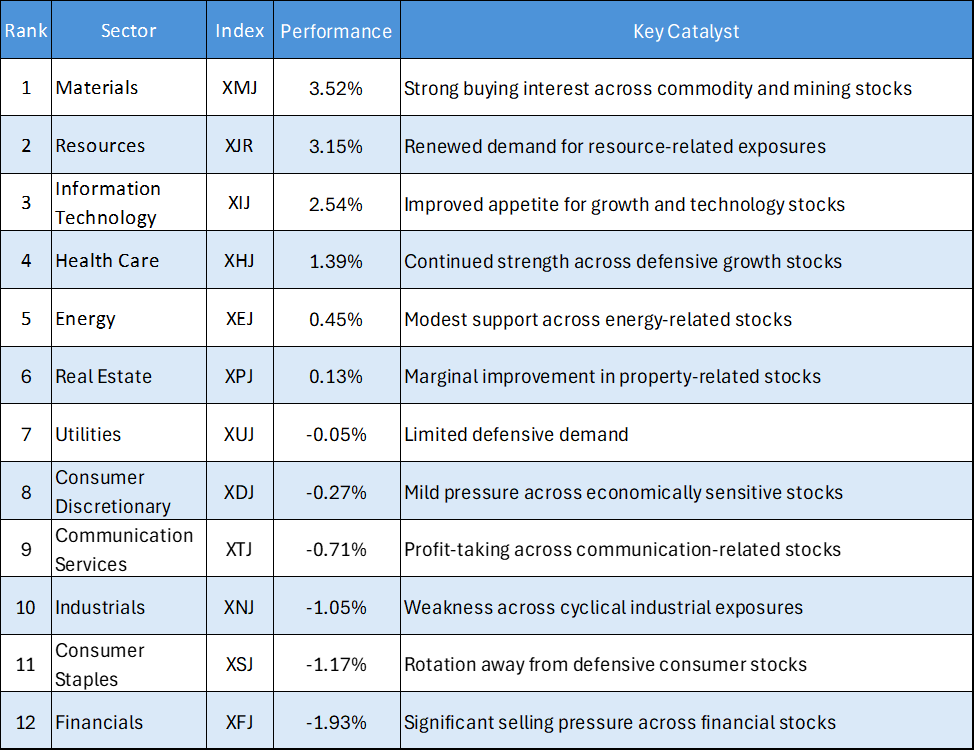
- Materials Lead the Market: Materials (XMJ) surged 3.52%, recording the strongest performance among all ASX sectors.
- Resources Rally Strongly: Resources (XJR) advanced 3.15%, highlighting strong buying interest across commodity-related stocks.
- Technology and Health Care Gain: Information Technology (XIJ) rose 2.54%, while Health Care (XHJ) added 1.39%, providing further support to the market.
- Energy and Real Estate Finish Higher: Energy (XEJ) and Real Estate (XPJ) posted smaller gains of 0.45% and 0.13%, respectively.
- Financials Become the Weakest Sector: Financials (XFJ) declined 1.93%, recording the largest sector loss of the session.
- Balanced Market Breadth: Six of the twelve ASX sectors advanced, while six declined, indicating a sharply divided market with strong Leadership concentrated in resources and growth-oriented sectors.
The Australian Equity market displayed a highly divergent sector performance on 20 August 2026, with Materials emerging as the clear leader after gaining 3.52%. Resources also rallied strongly by 3.15%, followed by Information Technology and Health Care, which advanced 2.54% and 1.39%, respectively.
Despite strong gains across several major sectors, Market Breadth remained evenly split, with six sectors advancing and six declining. The sharp contrast between strong resource-sector performance and weakness across Financials, Consumer Staples and Industrials suggests that investor Demand remained selective.
Daily ASX Sector Performance Summary
Materials and Resources Take the Lead
- Materials (XMJ) surged 3.52%, ranking first among all twelve ASX sectors and providing the strongest source of positive momentum.
- Resources (XJR) gained 3.15%, confirming broad-based strength across Commodity and mining-related exposures.
- The combined strength of Materials and Resources indicates that resource-related stocks were the primary beneficiaries of the session's risk appetite.
The strong performance of Materials and Resources represented the defining feature of the session. Both sectors significantly outperformed the rest of the market, suggesting a strong rotation toward commodity-linked exposures. The simultaneous gains across these two sectors also indicate that buying interest was relatively broad within the resources segment rather than being concentrated in a single area.
Technology and Health Care Provide Additional Support
Information Technology (XIJ) advanced 2.54%, making it the third-best-performing sector and reinforcing demand for growth-oriented stocks. Health Care (XHJ) also gained 1.39%, providing additional support from a sector that combines defensive characteristics with Long-term Growth exposure.
Energy (XEJ) added 0.45%, while Real Estate (XPJ) edged 0.13% higher. Although their gains were relatively modest, their positive performance helped maintain the balance between advancing and declining sectors.
The combination of strong Materials, Resources and Technology performance suggests that investors were willing to increase exposure to both cyclical and growth-oriented areas of the market.
Financials and Defensive Sectors Become the Main Laggards
Financials (XFJ) recorded the largest decline, falling 1.93%, making it the weakest-performing sector of the session. Consumer Staples (XSJ) also declined 1.17%, while Industrials (XNJ) fell 1.05%.
Communication Services (XTJ) declined 0.71%, followed by Consumer Discretionary (XDJ), which eased 0.27%. Utilities (XUJ) remained almost unchanged, slipping just 0.05%.
The divergence between Materials and Financials was particularly notable. While resource-related sectors posted gains of more than 3%, Financials declined almost 2%, highlighting a significant rotation in investor positioning. Weakness across Consumer Staples and Utilities also suggests that defensive sectors attracted less demand during the session.
Bottom Line
The Australian equity market displayed strong but selective sector momentum on 20 August 2026, with Materials and Resources dominating performance after gaining 3.52% and 3.15%, respectively. Information Technology and Health Care also recorded solid advances, supporting the broader market.
However, the equal split between advancing and declining sectors indicates that the rally was not broad-based. Strong resource and technology performance contrasted sharply with weakness in Financials, Consumer Staples and Industrials.
Looking ahead, continued strength in Materials, Resources and Technology would reinforce the market's positive momentum. A recovery in Financials and Industrials, together with broader participation across defensive sectors, would provide stronger confirmation that the improvement in market conditions is becoming more widespread.


 Nov 12, 2026





 Please wait processing your request...