
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
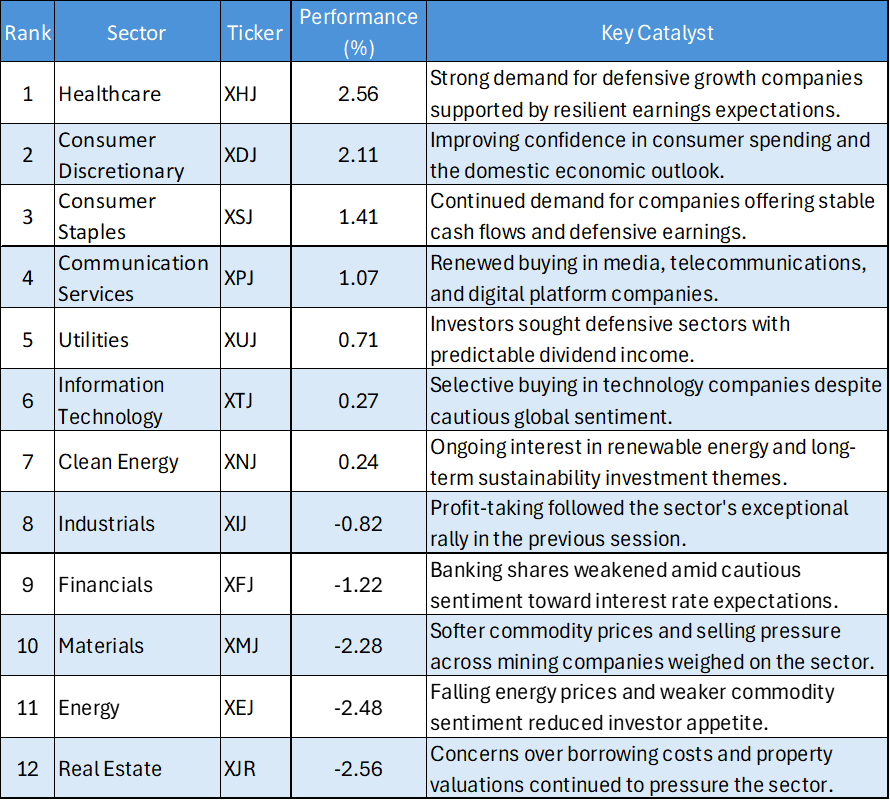
- Healthcare Emerges as Market Leader: Healthcare (XHJ) climbed 2.56%, recording the strongest gain of the session as investors favoured defensive growth stocks with resilient earnings.
- Consumer Discretionary Rallies Strongly: Consumer Discretionary (XDJ) advanced 2.11%, reflecting growing optimism surrounding consumer spending and domestic economic activity.
- Broad-Based Strength Across Defensive and Growth Sectors: Consumer Staples (XSJ), Communication Services (XPJ), Utilities (XUJ), Information Technology (XTJ), and Clean Energy (XNJ) all closed higher, demonstrating healthy market participation.
- Resource and Cyclical Sectors Underperform: Real Estate (XJR), Energy (XEJ), Materials (XMJ), and Financials (XFJ) ended lower, highlighting continued investor rotation away from commodity-linked sectors.
The Australian equity market delivered a mixed but generally constructive performance on June 25, 2026, with investors continuing to rotate capital into Healthcare and consumer-oriented sectors while reducing exposure to resources and cyclicals. Defensive growth companies attracted renewed buying interest, helping offset weakness across Energy, Materials, and Real Estate.
Although several major sectors finished in negative territory, the strong gains in Healthcare and Consumer Discretionary indicate improving confidence in Australia's domestic economy and corporate earnings outlook. The session reflected a clear divergence between sectors benefiting from stable earnings growth and those more heavily exposed to global commodity price fluctuations.
Daily ASX Sector Performance Summary
Key Market Themes
Healthcare Leads the Market
- Healthcare (XHJ) rose 2.56%, making it the strongest-performing sector of the trading session. Investors continued to favour companies with defensive earnings characteristics and reliable long-term growth prospects amid lingering macroeconomic uncertainty. The sector's outperformance suggests market participants remain willing to pay a premium for businesses capable of delivering stable earnings regardless of broader economic conditions. Strong buying interest in healthcare also highlights a preference for quality assets during periods of mixed market sentiment.
Consumer Sectors Reflect Improving Domestic Confidence
- Consumer Discretionary (XDJ) surged 2.11%, while Consumer Staples (XSJ) gained 1.41%, indicating optimism toward Australia's consumer economy. Strength in discretionary retailers suggests investors expect household spending to remain resilient, while continued demand for staples reflects an ongoing preference for companies with dependable revenue streams. Together, these sectors point to balanced investor positioning between growth opportunities and defensive stability.
Defensive Growth Continues to Attract Capital
- Communication Services (XPJ), Utilities (XUJ), Information Technology (XTJ), and Clean Energy (XNJ) all posted gains, reinforcing the broad participation across sectors outside the commodity complex. Utilities benefited from demand for stable dividend-paying companies, while Technology and Communication Services attracted selective buying following recent market volatility. The positive performance across these sectors demonstrates investors' willingness to diversify into industries offering structural growth alongside defensive characteristics.
Resource Sectors Face Renewed Selling Pressure
- Materials (XMJ) fell 2.28%, while Energy (XEJ) dropped 2.48%, making them among the weakest performers of the session. The declines likely reflected softer commodity prices, profit-taking after previous rallies, and ongoing uncertainty surrounding global demand. Investors appeared to reduce exposure to sectors whose earnings remain closely tied to fluctuations in commodity markets, favouring businesses with stronger earnings visibility instead.
Real Estate Remains Under Pressure
- Real Estate (XJR) declined 2.56%, recording the weakest performance among all sectors. Property-related stocks continued to struggle as investors assessed the outlook for interest rates, financing costs, and commercial property valuations. The sector's continued weakness suggests concerns surrounding borrowing costs and economic growth remain key headwinds despite improving sentiment elsewhere in the market.
Bottom Line
The June 25 trading session demonstrated continued sector rotation within the Australian equity market. Healthcare and Consumer Discretionary emerged as clear leaders, reflecting growing confidence in domestic economic resilience and companies capable of delivering consistent earnings growth.
Meanwhile, Energy, Materials, Financials, and Real Estate experienced notable selling pressure as investors reduced exposure to sectors facing greater macroeconomic and commodity-related uncertainty. Should leadership from Healthcare and consumer-focused sectors continue while weakness in resource sectors persists, the ASX may continue to exhibit a more selective, earnings-driven market environment in the near term.


 Nov 12, 2026





 Please wait processing your request...