
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
- The Banking Relief Rally: Financials (XFJ) acted as the primary index stabilizer, executing a +1.02% mean-reversion bounce following the catastrophic Liquidation event witnessed in the prior session.
- Tech’s Relentless Death Spiral: Information Technology (XIJ) suffered another severe algorithmic flush, plunging -2.20% to establish the absolute lower bound of the performance spread and confirming total momentum exhaustion.
- Commodity Engines Idle: After days of explosive structural breakouts, the primary resource barbell took a localized breather, with Materials (XMJ) and Resources (XJR) printing mild consolidations of -0.10% and -0.20% respectively.
- Staples Suffer Deep Distribution: The consumer complex pain deepened as Consumer Staples (XSJ) suffered a brutal -1.87% contraction, proving that traditional defensive Yield offers no safety in the current rotational environment.
The ASX Equity market session on May 14, 2026, delivered a tape defined by violent mean-reversion and ongoing structural fracturing. Rather than a cohesive directional trend, institutional Capital engaged in localized fire-fighting. The massive Liquidity extracted from the banking complex yesterday was partially redeployed back into the sector to arrest the freefall. However, this stabilization at the top end of the index was entirely offset by a brutal, sustained distribution event across high-Beta growth and traditional domestic consumer safety.
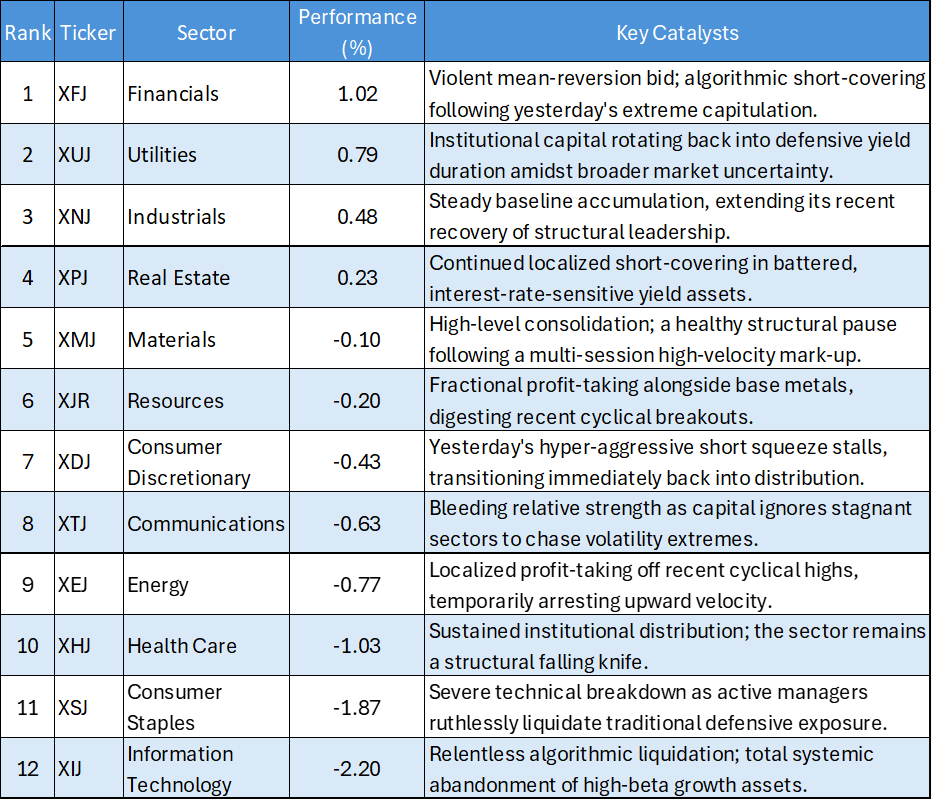
Daily ASX Sector Performance Summary (14/05/2026)
The following table summarizes the day's performance across the major ASX sectors, ordered by highest recorded return:
Key Market Themes
The Financials Mean-Reversion (+1.02%)
The most critical mathematical footprint of the May 14 session was the +1.02% bounce in Financials (XFJ). Following the terrifying -4.01% institutional flush yesterday, the index required the banking heavyweight to establish a structural floor to prevent a broader benchmark collapse. This price action represents a classic quantitative mean-reversion—short sellers covering localized exposure rather than the initiation of a fresh cyclical mark-up. It provides a temporary safety net, but the structural damage from the prior session remains immense.
The Tech Capitulation Extends (-2.20%)
While the banks found temporary relief, Information Technology (XIJ) continues to be systematically dismantled. The -2.20% plunge confirms that the localized stabilization attempted earlier in the week has completely failed. Institutional desks are aggressively using the tech sector as a primary funding source, flushing high-beta growth out of their portfolios with zero regard for historical valuations.
Commodity Consolidation (-0.10% / -0.20%)
The high-velocity commodity squeeze took a necessary pause. Materials (XMJ) and Resources (XJR) shed fractional percentages, closing essentially flat. In empirical Technical Analysis, an asset that consolidates horizontally immediately following a massive structural breakout is highly constructive. It indicates that Supply is being actively absorbed at higher prices without triggering a severe Retracement, keeping the resource complex primed for future momentum capture.
The Consumer Deficit Deepens (-1.87%)
The domestic consumer footprint remains a toxic environment for long-beta capital. While Consumer Discretionary (XDJ) gave back a mild -0.43% following yesterday's rocket-launch squeeze, the real damage occurred in Consumer Staples (XSJ), which plummeted -1.87%. The failure of staples—traditionally a recessionary safe-haven—signals deep institutional pessimism. Capital is entirely abandoning the domestic retail and consumer supply chain.
The empirical data from May 14 outlines an exhausted tape navigating extreme rotational whiplash. The relief bid in Financials masks the severe structural decay occurring beneath the surface, specifically the relentless algorithmic liquidation in Technology and Consumer Staples.
Active managers must tread carefully in this highly fractured environment. The high-level consolidation in Materials and Resources suggests the commodity barbell remains the only reliable structural long. Conversely, any long exposure in Tech, Health Care, or the Consumer complex is strictly counter-trend and highly vulnerable to further downside velocity. Maintain tight risk parameters and avoid chasing the banking bounce until empirical Volume confirms a true trend Reversal.


 Nov 12, 2026





 Please wait processing your request...