
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Momentum Shifts
- Information Technology (XIJ), Health Care (XHJ), Materials (XMJ) and Resources (XJR) remain in the Leading quadrant, indicating strong relative momentum and relative strength.
- Utilities (XUJ) remains in the Improving quadrant, signalling continued recovery in its relative momentum.
- Energy (XEJ) has moved into the Lagging quadrant, marking the latest deterioration in sector momentum.
- Seven sectors are now positioned in Lagging, including Financials (XFJ), Consumer Discretionary (XDJ), Real Estate (XPJ), Communication Services (XTJ), Consumer Staples (XSJ), Industrials (XNJ) and Energy (XEJ).
- No sectors currently occupy the Weakening quadrant, highlighting a rotation concentrated between Leading, Improving and Lagging.
The latest Relative Rotation Graph (RRG) for 17 August 2026 indicates that sector momentum across the Australian Equity market remains highly selective. Information Technology (XIJ), Health Care (XHJ), Materials (XMJ) and Resources (XJR) continue to occupy the Leading quadrant, maintaining their positions as the primary sources of relative strength.
The most notable change is the movement of Energy (XEJ) from Weakening into Lagging. Utilities (XUJ) remains the only sector in Improving, while seven sectors are now positioned in Lagging. The updated RRG therefore points to continued concentration of Leadership and limited improvement in overall momentum breadth.
Momentum Breakdown by Quadrant
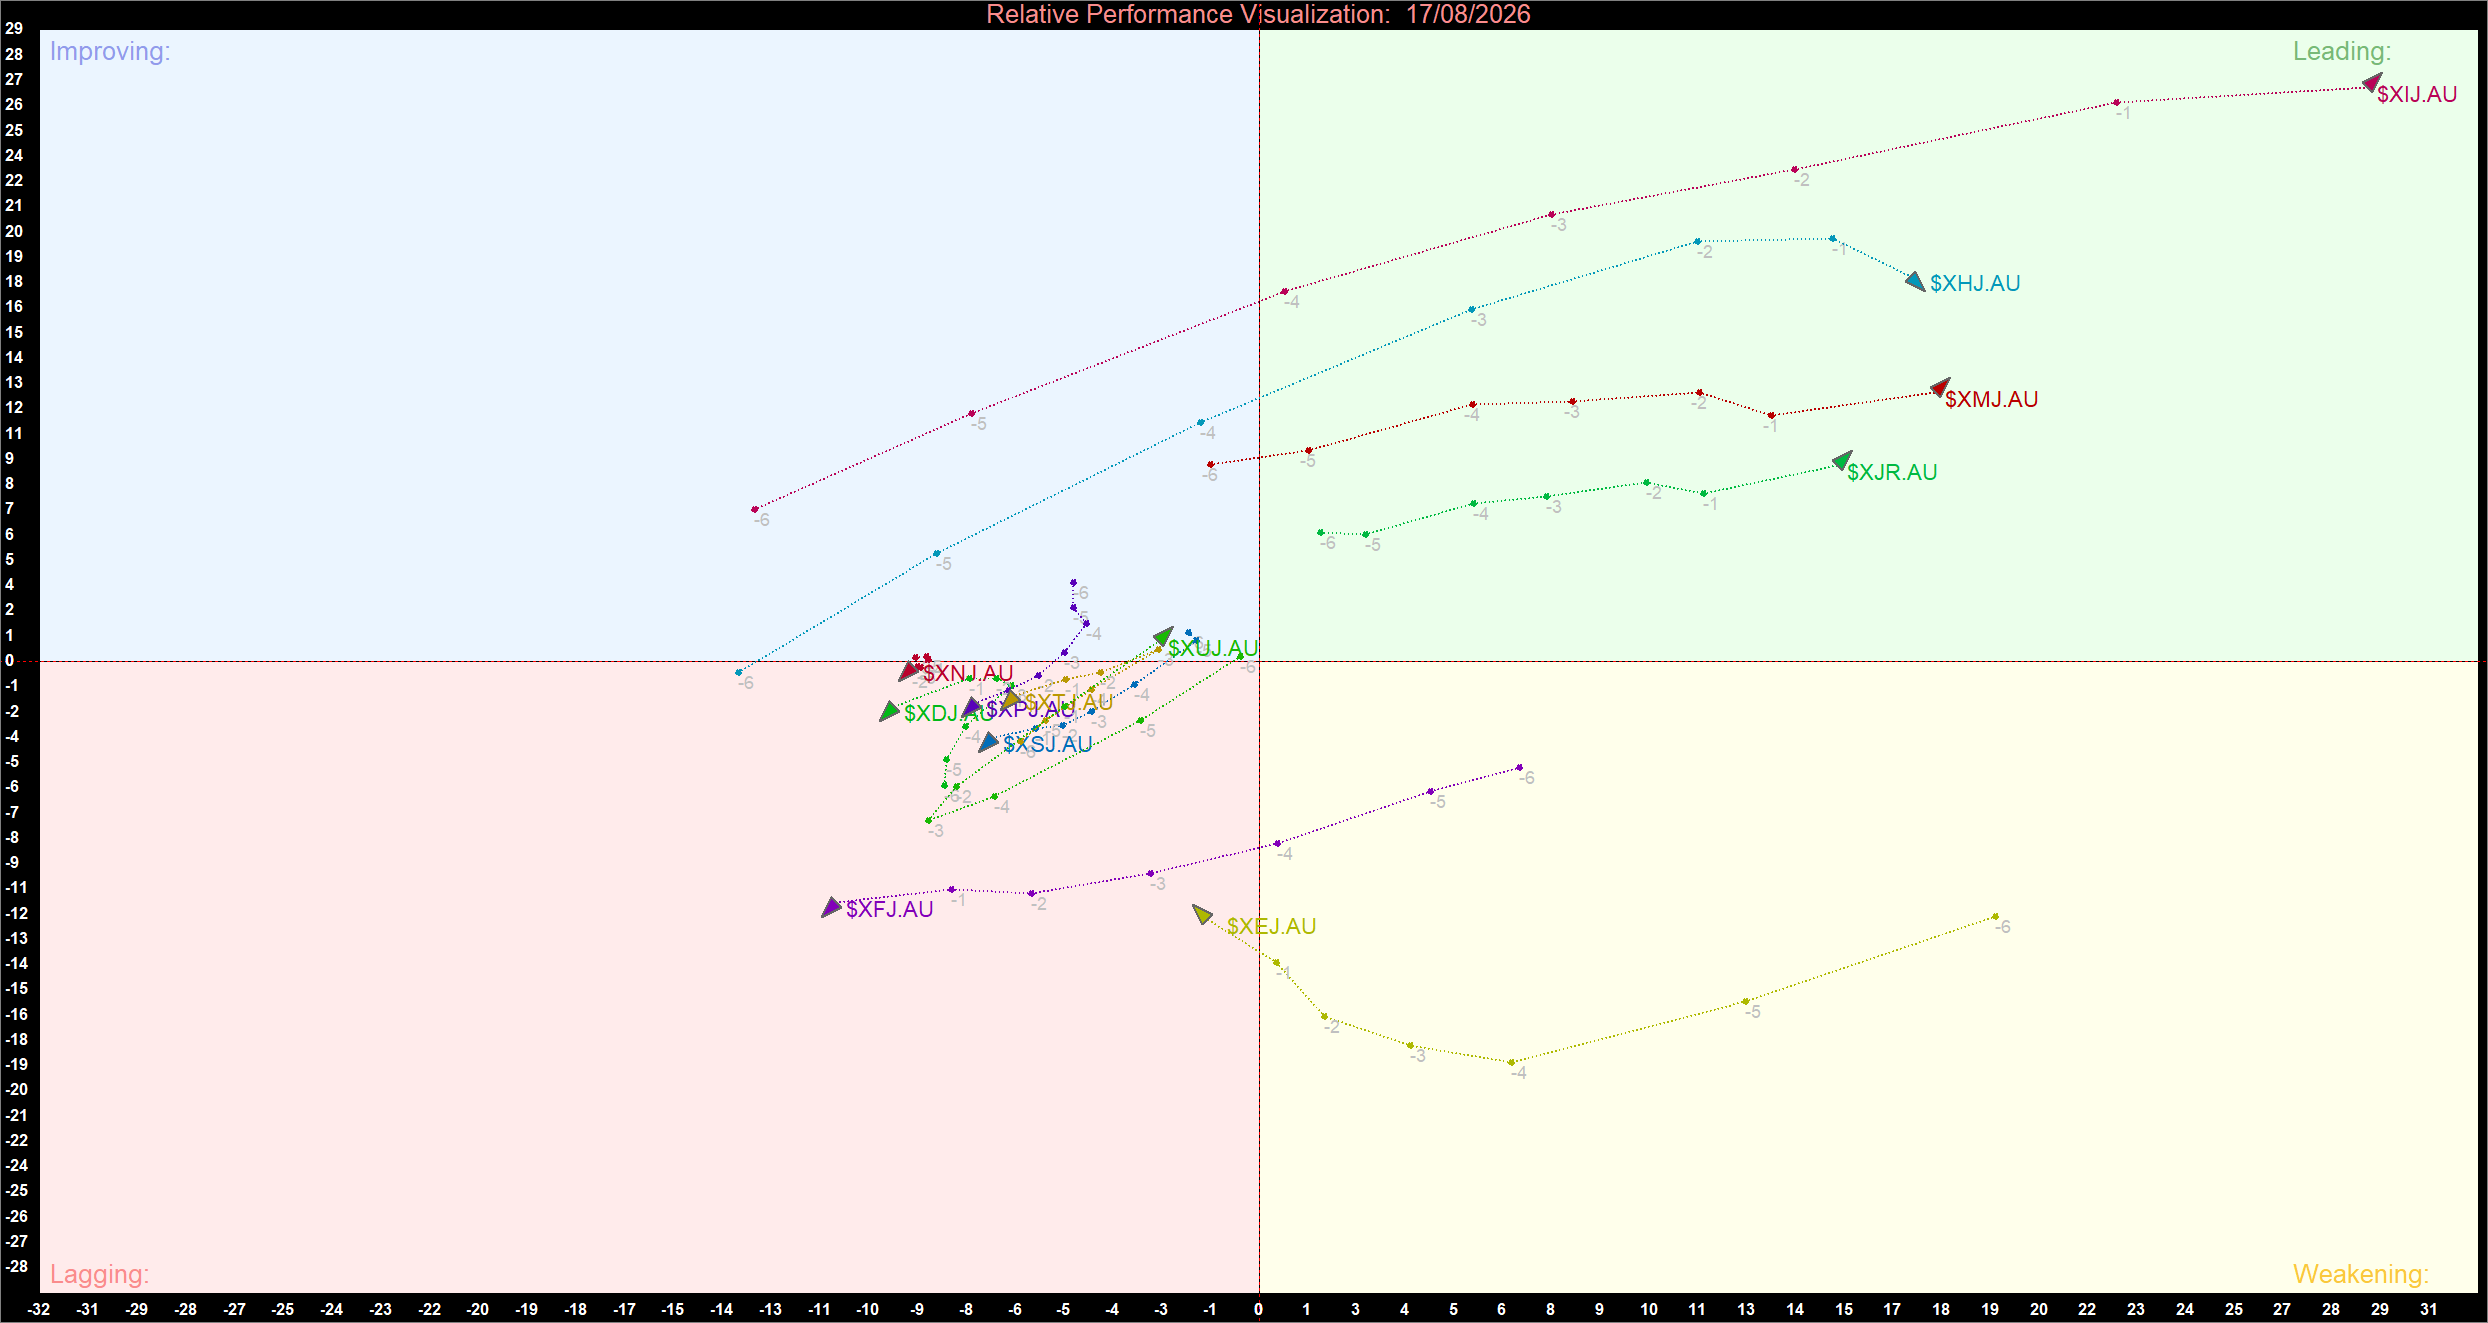
ASX Sector Relative Momentum Chart (at the closing price of 17/08/2026). Powered by: amibroker.com.
Leading Quadrant
The presence of four sectors in Leading indicates that Technology, Health Care, Materials and Resources continue to represent the principal sources of relative strength in the Australian equity market.
Information Technology (XIJ) remains the strongest sector on the chart, positioned well into the Leading quadrant and maintaining a clear separation from the rest of the market. Health Care (XHJ) also remains firmly positioned in Leading, while Materials (XMJ) and Resources (XJR) continue to display positive relative strength.
The continued Leading positions of these four sectors suggest that the market's strongest momentum remains concentrated within a relatively small group rather than broadly distributed across sectors.
Improving Quadrant
Utilities (XUJ) remains the only sector in the Improving quadrant. Its position indicates that relative momentum is strengthening from a comparatively weaker position.
If Utilities continues to move upward and to the right on the RRG, it could eventually challenge the Leading quadrant. However, confirmation would require sustained improvement in both relative strength and momentum.
The lack of additional sectors entering Improving highlights the limited breadth of the current momentum recovery.
Weakening Quadrant
There are currently no sectors in the Weakening quadrant.
This represents a change from the previous RRG, when Energy (XEJ) occupied Weakening. Its movement into Lagging indicates that its relative momentum has deteriorated further rather than stabilising.
Lagging Quadrant
Seven sectors are now positioned in Lagging: Energy (XEJ), Financials (XFJ), Consumer Discretionary (XDJ), Real Estate (XPJ), Communication Services (XTJ), Consumer Staples (XSJ) and Industrials (XNJ).
Energy's move into Lagging is the most important negative momentum shift in the latest chart. The transition suggests that the sector's relative momentum has weakened sufficiently to move below the Lagging boundary.
The concentration of seven sectors in Lagging continues to highlight the weakness in market breadth. While several sectors remain relatively close to the centre of the RRG, their positions still indicate weaker relative momentum compared with the Leading group.
Strategic Summary
The latest RRG shows that ASX sector momentum remains selective and concentrated. Information Technology, Health Care, Materials and Resources continue to lead, while Utilities remains the only sector in Improving.
The move of Energy into Lagging is the key negative momentum shift, increasing the number of Lagging sectors to seven. At the same time, the absence of sectors in Weakening suggests that the current rotation is concentrated between the Leading, Improving and Lagging quadrants.
Technology remains the strongest leader, while a sustained improvement in Utilities and further moves from Lagging into Improving would provide stronger evidence of a broader recovery in sector momentum.


 Nov 12, 2026





 Please wait processing your request...