
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Momentum Shifts
- Four Sectors Remain in Leading: Information Technology (XIJ), Health Care (XHJ), Materials (XMJ) and Real Estate (XJR) continue to occupy the Leading quadrant, indicating relatively strong momentum and relative strength.
- Energy Remains in Weakening: Energy (XEJ) is the only sector positioned in Weakening, indicating that its relative momentum is deteriorating despite a modest daily decline of 0.35%.
- Seven Sectors Remain Lagging: Utilities (XUJ), Communication Services (XSJ), Consumer Discretionary (XPJ), Financials (XFJ), Industrials (XNJ), Consumer Staples (XDJ) and Telecommunications (XTJ) occupy the Lagging quadrant.
- Utilities Deliver the Strongest Daily Gain: Utilities (XUJ) surged 2.78%, the strongest performance among all 12 sectors, despite remaining in Lagging on the RRG.
- Technology and Consumer Staples Also Advance: Information Technology (XIJ) gained 0.85%, while Consumer Staples (XDJ) rose 0.74%, providing additional support to the market.
- Communication Services Is the Biggest Laggard: Communication Services (XTJ) declined 2.30%, recording the weakest daily performance among all sectors.
- Market Leadership Remains Concentrated: The RRG continues to show a clear concentration of relative strength in four sectors, while most sectors remain positioned in Lagging.
The latest Relative Rotation Graph (RRG) for 13 August 2026 indicates that sector momentum across the Australian Equity market remains highly selective. Information Technology (XIJ), Health Care (XHJ), Materials (XMJ) and Real Estate (XJR) continue to occupy the Leading quadrant, maintaining their positions as the primary sources of relative strength.
Energy (XEJ) is the only sector positioned in Weakening, while the remaining seven sectors are concentrated in Lagging. This structure highlights a market where leadership remains narrow despite strong individual daily performances in some sectors, particularly Utilities.
Momentum Breakdown by Quadrant
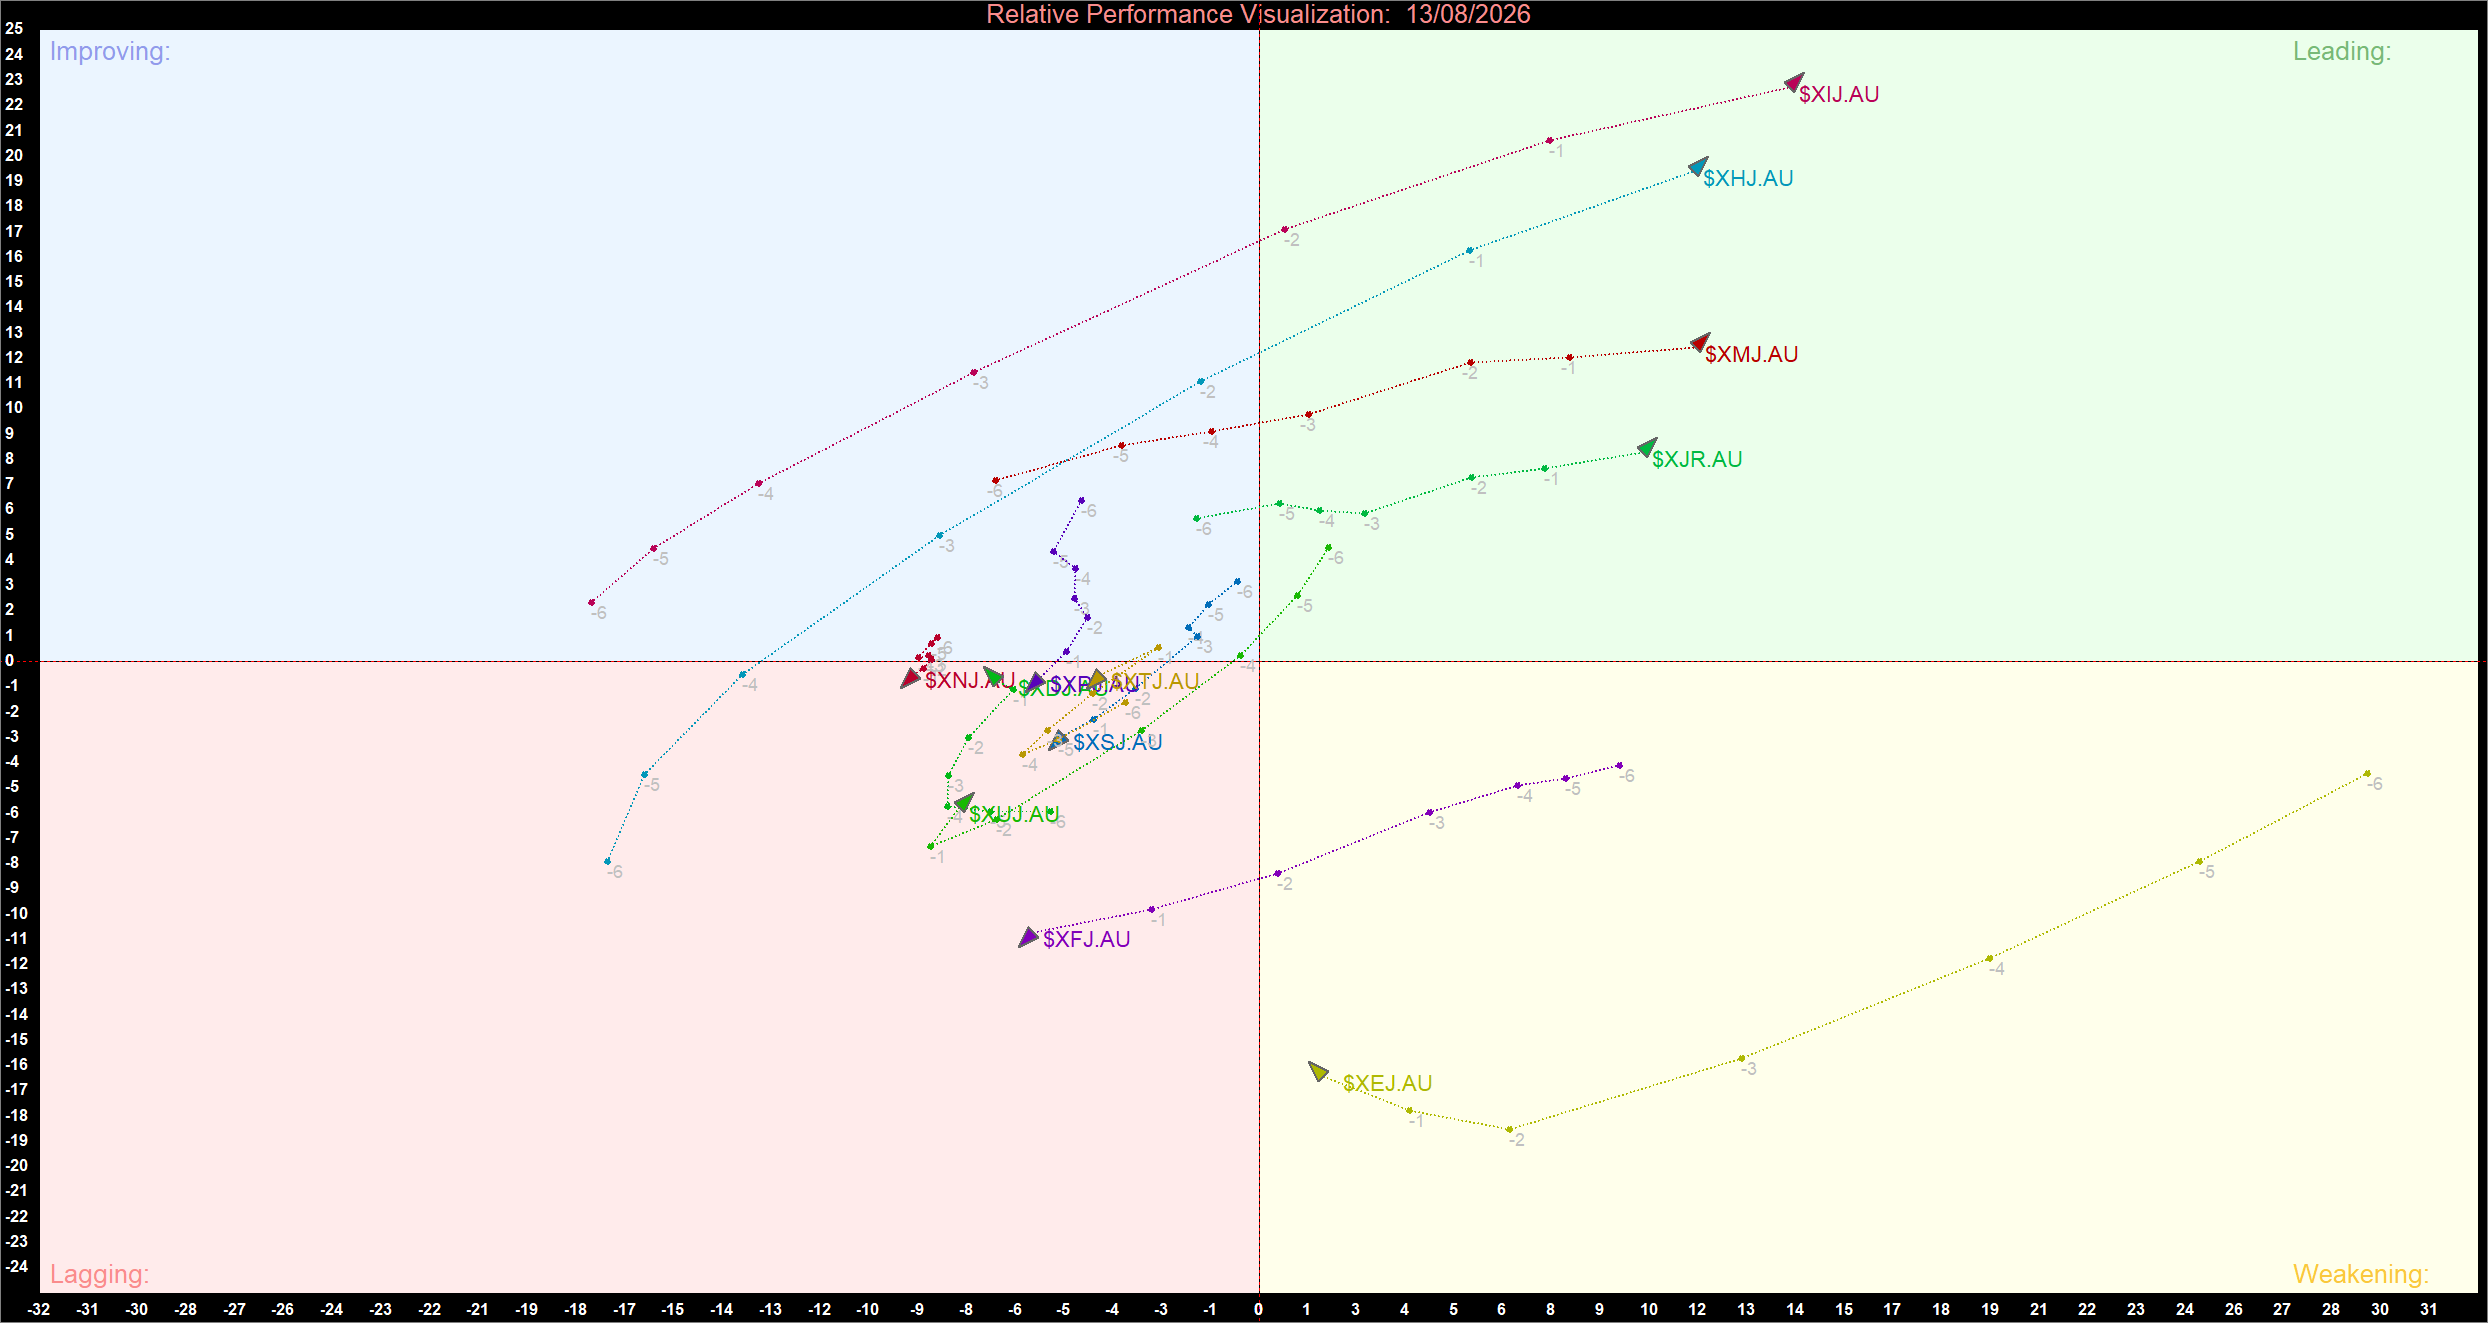
ASX Sector Relative Momentum Chart (at the closing price of 13/08/2026). Powered by: amibroker.com.
Leading Quadrant
- Information Technology (XIJ) remains in the Leading quadrant, indicating strong relative momentum and favourable positioning within the current sector rotation. The sector also gained 0.85% in the latest session, reinforcing its positive short-term performance.
- Health Care (XHJ) continues to occupy Leading, reflecting sustained relative strength. The sector advanced 0.17% during the session.
- Materials (XMJ) remains in Leading, supported by its favourable relative positioning despite declining 0.71% on the latest trading day.
- Real Estate (XJR) also remains in Leading, indicating that property-related equities continue to demonstrate relatively strong momentum despite a 0.66% decline.
The presence of four sectors in Leading indicates that Technology, Health Care, Materials and Real Estate remain the principal sources of relative strength in the Australian equity market. However, the mixed daily performance of these sectors demonstrates that RRG positioning reflects broader relative momentum rather than simply the latest one-day price movement.
Weakening Quadrant
- Energy (XEJ) is the only sector positioned in Weakening, indicating that its relative momentum is deteriorating.
- Energy declined 0.35% during the latest session, contrasting with the much stronger performance recorded by Utilities, Information Technology and Consumer Staples.
Energy's position is important because it remains between the Leading and Lagging groups. A sustained improvement in its RRG trajectory would be required to signal a return toward stronger relative momentum, while continued deterioration could push the sector further into the Lagging quadrant.
The fact that Energy is the only sector in Weakening also indicates that the current rotation is relatively polarised, with sectors either maintaining leadership or remaining firmly positioned in the weaker part of the RRG.
Lagging Quadrant
- Utilities (XUJ) remains in Lagging despite surging 2.78%, highlighting the difference between short-term price performance and broader relative momentum.
- Communication Services (XSJ) remains in Lagging and recorded a sharp 2.30% decline, making it the weakest-performing sector of the session.
- Consumer Discretionary (XPJ) remains in Lagging after declining 0.15%.
- Financials (XFJ) is also positioned in Lagging, with the sector edging 0.08% higher.
- Industrials (XNJ) remains in Lagging despite a relatively modest 0.26% decline.
- Consumer Staples (XDJ) remains in Lagging even after gaining 0.74% during the session.
- Telecommunications (XTJ) remains in Lagging after falling 2.30%.
The concentration of seven sectors in Lagging represents the weakest part of the current RRG structure. While several of these sectors recorded positive or only modestly negative daily performances, their positions indicate that their broader relative momentum remains weaker than the Leading group.
The contrast between Utilities and its RRG position is particularly notable. Utilities gained 2.78%, the strongest daily performance among all 12 sectors, yet remains in Lagging. This demonstrates why short-term sector performance should not be interpreted in isolation from relative momentum and rotation trends.
Strategic Summary
The latest Relative Rotation Graph highlights a concentrated sector leadership structure across the Australian equity market. Information Technology (XIJ), Health Care (XHJ), Materials (XMJ) and Real Estate (XJR) remain in the Leading quadrant, making them the primary sources of relative strength.
Energy (XEJ) is the only sector in Weakening, while seven sectors — Utilities, Communication Services, Consumer Discretionary, Financials, Industrials, Consumer Staples and Telecommunications — remain in Lagging. The absence of sectors in Improving indicates that there is currently no clear emerging rotation from the weakest part of the market toward stronger relative momentum.
The contrast between RRG positioning and daily sector performance is particularly important. Utilities gained 2.78%, Information Technology rose 0.85% and Consumer Staples advanced 0.74%, yet all three remain outside the Leading quadrant except for Information Technology. Conversely, Materials and Real Estate remain in Leading despite declining 0.71% and 0.66%, respectively.
Overall, the RRG suggests that Information Technology, Health Care, Materials and Real Estate continue to provide the strongest relative leadership, while Energy is the only sector showing a weakening momentum profile. With seven sectors concentrated in Lagging and none in Improving, sector momentum remains selective and uneven. A rotation of one or more Lagging sectors into Improving would provide stronger evidence of a broadening market recovery.


 Nov 12, 2026





 Please wait processing your request...