
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Momentum Shifts
- Information Technology Establishes Dominant Leadership Position: Information Technology (XIJ) has emerged as the ASX’s strongest institutional leadership engine, deeply embedded within the Leading quadrant. The sector’s persistent North-East trajectory confirms sustained institutional accumulation and accelerating relative strength as capital aggressively rotates toward high-beta growth exposure.
- Consumer Sectors Continue Capturing Institutional Flows: Consumer Discretionary (XDJ) remains firmly positioned within the Leading quadrant despite recent momentum volatility, while Consumer Staples (XSJ) are quietly transitioning toward structural leadership. The simultaneous strength across both cyclical and defensive consumer segments reflects highly selective institutional allocation behavior favoring earnings visibility and domestic resilience.
- Health Care Builds Momentum as Defensive Growth Leadership Expands: Health Care (XHJ) continues strengthening inside the Improving quadrant, displaying one of the most constructive recovery trajectories on the matrix. Institutional capital remains heavily concentrated in high-quality defensive growth sectors offering durable earnings characteristics.
The ASX rotational structure has now evolved into a highly selective leadership environment dominated by Technology and consumer-oriented sectors. Unlike previous defensive rallies driven primarily by capital preservation flows, the current matrix reflects a more sophisticated institutional allocation regime centered around quality growth, domestic resilience, and tactical momentum expansion.
Importantly, the market is no longer functioning under synchronized macro participation. Instead, institutional desks are increasingly concentrating capital within sectors demonstrating superior earnings durability, pricing power, and momentum leadership while simultaneously reducing exposure to commodity-linked cyclicals and defensive yield structures.
ASX Sector Momentum Summary Chart
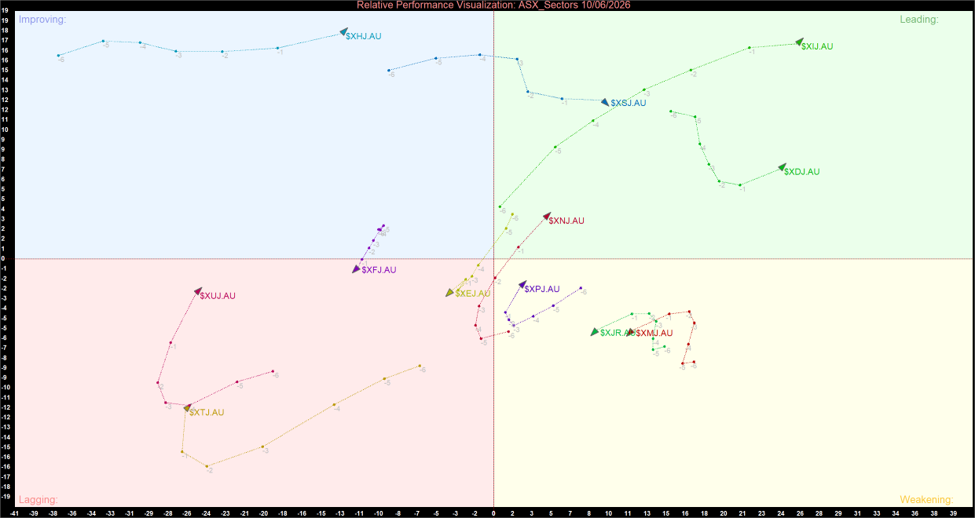
ASX Sector Relative Momentum Chart (at the closing price of 10/06/2026). Powered by: amibroker.com
ASX Sector Relative Momentum Overview
The Leading Quadrant (The Institutional Leadership Complex)
- Information Technology (XIJ): The dominant leadership structure on the matrix. XIJ remains deeply embedded within the Leading quadrant with exceptionally strong relative momentum and relative strength characteristics. The sector’s smooth North-East rotational trajectory signals sustained institutional sponsorship rather than temporary short-covering activity. Technology has now firmly re-established itself as the ASX’s primary high-beta accumulation zone.
- Consumer Discretionary (XDJ): Continues maintaining strong relative strength despite intermittent momentum volatility. The recent upward hook in the rotational structure suggests that prior profit-taking pressure has begun stabilizing, allowing institutional accumulation to reaccelerate. Domestic consumption resilience remains a critical supporting theme for the sector.
- Consumer Staples (XSJ): Quietly emerging as a secondary leadership candidate. While traditionally defensive in nature, Staples are now displaying improving relative strength characteristics alongside stabilizing momentum. Institutional capital appears increasingly attracted to sectors capable of delivering stable earnings visibility without sacrificing relative performance leadership.
The Improving Quadrant (The Emerging Recovery Structure)
- Health Care (XHJ): One of the strongest improving structures on the matrix. Relative momentum continues accelerating materially despite relative strength remaining marginally negative. The sector continues functioning as the market’s preferred defensive growth sanctuary, supported by persistent institutional accumulation focused on earnings durability and balance-sheet quality.
- Industrials (XNJ): Showing early signs of cyclical recovery. The sector has begun transitioning away from prior lagging conditions as momentum improves materially. Institutional desks are selectively rebuilding exposure toward infrastructure, logistics, engineering, and domestic industrial proxies following the recent correction cycle.
- Energy (XEJ): Early stabilization characteristics are beginning to emerge. Although the sector remains structurally fragile, improving momentum vectors suggest that the prior liquidation cycle may be moderating as selective bottom-fishing activity gradually returns.
The Weakening Quadrant (The Rotational Distribution Zone)
- Communication Services (XPJ): Relative momentum continues deteriorating despite retaining modest residual relative strength. Institutional conviction appears to be fading gradually as capital rotates toward stronger leadership themes within Technology and Consumer sectors.
- Materials (XMJ): Remains under persistent institutional distribution pressure. The sector’s unstable rotational trajectory indicates that commodity-linked exposures continue struggling to regain sustained sponsorship amid weakening global resource sentiment.
- Resources (XJR): Continues exhibiting structural fragility despite minor stabilization attempts. Relative momentum remains weak as institutional desks continue reducing exposure toward mining beta and broader commodity cyclicals.
The Lagging Quadrant (The Structural Underperformers)
- Utilities (XUJ): Defensive positioning continues unwinding aggressively. The sector remains deeply entrenched within the Lagging quadrant as institutional managers increasingly abandon low-volatility yield structures in favor of higher-conviction growth and recovery opportunities.
- Real Estate (XTJ): Remains one of the weakest structural segments on the matrix. Relative strength and momentum continue deteriorating simultaneously, reflecting persistent institutional caution toward property-linked exposures amid changing macro expectations.
- Financials (XFJ): Currently operating as a structurally neutral-to-weak segment near the matrix center. While outright collapse has not yet emerged, the banking complex lacks decisive institutional sponsorship capable of supporting broader market leadership. The sector continues functioning primarily as a benchmark stabilizer rather than a dominant accumulation zone.
Strategic Summary
The ASX momentum structure has entered a highly selective rotational phase dominated by Technology leadership, resilient consumer exposure, and emerging defensive growth momentum. Institutional capital is increasingly concentrating within sectors capable of delivering superior earnings visibility and structural growth characteristics while simultaneously reducing exposure to traditional defensive yield sectors and commodity-linked cyclicals.
Maintain core exposure toward Information Technology (XIJ), Consumer Discretionary (XDJ), and selectively improving Health Care (XHJ) structures, where institutional sponsorship remains strongest. Consumer Staples (XSJ) also warrant increasing attention as their rotational profile continues improving toward full leadership conditions.
Remain increasingly cautious toward Materials (XMJ), Resources (XJR), Utilities (XUJ), and Real Estate (XTJ), where structural momentum deterioration continues signaling persistent institutional de-risking activity.
The current ASX environment strongly favors tactical sector rotation, disciplined momentum allocation, and active stock selection rather than broad-based passive market exposure. Flexibility and relative-strength discipline remain critical as institutional flows continue rapidly evolving across the Australian equity landscape.


 Nov 12, 2026





 Please wait processing your request...