
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Momentum Shifts
- Health Care remains the only sector positioned in the Leading quadrant, although its daily performance declined 1.10%.
- Information Technology remains in Improving and recorded the strongest daily gain, surging 4.45%.
- Consumer Discretionary remains in Improving despite gaining 0.85% during the session.
- Materials and Resources are positioned in Improving, supported by daily gains of 1.14% and 1.23%, respectively.
- Real Estate remains in Improving despite recording the weakest daily performance, declining 1.63%.
- Consumer Staples, Financials and Industrials are positioned in Weakening, although all three recorded positive daily returns.
- Utilities, Energy and Communication Services remain in Lagging.
- The chart highlights a significant divergence between short-term daily performance and broader relative momentum.
The latest Relative Rotation Graph for 2 October 2026 shows continued divergence across ASX sector momentum. Health Care occupies the Leading quadrant, while Information Technology, Consumer Discretionary, Materials, Resources and Real Estate remain in Improving. Consumer Staples, Financials and Industrials are positioned in Weakening, while Utilities, Energy and Communication Services remain in Lagging.
The chart also demonstrates the distinction between daily price performance and broader relative momentum. Information Technology delivered the strongest daily gain while remaining in Improving, whereas Health Care remained the only sector in Leading despite recording a negative daily return.
Momentum Breakdown by Quadrant
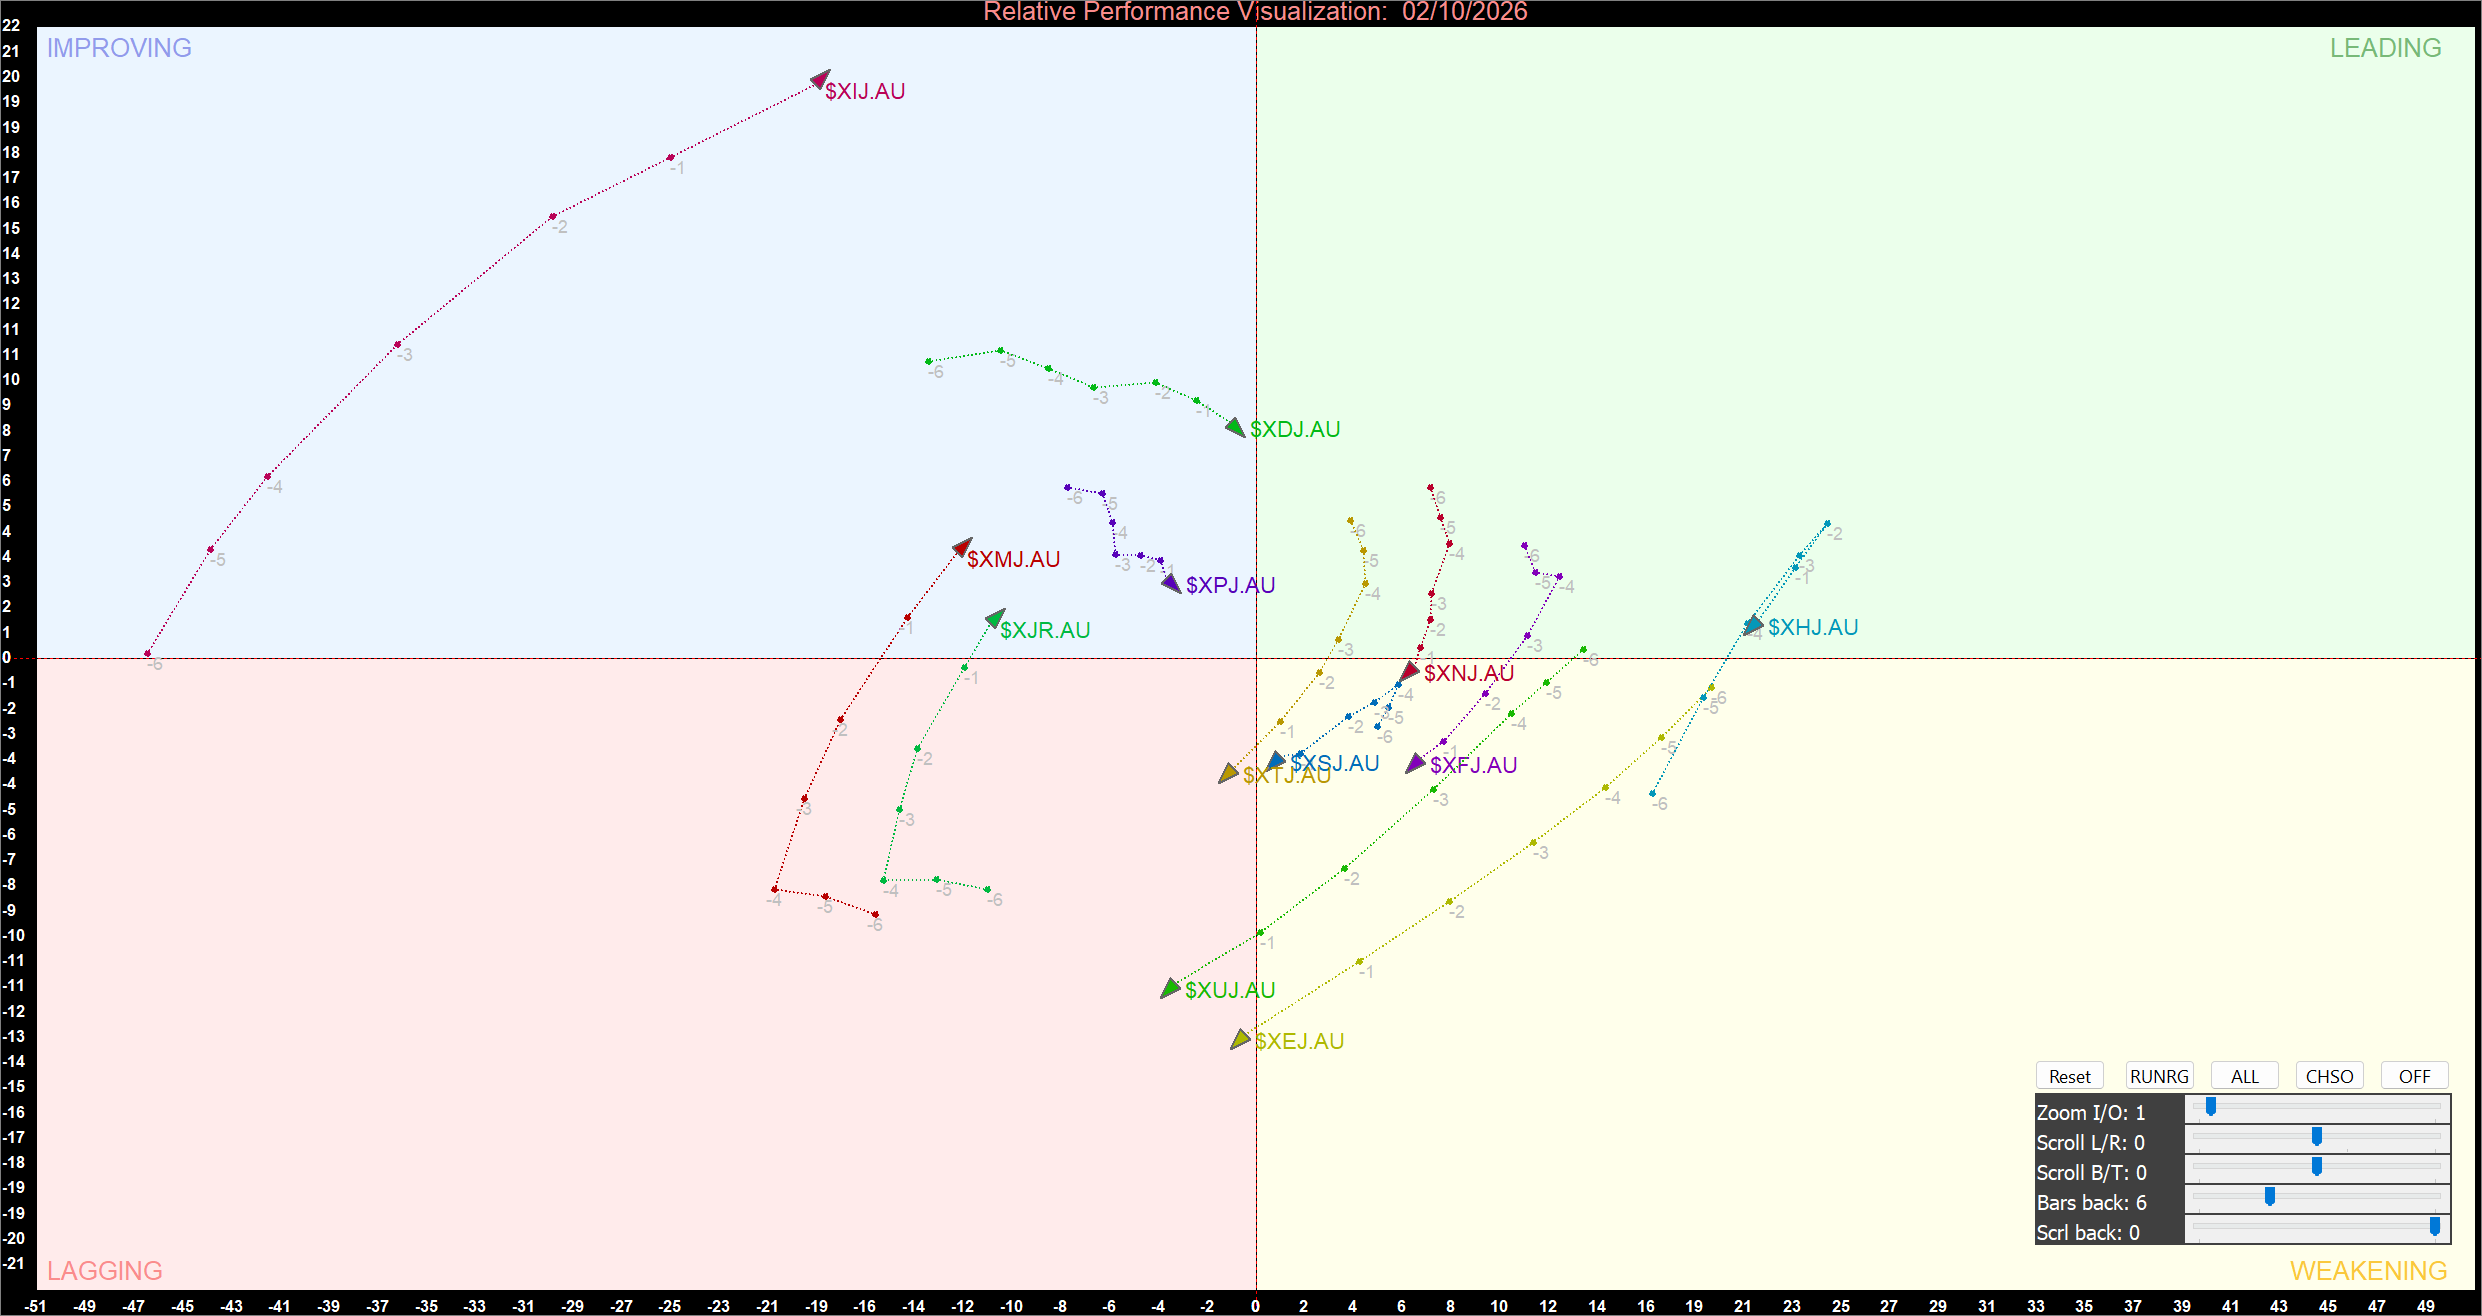
ASX Sector Relative Momentum Chart at the closing price of 2/10/2026. Powered by: amibroker.com
Leading Quadrant
Health Care (XHJ) is the only sector positioned in the Leading quadrant. Its location above the horizontal midpoint and to the right of the vertical axis indicates relatively stronger momentum and relative strength compared with the broader market.
However, Health Care declined 1.10% during the session, making it the second-weakest performer among the twelve sectors. This contrast demonstrates that RRG positioning does not simply represent the latest daily return. Instead, the chart captures the broader direction of relative momentum and relative strength.
The position of Health Care will therefore remain important. Continued movement further into the Leading quadrant would reinforce its leadership, while a sustained move back toward the centre could indicate deterioration in relative momentum.
Improving Quadrant
Information Technology (XIJ), Consumer Discretionary (XDJ), Materials (XMJ), Resources (XJR) and Real Estate (XPJ) are positioned in Improving.
Information Technology was the strongest-performing sector during the session, rising 4.45%. Its position high in the Improving quadrant, together with its upward trajectory, makes it the most notable momentum improvement on the chart. The combination of strong daily performance and an improving RRG trajectory suggests that technology is gaining relative momentum.
Consumer Discretionary advanced 0.85% and remains in Improving. Its position indicates that relative momentum is strengthening, although relative strength has not yet moved sufficiently to place the sector in Leading.
Materials and Resources gained 1.14% and 1.23%, respectively. Both sectors remain in Improving, indicating that their relative momentum is recovering from weaker positioning. Continued movement toward the centre and subsequently into the upper-right quadrant would provide stronger evidence of improving relative strength.
Real Estate was the weakest daily performer, declining 1.63%, yet it remains in Improving. This is an important example of why the RRG should not be interpreted as a simple daily performance ranking. Despite its negative session, the sector's broader trajectory remains consistent with improving relative momentum.
Weakening Quadrant
Consumer Staples (XSJ), Financials (XFJ) and Industrials (XNJ) are positioned in the Weakening quadrant.
Consumer Staples gained 1.05%, while Financials advanced 1.03% and Industrials rose 0.45%. Despite these positive daily performances, all three sectors remain below the horizontal midpoint on the RRG.
Their positions indicate that relative momentum is deteriorating compared with the broader market. This divergence is particularly important because positive daily returns do not necessarily signal improving medium-term relative momentum.
A sustained movement back above the horizontal midpoint would provide evidence of renewed momentum, while further movement toward the lower-left area would increase the risk of a transition into Lagging.
Lagging Quadrant
Utilities (XUJ), Energy (XEJ) and Communication Services (XTJ) remain in the Lagging quadrant.
Energy gained 1.48%, recording the second-strongest daily performance among the twelve sectors. Utilities also advanced 0.73%, while Communication Services gained 0.54%. Nevertheless, all three remain in Lagging, reinforcing the distinction between daily price performance and broader relative strength.
Energy and Utilities are particularly notable because their plotted positions remain well below the horizontal midpoint. A sustained upward movement toward the centre of the chart would be required before either sector could be considered to have entered Improving.
Bottom Line
The 2 October 2026 ASX Relative Rotation Graph shows continued sector rotation and significant divergence in relative momentum. Health Care is the only sector positioned in Leading, while Information Technology, Consumer Discretionary, Materials, Resources and Real Estate occupy Improving.
Consumer Staples, Financials and Industrials remain in Weakening, while Utilities, Energy and Communication Services continue to occupy Lagging.
The most notable feature of the latest chart is the strong improving trajectory of Information Technology, which also recorded the strongest daily gain of 4.45%. At the same time, Health Care retains the strongest relative position despite declining 1.10% during the session. The divergence between daily performance and RRG positioning remains significant, with Energy and Utilities providing clear examples of sectors that gained during the session while remaining in Lagging.
Overall, the latest RRG suggests that sector Leadership remains dynamic. The trajectories of Information Technology, Materials, Resources and Consumer Discretionary Warrant close attention, while further deterioration in the Weakening and Lagging groups could reinforce the current rotation pattern.


 Nov 12, 2026





 Please wait processing your request...