
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Momentum Shifts
- Health Care (XHJ), Information Technology (XIJ), Materials (XMJ), Resources (XJR) and Utilities (XUJ) are positioned in the Leading quadrant, indicating relatively strong momentum and relative strength.
- Health Care remains the strongest sector on the chart, while Information Technology continues to occupy a particularly strong relative position.
- Utilities (XUJ) has moved into the Leading quadrant, marking a positive improvement in relative momentum.
- Energy (XEJ), Financials (XFJ), Consumer Discretionary (XDJ), Real Estate (XPJ), Communication Services (XTJ), Consumer Staples (XSJ) and Industrials (XNJ) remain in Lagging.
- Seven sectors are positioned in Lagging, while no sectors currently occupy either the Improving or Weakening quadrants.
The latest Relative Rotation Graph (RRG) for 19 August 2026 indicates that sector momentum across the Australian Equity market remains highly selective. Health Care (XHJ), Information Technology (XIJ), Materials (XMJ), Resources (XJR) and Utilities (XUJ) occupy the Leading quadrant, maintaining a clear concentration of relative strength within a limited group.
The most notable positive shift is the movement of Utilities (XUJ) into Leading. At the same time, seven sectors remain in Lagging, highlighting continued weakness in overall momentum breadth despite the presence of several strong leaders.
Momentum Breakdown by Quadrant
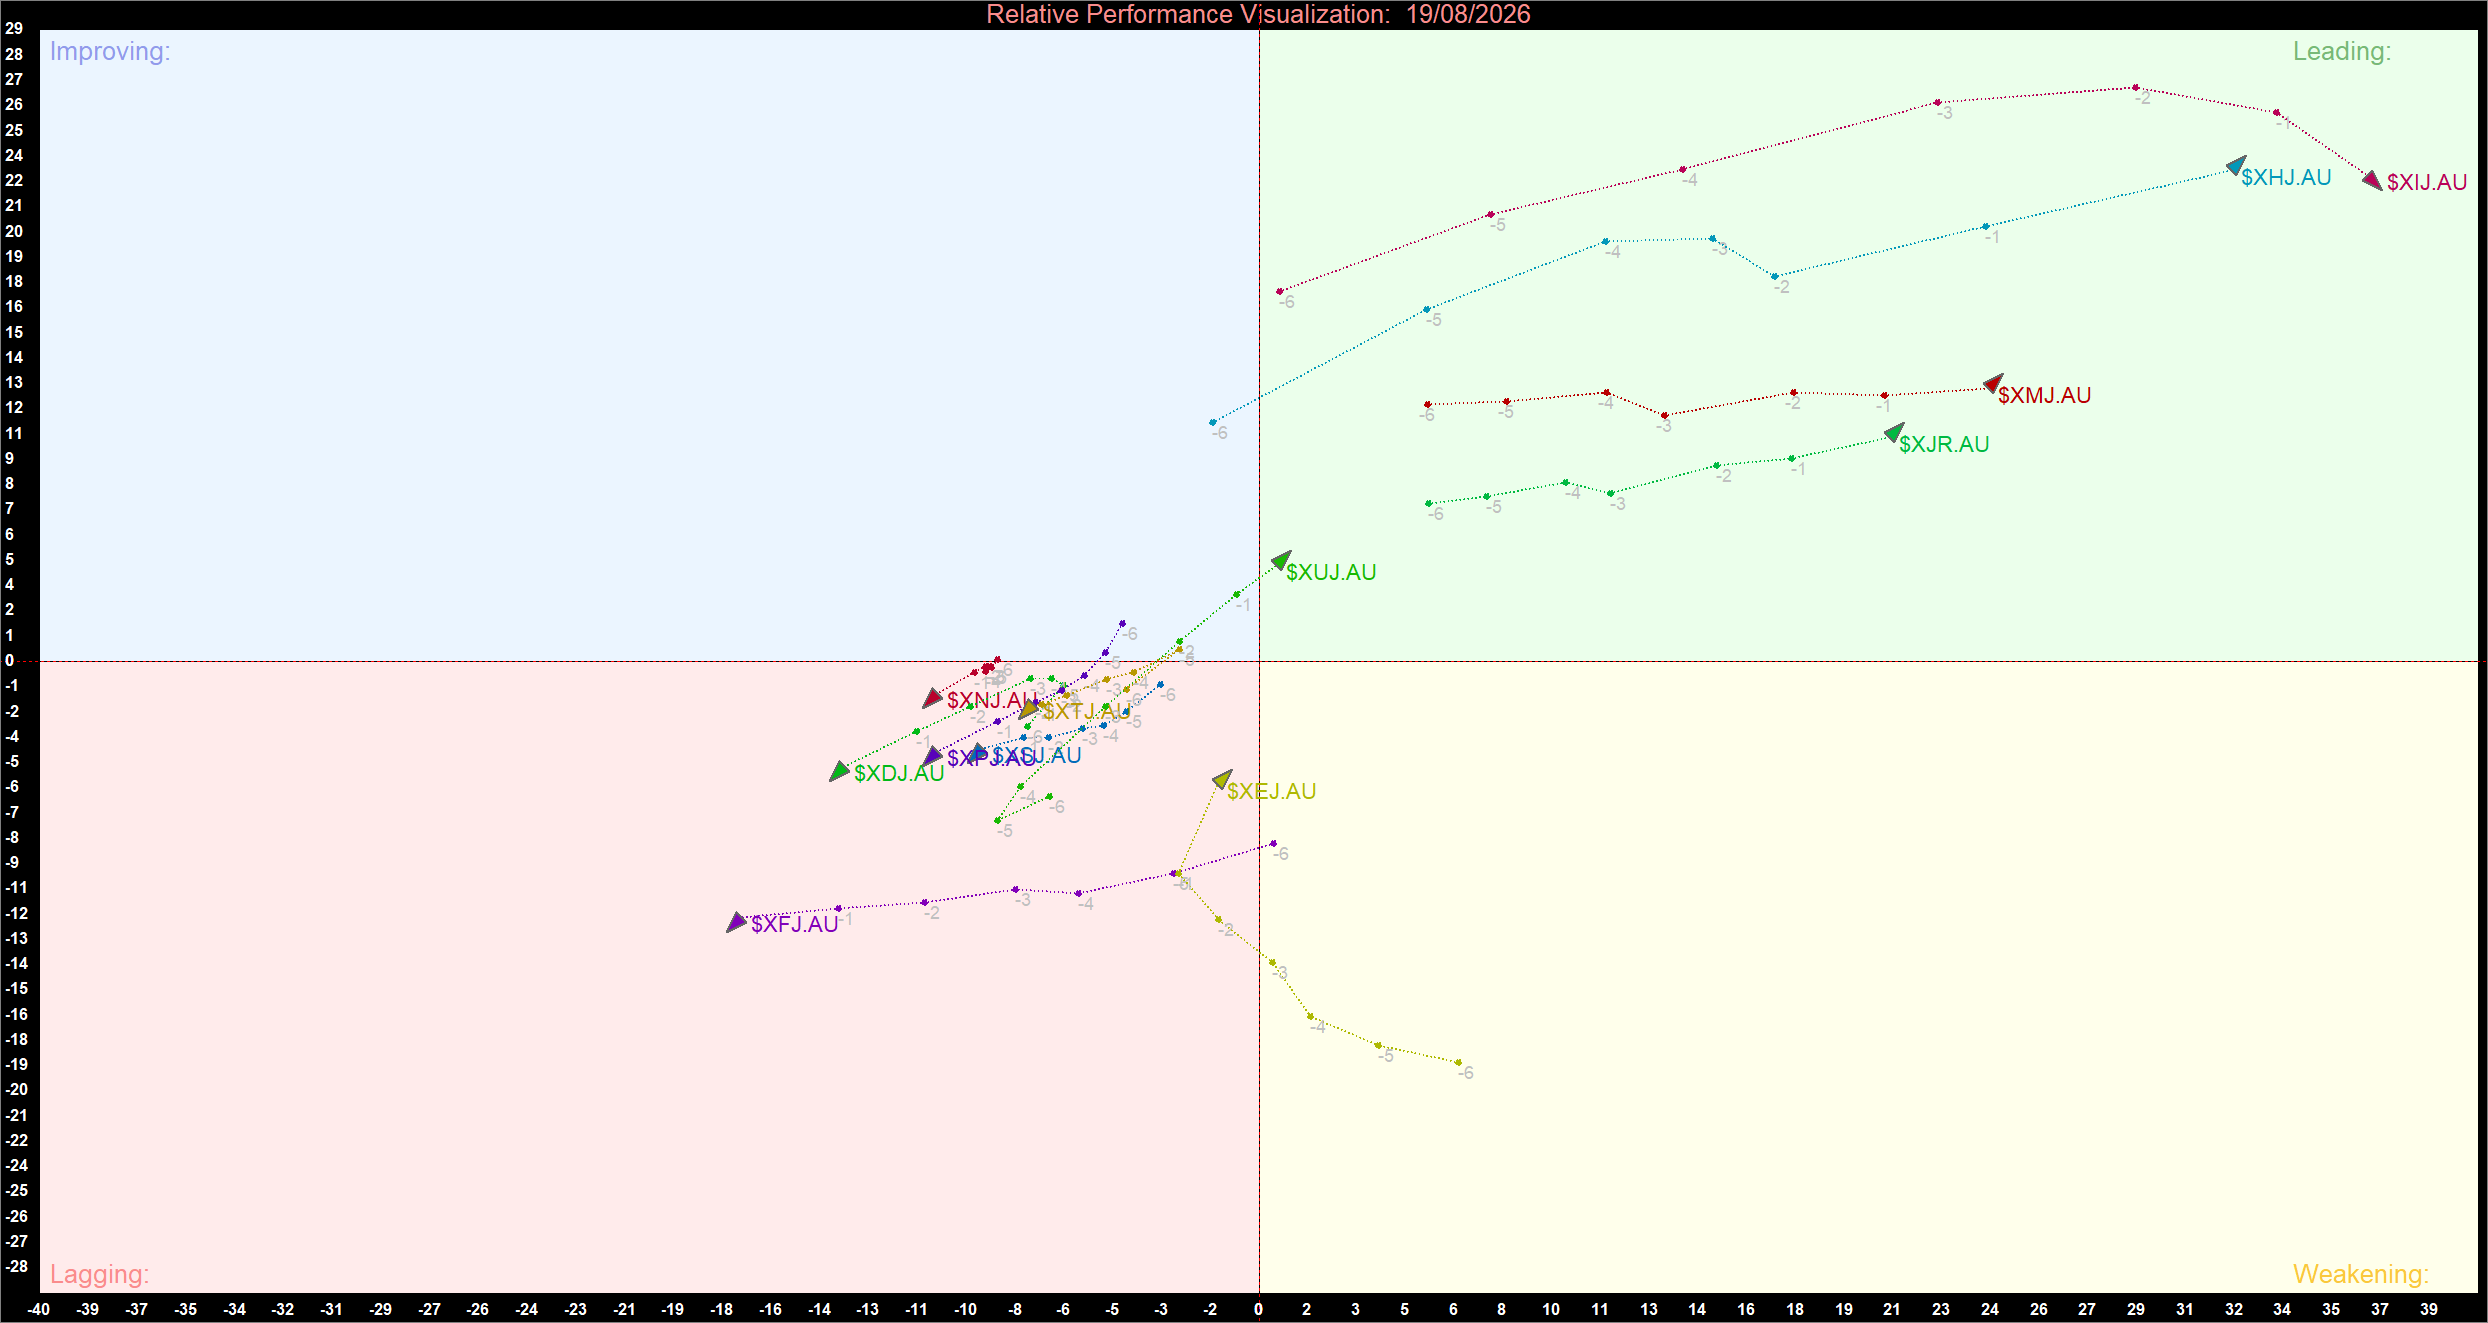
ASX Sector Relative Momentum Chart (at the closing price of 19/08/2026). Powered by: amibroker.com.
Leading Quadrant
The presence of five sectors in Leading indicates that Health Care, Information Technology, Materials, Resources and Utilities currently represent the principal sources of relative strength in the Australian equity market.
Health Care (XHJ) remains one of the strongest sectors on the chart and also recorded the strongest daily performance, gaining 2.60% on 19 August. Information Technology (XIJ) remains positioned strongly in Leading despite declining 3.15% during the latest session, highlighting the difference between short-term price performance and longer-term relative momentum.
Materials (XMJ) and Resources (XJR) also remain firmly positioned in Leading, although their daily performances were relatively modest at -0.07% and 0.09%, respectively.
Utilities (XUJ) has strengthened sufficiently to move into the Leading quadrant. Its position suggests that relative momentum has improved and that the sector is becoming a more important contributor to the market's Leadership structure.
The continued presence of five sectors in Leading indicates that leadership has broadened from the previous configuration. However, the concentration of relative strength within these sectors suggests that momentum remains unevenly distributed across the market.
Improving Quadrant
There are currently no sectors in the Improving quadrant.
The absence of sectors in Improving indicates that none of the lagging sectors has yet established a sufficiently strong improvement in relative momentum to signal a potential transition toward Leading.
This is an important feature of the latest RRG because it suggests that the current leadership structure remains relatively established, while the weaker sectors have yet to generate convincing rotation signals.
Weakening Quadrant
There are currently no sectors in the Weakening quadrant.
The absence of sectors in Weakening suggests that none of the current Leading sectors is showing a sufficiently significant deterioration in relative momentum to move through this quadrant.
This supports the view that the Leading group remains relatively stable, although continued monitoring of the trajectories of Health Care, Information Technology, Materials, Resources and Utilities will be important to identify any future deterioration.
Lagging Quadrant
Seven sectors are currently positioned in Lagging: Energy (XEJ), Financials (XFJ), Consumer Discretionary (XDJ), Real Estate (XPJ), Communication Services (XTJ), Consumer Staples (XSJ) and Industrials (XNJ).
Energy remains in Lagging despite gaining 0.77% during the latest session. This highlights that a positive daily return does not necessarily indicate improving relative momentum.
Financials declined 0.64%, while Consumer Discretionary fell 0.58% and Real Estate declined 1.15%. Communication Services, Consumer Staples and Industrials recorded only marginal daily movements, but their RRG positions remain within Lagging.
The concentration of seven sectors in Lagging continues to highlight relatively weak momentum breadth. A sustained move by these sectors toward the centre of the RRG and eventually into Improving would provide stronger evidence of a broader recovery in market participation.
Strategic Summary
The latest RRG shows that ASX sector momentum remains concentrated, although leadership has broadened with five sectors now positioned in Leading. Health Care, Information Technology, Materials, Resources and Utilities represent the strongest areas of relative momentum.
The move of Utilities into Leading is the key positive rotation in the latest RRG, while the continued presence of seven sectors in Lagging highlights the uneven nature of the market.
Health Care stands out as the strongest combination of relative momentum and recent price performance, gaining 2.60% in the latest session. By contrast, Information Technology remains a strong relative leader despite its sharp 3.15% daily decline, suggesting that short-term price weakness has not yet overturned its broader relative position.
Looking ahead, further strengthening in Utilities and sustained leadership from Health Care, Technology, Materials and Resources would support the current positive rotation. At the same time, movement of Financials, Consumer Discretionary, Real Estate, Communication Services, Consumer Staples, Industrials and Energy from Lagging into Improving would provide stronger evidence of a broader and more sustainable recovery in ASX sector momentum.


 Nov 12, 2026





 Please wait processing your request...