
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Momentum Shifts
- Consumer and Defensive Sectors Maintain Leadership: Consumer Staples (XSJ), Health Care (XHJ), Consumer Discretionary (XDJ), Communication Services (XPJ), and Clean Energy (XNJ) remain positioned within the Leading quadrant, although momentum trends are becoming increasingly mixed.
- Financials and Utilities Continue Building Momentum: Financials (XFJ) and Utilities (XUJ) remain firmly established in the Improving quadrant, displaying constructive North-East trajectories that reinforce their potential transition into market leadership.
- Materials, Real Estate, and Energy Remain Structural Laggards: Materials (XMJ), Real Estate (XJR), and Energy (XEJ) continue to occupy the Lagging quadrant, reflecting persistent relative weakness compared with the broader market.
- Industrials Show Further Momentum Deterioration: Industrials (XIJ) remains deeply embedded in the Weakening quadrant and has moved further away from the leadership group, highlighting ongoing institutional selling pressure.
The ASX sector rotation landscape on June 23, 2026, continues to reflect a market characterised by defensive leadership and selective risk-taking. Investors remain concentrated in sectors demonstrating superior relative strength, while economically sensitive sectors continue to struggle. The latest RRG configuration suggests that market participants remain cautious regarding the broader economic outlook, favouring stability and earnings resilience over cyclical exposure.
ASX Sector Momentum Summary
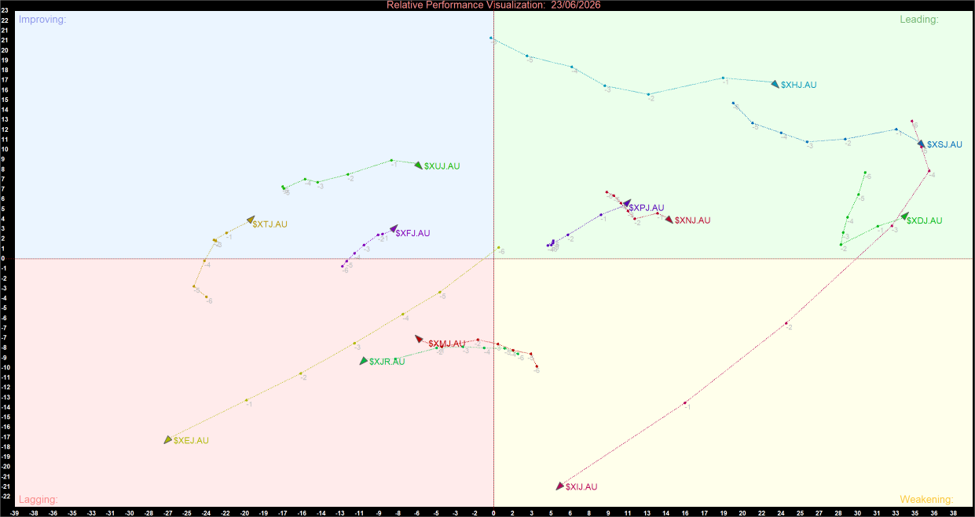
ASX Sector Relative Momentum Chart (at the closing price of 23/06/2026). Powered by: amibroker.com
Momentum Breakdown by Quadrant
The Leading Quadrant (The Market Leaders)
- Health Care (XHJ): Continues to occupy one of the strongest positions on the Relative Rotation Graph. Although momentum has moderated slightly from recent highs, the sector remains firmly entrenched within the Leading quadrant and continues to exhibit superior relative strength.
- Consumer Staples (XSJ): Remains a key defensive leader. While short-term momentum has softened, the sector continues to demonstrate robust relative performance and remains well-positioned within the leadership group.
- Consumer Discretionary (XDJ): Continues to advance within the Leading quadrant. The recent upward trajectory suggests improving investor confidence and increasing participation in consumer-facing companies.
- Communication Services (XPJ): Remains within the Leading quadrant despite experiencing some loss of momentum. Relative strength remains supportive, although further deterioration could place its leadership position at risk.
- Clean Energy (XNJ): Holds its position within the Leading quadrant, though recent momentum weakness suggests investors may be becoming more selective toward renewable-energy exposures following previous gains.
The Improving Quadrant (The Emerging Leadership Candidates)
- Utilities (XUJ): Continues to display one of the strongest momentum profiles on the chart. The sector is moving steadily toward the Leading quadrant as investors increasingly favour defensive earnings and yield-oriented opportunities.
- Financials (XFJ): Remains among the most constructive sectors on the RRG. Momentum continues to improve, and the sector appears increasingly likely to transition into the Leading quadrant if current trends persist.
- Information Technology (XTJ): Continues its recovery within the Improving quadrant. Relative momentum has strengthened noticeably, suggesting that technology stocks may be entering the early stages of a broader leadership recovery.
The Weakening Quadrant (Leadership Under Threat)
- Industrials (XIJ): Remains isolated within the Weakening quadrant and continues to deteriorate. The sector's deep position within this quadrant reflects significant momentum loss and ongoing institutional distribution. Unless momentum stabilises, Industrials may continue to underperform the broader market in the near term.
The Lagging Quadrant (The Structural Underperformers)
- Materials (XMJ): Continues to struggle within the Lagging quadrant. Relative strength remains weak as investors reduce exposure to resource-related sectors amid uncertain commodity demand expectations.
- Real Estate (XJR): Remains firmly positioned within Lagging. Property stocks continue to face headwinds from economic uncertainty and shifting capital flows toward sectors displaying stronger momentum characteristics.
- Energy (XEJ): Although still deeply embedded within the Lagging quadrant, the sector has continued to rotate gradually North-East. This suggests selling pressure may be easing and that a longer-term recovery process could be developing, although confirmation remains absent.
Strategic Summary
The latest RRG configuration continues to favour defensive and consumer-oriented sectors, with Health Care (XHJ), Consumer Staples (XSJ), Consumer Discretionary (XDJ), Communication Services (XPJ), and Clean Energy (XNJ) maintaining positions within the Leading quadrant.
Meanwhile, Financials (XFJ), Utilities (XUJ), and Information Technology (XTJ) remain the strongest candidates for future leadership, supported by steadily improving momentum profiles.
Conversely, Materials (XMJ), Real Estate (XJR), and Energy (XEJ) continue to lag the broader market, while Industrials (XIJ) remains the weakest area of the ASX universe. Until economic visibility improves and cyclical sectors regain momentum, market leadership is likely to remain concentrated in defensive sectors, consumer-oriented industries, and selected growth opportunities.


 Nov 12, 2026





 Please wait processing your request...